
Story
Williams-Sonoma Stock Falls Despite Strong Earnings and Upgraded Forecast
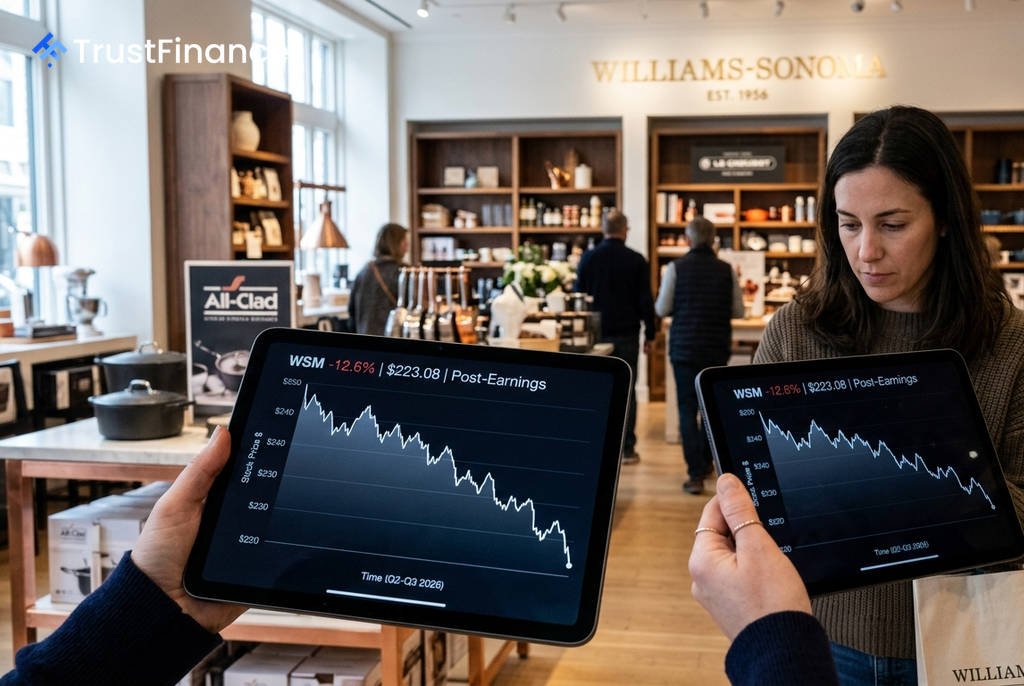
Shares of Williams-Sonoma (NYSE: WSM) have declined approximately 12.6% from their 52-week high, a notable pullback that occurred immediately after the company reported second-quarter earnings that beat analyst expectations and raised its full-year guidance.
The move suggests a classic "sell-the-news" scenario, where high investor expectations were already priced into the stock ahead of the announcement, according to a report from Investing.com. As of early trading on September 4, the stock was priced at $223.08, down from a peak of $254.89.
A Strong Quarter Undercut by Market Reaction
Williams-Sonoma reported strong financial results for its second quarter. The company posted an adjusted earnings per share (EPS) of $2.10, surpassing the consensus estimate of $2.06. Revenue also came in ahead of forecasts at $1.96 billion, compared to an expected $1.92 billion.
Following the performance, the company raised its full-year outlook. It now expects comparable sales growth between 4.0% and 6.5% and an adjusted operating margin in the range of 17.8% to 18.2%. Despite these positive indicators, the stock slid roughly 4.6% in the immediate aftermath of the report.
Conflicting Valuation Views
 Ad
The retailer's underlying fundamentals remain robust, with a return on equity (ROE) of 55.0% and a return on invested capital (ROIC) of 30.1%, figures considered best-in-class for the specialty retail sector. However, Wall Street and quantitative models present a divided outlook on the stock's valuation.
- Analyst Bull Case: Several Wall Street firms remain bullish, with price targets implying significant upside. Jefferies has a target of $275, KeyBanc targets $270, and Bank of America targets $261.
- Quantitative Bear Case: In contrast, InvestingPro's quantitative fair value model suggests the stock is overvalued, flagging a potential 15.9% downside with a fair value estimate of $187.32.
Tariff Pressures Remain a Headwind
A key risk factor weighing on the company is the impact of tariffs on imported goods. In the second quarter, Williams-Sonoma's adjusted operating margin contracted by 60 basis points year-over-year to 17.3%, a decline the company directly attributed to tariff costs.
Management's updated guidance for the fiscal year assumes that all current tariffs, including Section 232 and new Section 301 tariffs, will remain in place. This ongoing margin pressure from trade policy remains a significant headwind for the company, potentially limiting further expansion of its valuation multiple.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.