
Story
SpaceX Gets $800 Target as Analysts Diverge on Salesforce, Shopify AI Plays
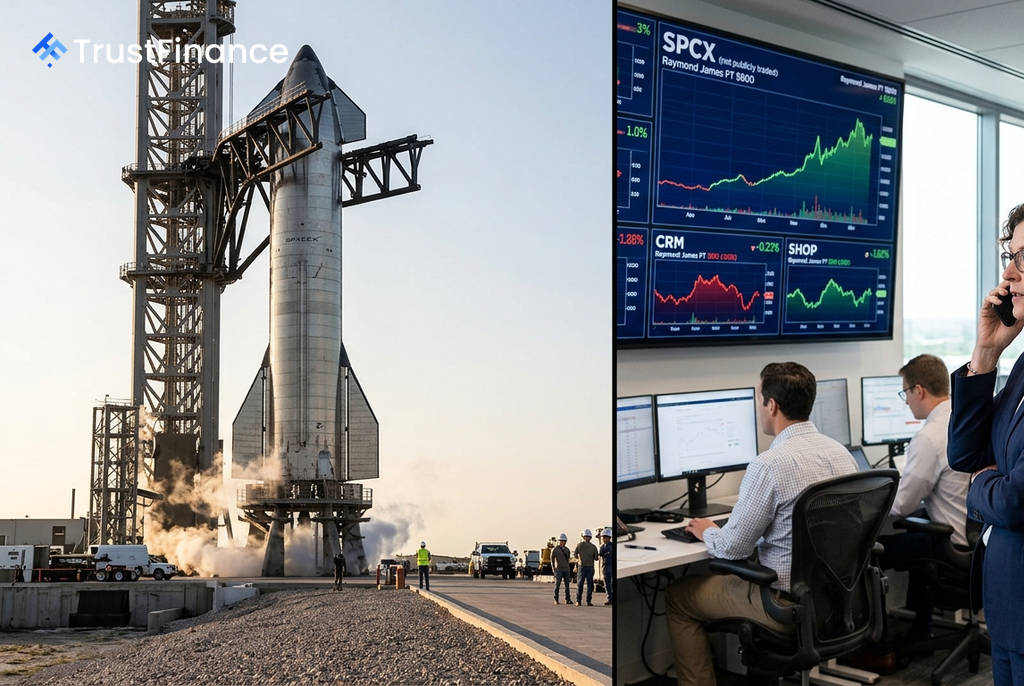
A flurry of analyst reports this week highlighted diverging views on key players in the artificial intelligence space, with Raymond James initiating coverage on SpaceX with a Street-high price target, while Bernstein downgraded Salesforce citing poor feedback on its AI offerings.
SpaceX Earns Street-High Target in Bullish Initiation
Raymond James initiated coverage of SpaceX with a Strong Buy rating and an $800 price target, arguing that the company is building the foundational platform for the next generation of industrial capacity. The firm's thesis centers on Starship, which it says will reduce the cost of transporting mass to orbit by over 99%, transforming orbital launch into a commercial transportation network.
Analyst Brian Gesuale estimates SpaceX's total addressable market approaches $30 trillion. The firm projects SpaceX's revenue will grow from approximately $38.5 billion today to over $837 billion by 2031, with EBITDA expanding from $17.7 billion to $696 billion over the same period. Gesuale highlighted a "powerful infrastructure flywheel" where Falcon funds Starlink, Starlink funds Starship, and Starship enables future platforms.
Divergent Views on Software and E-commerce
Analysts took opposing stances on major software and e-commerce platforms, with AI readiness being a key factor.
 Ad
- Salesforce (CRM): Bernstein downgraded the stock to Sector Weight from Outperform, removing its price target. The firm cited weak customer feedback on the Agentforce AI product, with checks revealing that customer data is often not organized for AI and that the product "just isn’t there." A recent CIO survey also indicated more IT departments expect to deprioritize Salesforce spending over the next year.
- Shopify (SHOP): In contrast, Stifel upgraded Shopify to Buy and raised its price target to $150 from $110. The analyst noted that a recent stock decline has created an attractive entry point. Stifel sees a "realistic path to 30%-plus revenue growth in 2026" as the company gains market share and writes the "agentic commerce playbook."
Analysts See Value in Asian Tech
Bank of America reiterated its Buy rating on Alibaba, calling it "one of the most compelling AI plays in China" with a $172 price objective. The bank expects AI-led demand to push Alibaba's cloud revenue growth to 45% year-over-year in the June quarter, up from 38% previously.
Meanwhile, Mizuho analyst Jordan Klein called the recent sell-off in Samsung an overreaction to its preliminary Q2 results. Klein argued the revenue miss was driven by mobile devices and TVs, not the critical memory business. He noted that the implied memory operating margins were over 80% and that third-quarter pricing trends for DRAM and NAND look "very strong."