
Story
Plug Power Stock Jumps on Q2 Revenue Beat, Margin Improvement
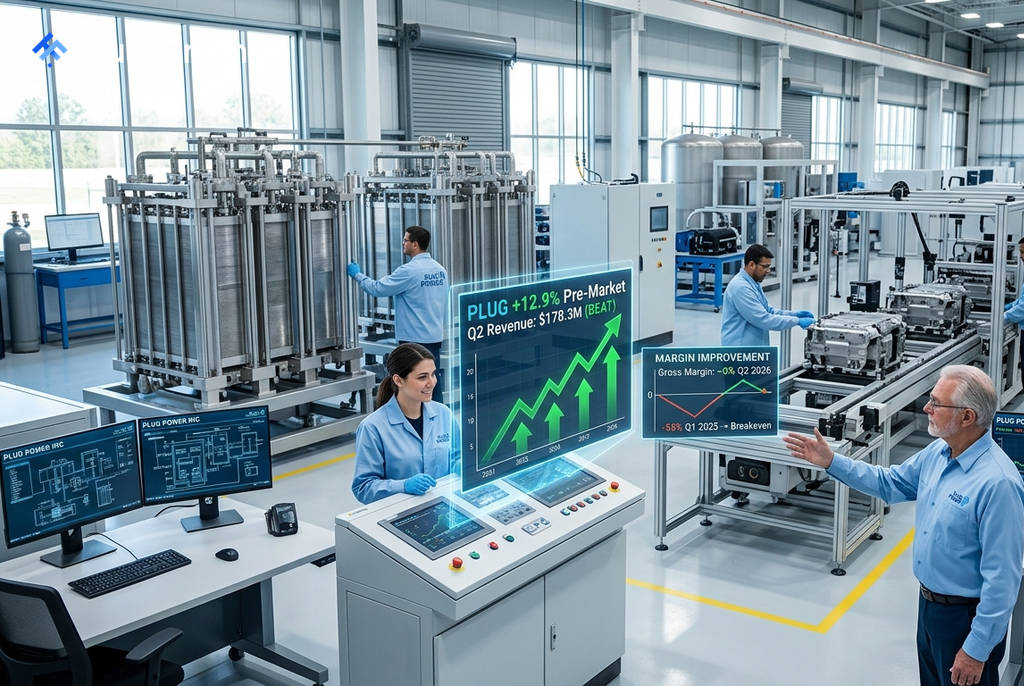
Plug Power (NASDAQ: PLUG) reported second-quarter financial results that beat analyst expectations on revenue and showed significant progress in improving its gross margins, causing its stock to surge 12.9% in pre-market trading. The company also raised its full-year revenue growth guidance to a range of 15% to 16%.
Turnaround Signs Emerge
The company announced Q2 revenue of $178.3 million, surpassing the consensus estimate of $168.8 million. A key highlight for investors was the substantial improvement in profitability metrics. Gross margin reached nearly breakeven, a dramatic turnaround from deeply negative levels in previous periods.
According to the company, this represents a 55 percentage point recovery in gross margin over the last 12 months. The improvement was attributed to cost-cutting initiatives and a more than 30% year-over-year drop in GenDrive service costs. The company's electrolyzer business also showed strong growth, with a newly announced 50 MW order from Orica in Australia.
Cash Position Remains a Key Focus
Despite the operational improvements, Plug Power's liquidity continues to be a central concern for investors. The company ended the quarter with $162 million in unrestricted cash after a cash burn of $61 million, though this was a 58% sequential decrease.
 Ad
Management is actively working to bolster its balance sheet through asset monetization, announcing $80 million in transactions after the quarter ended, with $47 million already received. The company is also awaiting a final decision on a $1.6 billion loan term sheet from the Department of Energy, which would fund the development of up to six hydrogen production facilities.
Outlook and Analyst Reaction
Looking ahead, management has set a target to achieve positive EBITDAS by the fourth quarter of 2026, a milestone analysts see as a make-or-break moment for the company. The Wall Street consensus rating on the stock is a Hold, with an average price target of $3.55.
Analysts acknowledged the strong quarterly performance but remain cautious. Canaccord Genuity maintained a Hold rating, citing execution risk, while Oppenheimer noted the company's significant trailing twelve-month EBITDA loss of -$614 million. The company's large cash burn and $1.01 billion in total debt remain key risks for the bull case.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.