
Story
Paycom Highlighted for Valuation and Capital Efficiency in Mid-Cap Tech Analysis
Summary
An analysis of U.S. mid-cap technology stocks identifies Paycom (PAYC) as a standout, citing a strong balance of attractive valuation, superior capital efficiency, and potential for recovery compared to peers.
Paycom (PAYC) has been highlighted as a leading U.S. mid-cap technology stock, distinguished by what an Investing.com analysis calls a compelling mix of quality, valuation, and recovery potential.
Comparative Analysis
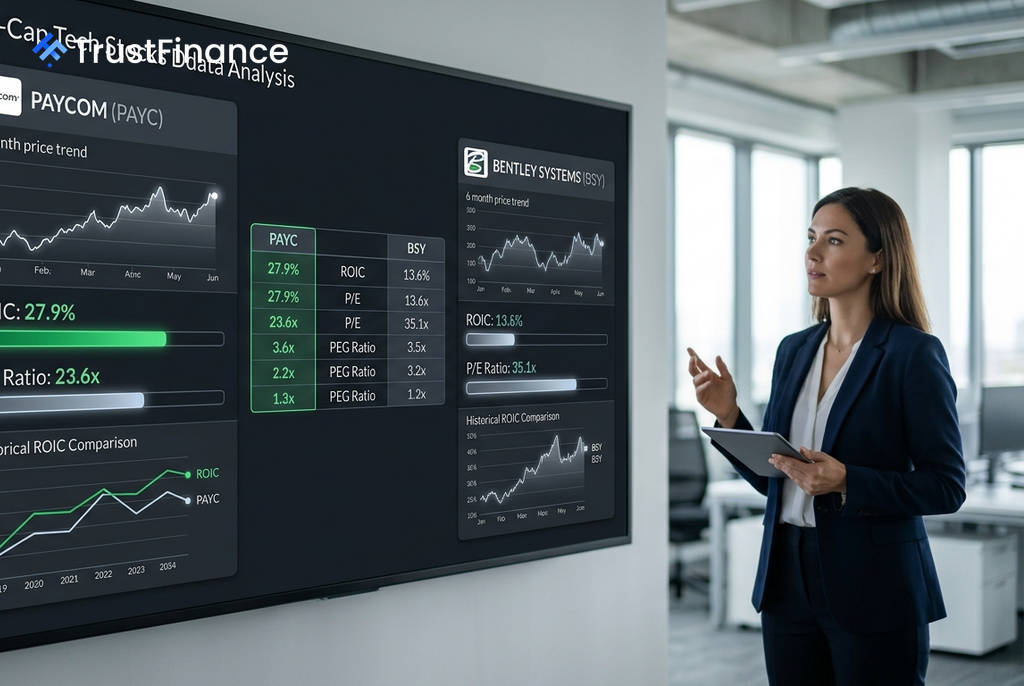
A comparison with peer Bentley Systems (BSY) underscores the key differences in financial metrics that favor Paycom, according to a stock screener cited in the September 14 report. The analysis points to Paycom's more efficient use of capital and more attractive valuation multiples.
Key metrics for the two companies include:
- Return on Invested Capital (ROIC): Paycom at 27.9% versus Bentley Systems at 13.6%.
- Price-to-Earnings (P/E) Ratio: Paycom at 23.6x compared to Bentley Systems at 35.1x.
- Revenue Growth: Paycom at 9.2% and Bentley Systems at 12.8%.
- PEG Ratio: Paycom at 0.76, significantly lower than Bentley Systems' 2.14.
The Case for Paycom
 Ad
The report emphasizes Paycom's superior capital efficiency, noting its ROIC is more than double that of Bentley Systems. This suggests the company generates higher returns from the capital it deploys. The valuation is also described as "friendlier," supported by its lower P/E and PEG ratios.
Furthermore, the analysis points to Paycom's strong cash generation, highlighting a 5.9% free cash flow (FCF) yield. These factors combine to build a case for the company as a quality investment at a reasonable price, according to the source.
Investor Considerations
While Paycom's fundamentals appear strong, the report clarifies that it does not represent a high-growth momentum story. The focus has been on whether its 9.2% revenue growth can reaccelerate. The investment thesis is framed around quality and value rather than rapid expansion.
In contrast, Bentley Systems offers a stronger growth profile. However, its higher valuation leaves less room for execution delays, particularly as the report notes that significant monetization from AI initiatives is not anticipated until 2027.
Read next
More on Stocks
BOJ Rate Hike Nears, Pitting Japanese Financials Against Exporters
The Bank of Japan is widely expected to raise its key interest rate to a 31-year high this week, a move that is creating a sharp divide in the stock market between beneficiaries like banks and sectors facing pressure, such as exporters.

Genscript Biotech Stock Surges Over 16% on Eli Lilly AI Partnership
Shares in the Hong Kong-listed biotech firm rallied after announcing a collaboration with Eli Lilly's AI-powered drug discovery platform, a move supported by a recent capital raise focused on AI infrastructure.

Volkswagen's Seat Brand Faces Discontinuation Amid Chinese EV Pressure
Volkswagen is reportedly set to phase out its historic Spanish brand, Seat, as part of a major restructuring to combat rising competition from Chinese automakers and focus investment on its profitable, all-electric Cupra marque.

Hong Kong Biotech Sector Shows Stark Divide as Biocytogen, Genscript Post Major Gains
A small group of companies, led by Biocytogen Pharmaceuticals and Genscript Biotech, have delivered substantial one-year returns, highlighting a sharp performance gap within Hong Kong's 52-stock biotech universe where most firms remain unprofitable.