
Story
Palantir Stock Faces Valuation Scrutiny Despite Strong Growth Metrics
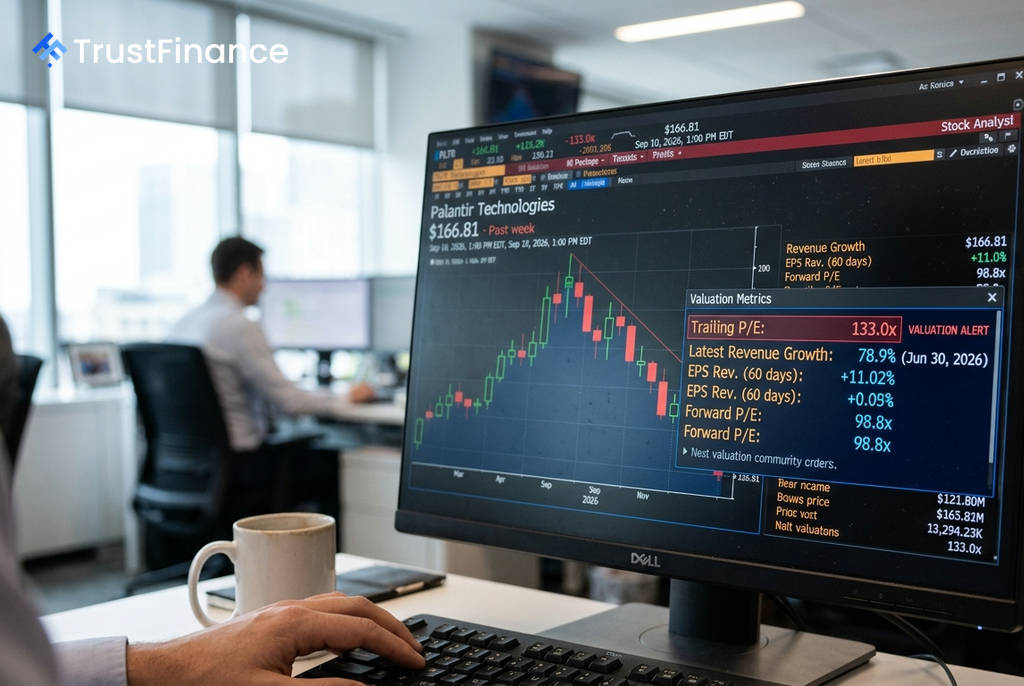
Palantir Technologies (PLTR) presents a divided outlook for investors, with exceptional operational growth and profitability running against a steep valuation that leaves little margin for error. The data analytics firm's strong fundamentals are being weighed against a trailing price-to-earnings ratio that stands at over 130 times.
Impressive Growth and Profitability
Palantir has demonstrated a robust growth trajectory and strong financial health. The company's operational performance is highlighted by several key metrics from its recent financial disclosures:
- Revenue Growth: Annual revenue surged from $1.54 billion in 2021 to $4.48 billion in 2025. The most recent revenue growth metric was 78.9% as of June 30, 2026.
- Profitability: The company reported a gross margin of 84.8% and a net-income margin of 49.0% as of the same date.
- Strong Cash Flow: Palantir generated $3.36 billion in levered free cash flow with minimal debt of just $211.40 million, providing significant flexibility to fund expansion.
Furthermore, the company has consistently surpassed earnings expectations. In its latest quarterly report on August 3, 2026, Palantir posted an EPS of $0.41, beating the consensus estimate of $0.34, on revenue of $1.94 billion versus an expected $1.81 billion.
A Tale of Two Valuations
 Ad
Despite its strong performance, Palantir's stock valuation is a primary point of concern. The company trades at a 133.0x trailing P/E and a 98.8x forward P/E, suggesting that significant future growth is already priced into the stock.
Valuation models present a sharp disagreement on the stock's future. An Investing.com fair value model calculated as of September 10, 2026, suggests a price of $129.60, implying a -22.3% downside from its current level. In contrast, aggregate analyst price targets indicate a potential upside of 20.9% as of June 30, 2026.
Conflicting Market Sentiment
The market's sentiment towards Palantir is similarly fractured. Positive momentum is supported by strong product adoption and strategic partnerships, such as an expanded relationship with Fujitsu to improve international distribution. The company is also showcasing customer adoption at its AIPCon 11 conference.
However, technical indicators are conflicted. While weekly and monthly signals show a "Strong Buy," the daily signal is a "Sell," according to the source's analysis. This suggests that short-term selling pressure is currently testing a much stronger long-term uptrend. The key question for investors is whether Palantir's growth can continue at a pace sufficient to justify its premium valuation, with the next earnings release on November 9, 2026, serving as a critical checkpoint.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.