
Story
Murata Manufacturing Stock Falls 30% Despite Earnings Beat and Raised Forecast
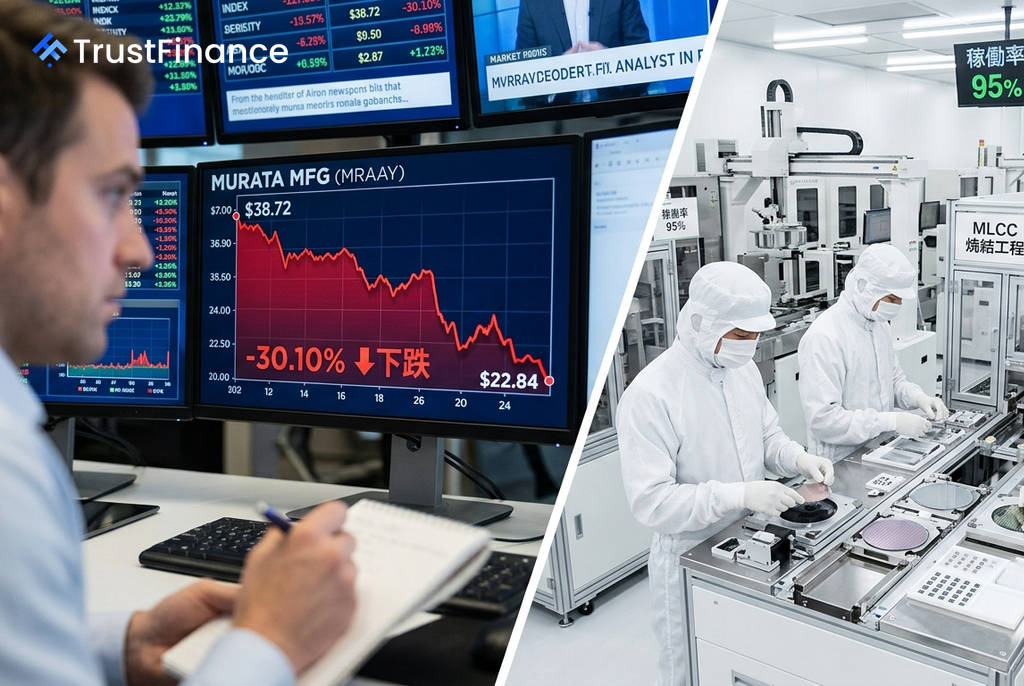
Shares of Japanese electronic components maker Murata Manufacturing (MRAAY) have fallen approximately 30% over the past month, a significant pullback that appears disconnected from the company's strengthening fundamental performance. The decline follows a period of rapid appreciation where the stock gained over 400% from its 52-week low, according to a report from Investing.com.
Financials Outpace Market Sentiment
Despite the negative stock performance, Murata recently reported strong financial results. The company posted a first-quarter operating profit of ¥98.5 billion, beating consensus estimates of ¥89.3 billion by about 10%.
Furthermore, Murata raised its full-year operating profit guidance by 13% to ¥430 billion. This positive revision is underpinned by surging demand for its multilayer ceramic capacitors (MLCCs), critical components in everything from smartphones to data centers.
Surging Demand from AI and Automotive
Several key indicators point to robust underlying business momentum for the electronics supplier. The company's positive outlook is supported by:
 Ad
- A high factory utilization rate of 95% for its MLCCs.
- A strong book-to-bill ratio of 1.47x, indicating that new orders are significantly outpacing current shipments.
- A 40% quarter-over-quarter increase in demand for MLCCs used in AI servers.
- An upgraded full-year sales forecast for MLCCs, now expected to grow 24% year-over-year, up from a previous estimate of 13%.
- A revised forecast for AI and data center-related sales, which are now projected to double (+100% year-over-year).
Market Correction and Margin Headwinds
The sharp sell-off in the stock is seen by some analysts as a market correction, or mean-reversion, after its substantial run-up. Investors may also be weighing potential headwinds, including rising labor and IT costs.
A shifting product mix toward automotive components, which can carry lower margins than premium AI-related parts, could also be tempering investor enthusiasm. While revenues are growing robustly, profitability may not be expanding at the same pace, presenting a potential concern for future margin performance.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.