
Story
Memory Chip Stocks Micron and SanDisk Enter Deep Correction Territory
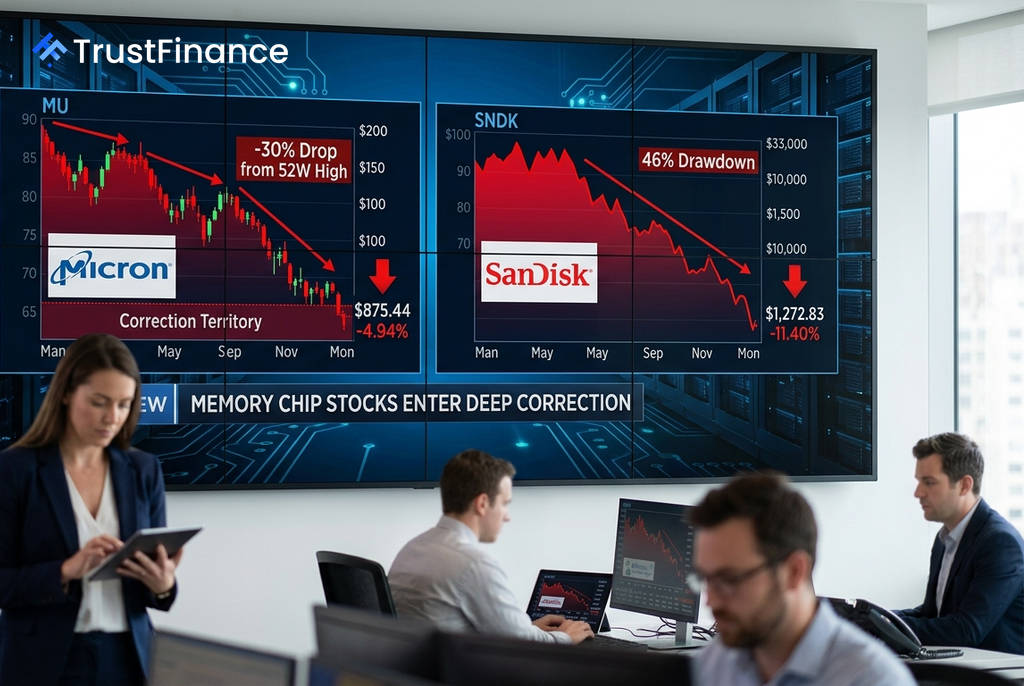
Shares of semiconductor leaders Micron (MU) and SanDisk (SNDK) have plunged into correction territory, erasing a significant portion of their recent massive gains. As of July 27, Micron stock is down 30% from its 52-week high, while SanDisk has seen a much steeper decline, falling 46% from its peak.
A Tale of Two Drawdowns
Despite the similar downward trend, the two companies present different profiles for investors. Micron, a $990.9 billion market-cap behemoth, has experienced a more moderate pullback compared to the $188.7 billion SanDisk, whose shares have been nearly cut in half.
SanDisk's more severe drawdown offers potentially higher leverage for a rebound but also carries greater risk. Both companies have delivered enormous year-to-date returns even with the recent sell-off, with Micron up 197.5% and SanDisk gaining 422.1%.
Earnings Catalysts and Analyst Outlook
A key distinction lies in their earnings performance and near-term catalysts. Micron has a track record of four consecutive quarters of beating analyst estimates, including a +22.6% earnings per share surprise in its fiscal third quarter of 2026. In contrast, SanDisk delivered an even larger +59.7% EPS surprise in its most recent report.
All eyes are on SanDisk's upcoming earnings release scheduled for August 5, which is seen as a pivotal event that could either accelerate its decline or trigger a sharp recovery. Analyst sentiment for Micron remains strong, with firms like Citi, UBS, and BofA reiterating 'Buy' ratings. SanDisk has a vocal bull in Evercore ISI, which holds an 'Outperform' rating and a $3,100 price target, implying over 140% upside. However, InvestingPro’s fair value model suggests a more modest valuation of $1,630 for SNDK.
 Ad
Sector-Wide Headwinds
Investors are also weighing several bearish signals that could impact the broader memory chip sector. These potential risks include:
- Notable short interest: Famed investor Michael Burry initiated put options on Micron in early July.
- Increased competition: China’s largest DRAM manufacturer, CXMT, is planning an IPO after reporting 719% year-over-year revenue growth, signaling a potential increase in global supply.
- Customer hedging: Major client CoreWeave is reportedly exploring derivative contracts to hedge against potential declines in memory prices.
- Insider activity: Micron experienced its highest level of insider selling since 2010 in late June.
Investor Choice: Stability vs. Volatility
The current market presents a choice between two distinct investment theses. Micron is viewed as a more diversified and defensible option, with exposure to DRAM, NAND, and HBM memory and durable demand from the automotive sector. Its consensus EPS forecast for fiscal 2027 of $154.18 suggests a long-term growth trajectory.
SanDisk represents a higher-risk, higher-reward trade centered on its upcoming earnings. The stock's extreme volatility is a key feature for traders, but significant uncertainty is reflected in its next-quarter EPS estimate of just $1.61, a sharp drop from $23.41 in the prior quarter.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.