
Story
Global Bond Yields Stabilize After U.S.-Iran Conflict Triggers Inflation Fears
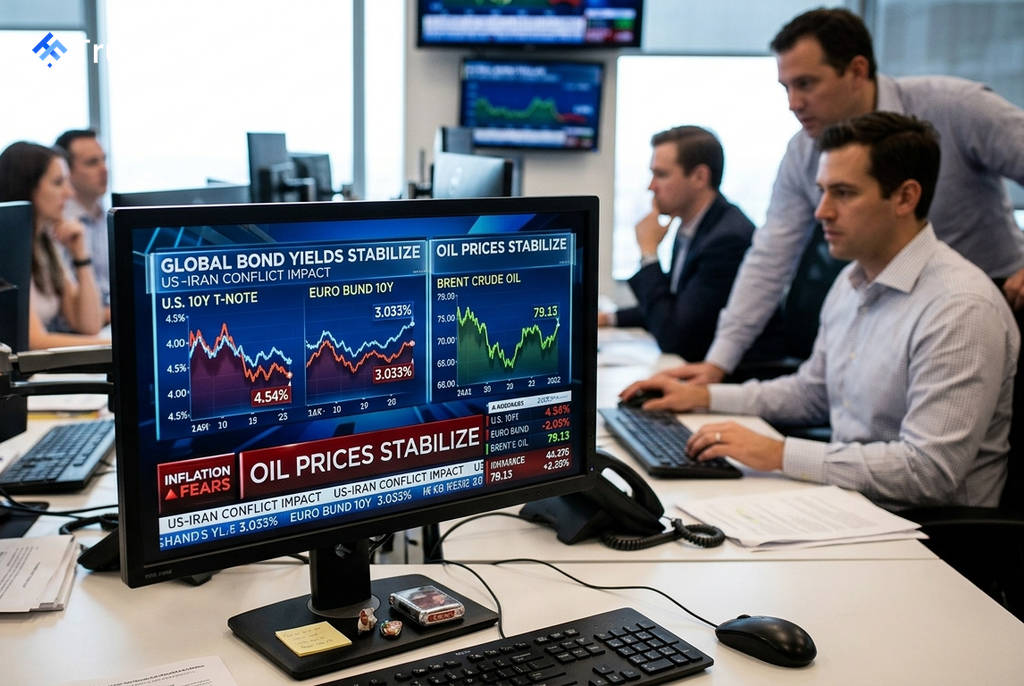
U.S. and European government bond yields steadied on Friday, pausing a sharp sell-off that marked the largest two-day spike in months. The bond market rout was triggered by escalating military conflict between the United States and Iran, which stoked fears of a new wave of energy-driven inflation.
Yields Consolidate at Multi-Week Highs
Fixed-income markets caught their breath after two sessions of heavy selling. Key benchmark yields stabilized but held near recently established highs:
- The yield on the benchmark 10-year U.S. Treasury note eased slightly to 4.54%, consolidating near a two-month peak.
- The two-year U.S. Treasury yield, which is highly sensitive to Federal Reserve interest rate expectations, hovered around 4.18%.
- Germany’s 10-year Bund yield, the benchmark for the eurozone, ticked up to 3.033%, holding near a seven-week high.
Geopolitical Shock Disrupts Markets
The violent repricing in government bonds followed the collapse of a fragile June 17 ceasefire between Washington and Tehran. The sell-off was ignited after the U.S. struck Iranian targets, which was followed by retaliatory attacks from Tehran against American assets across Kuwait and Bahrain, according to reports.
 Ad
The immediate market reaction was a surge in energy prices, with Brent crude climbing back toward $78 a barrel. The spike was attributed to severe disruptions to maritime transit through the critical Strait of Hormuz, a key chokepoint for global oil supply.
Inflation Outlook in Question
The sudden escalation has abruptly challenged the prevailing market narrative that moderating inflation would allow major central banks to maintain a neutral policy stance. Prior to this week's clashes, bond markets had been rallying on expectations of cooling price pressures.
With the surge in oil rewriting near-term inflation projections, investors are now forced to re-evaluate the potential for central banks to remain hawkish. This shift has unwound bets on a more dovish policy outlook, repricing rate expectations higher across the yield curve.