
Story
Estee Lauder Stock Faces Key Test After 7% Weekly Drop
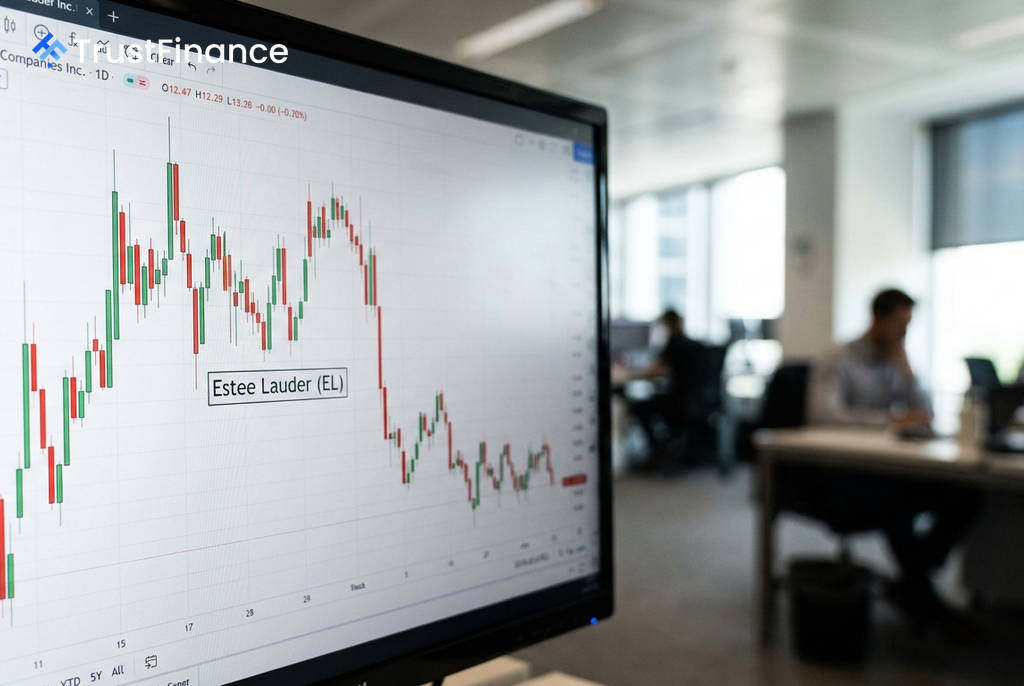
Shares of Estee Lauder (NYSE: EL) are facing renewed scrutiny from investors after a significant pullback, with the stock closing at $96.47 on September 10, a decline of 7.12% over the past week. The drop places the cosmetics giant at a critical juncture, testing the market's conviction in its ongoing business turnaround against persistent valuation concerns.
A Mixed Technical Picture
The recent price action has created conflicting technical signals across different timeframes. While the weekly chart remains in a "Strong Buy" state, with support identified near the $96.83 level, the daily chart has flipped to a "Sell" signal, according to Investing.com data. The longer-term monthly chart is considered neutral, suggesting the company's recovery is still incomplete.
For market participants, the key technical test is whether the stock can hold support in the $95.78–$96.83 range. A rebound that reclaims the daily pivot point of $99.09 would be seen as a positive sign for short-term momentum, while a break below this support zone could weaken the constructive weekly setup.
Turnaround Progress vs. Valuation Headwinds
Evidence of an operational turnaround has fueled the bull case for Estee Lauder. The company's last earnings release beat consensus EPS estimates by nearly 22%, triggering a 14.10% rally in its shares. Over the past year, consensus EPS revisions have improved by over 35%, and the company reported revenue growth of 5.0% as of June 30, 2026.
Despite these improvements, the stock's valuation remains a significant hurdle. Key metrics for bears include:
 Ad
- A forward price-to-earnings (P/E) ratio of 29.2x.
- A thin net margin of just 1.2%.
- A high debt-to-equity ratio of 242.9%.
These figures leave little room for error, while external risks such as potential tariffs, exposure to the Middle East, and an uneven global economic recovery persist.
Analyst Outlook
Analysts at Deutsche Bank noted the potential for further gains but emphasized that they are conditional. "Under the right conditions, we see a credible ‘bull case’ path to the stock exceeding $120 by year-end CY26/early-CY27 on a trajectory closer to $130+ over the next 12 months," the bank stated in a recent note. However, Investing.com's own fair value estimate suggests a potential downside of 1.0% from current levels, highlighting the valuation debate.
The next major catalyst for the stock will be its upcoming earnings report, scheduled for pre-market release on November 2, 2026. Analysts expect the company to post an EPS of $0.50 on revenue of $3.64 billion.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.