
Story
Dick's Sporting Goods Upgraded by Wells Fargo on Long-Term Growth Outlook
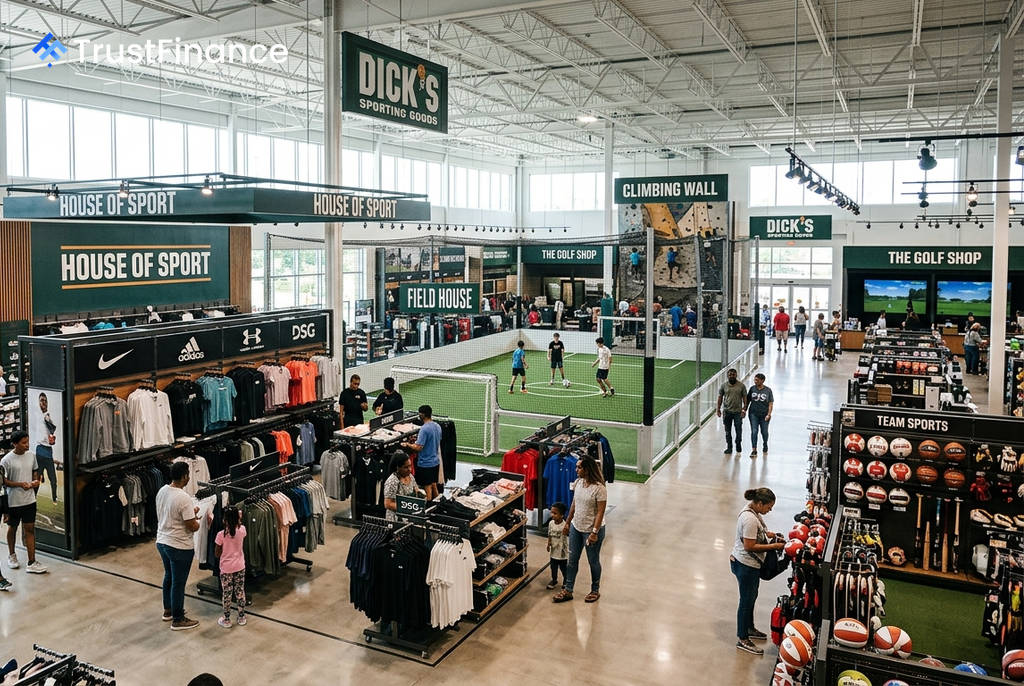
Wells Fargo upgraded its rating on Dick's Sporting Goods (NYSE: DKS) to Overweight from Equal Weight on Monday, citing a long-term growth narrative that it believes overshadows softer near-term business trends. The firm also raised its price target on the retailer's stock to $240 from $220.
Analyst's Thesis
In a note to investors, Wells Fargo analyst Ike Boruchow acknowledged that near-term trends look "squishy at best," but stated that the firm is a "buyer of the risk/reward" at current levels. The upgrade is centered on a multi-year recovery story, primarily driven by the potential turnaround of the recently acquired Foot Locker business.
The bank sees significant multi-year margin upside at Foot Locker, with a potential return to 7% to 8% operating margins from a current level of 1% to 2%. This improvement is expected to come from better product allocation and merchandising. The note also highlighted the strength of the core Dick's business, which it called the "New Star of US Sport," citing its category leadership and strong returns from its 'House of Sport' and 'Field House' store remodels.
Key Growth Drivers
Wells Fargo identified several factors contributing to its positive long-term view:
 Ad
- Core Business Execution: The analyst described the core Dick's operation as being in the "early-innings of building a compelling fly-wheel."
- Nike Partnership: The firm views Dick's as "the best way to play Nike's eventual product turnaround."
- Under-appreciated Assets: The note pointed to GameChanger, a paid loyalty program, and the DICK's Media Network as an "under-appreciated flywheel" for growth.
Near-Term Headwinds
Despite the upgrade, Wells Fargo anticipates a weak second-quarter earnings report, largely due to challenges at Foot Locker. The firm models Q2 earnings per share of $3.72, which is below the current Wall Street consensus.
However, the analyst believes investors will look past the immediate results. The note stated that the go-forward outlook for the back-to-school season and profit levers in the second half of the year will be "more critical to story than the actual 2Q results." Wells Fargo's new price target is based on a valuation of 14 to 15 times its 2027 earnings estimate, and the firm sees the company's fiscal 2028 earnings power reaching above $20 per share.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.