
Story
Dick's Sporting Goods Stock Plummets as Foot Locker Acquisition Drags Down Q2 Earnings
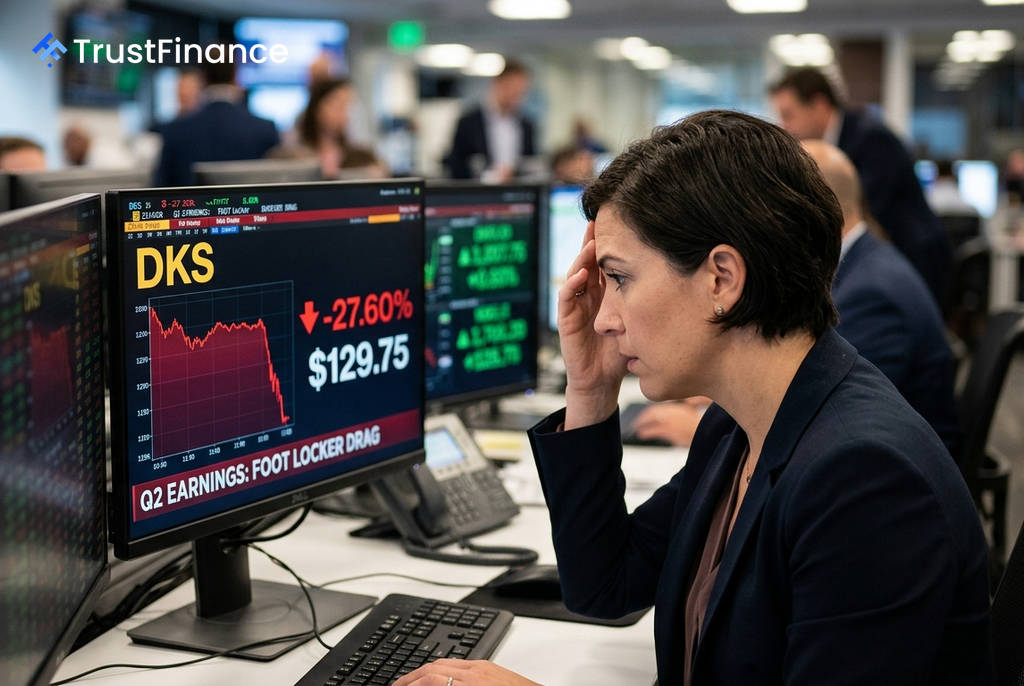
Dick's Sporting Goods (NYSE: DKS) shares plunged 27.6% in intraday trading after the retailer reported disappointing second-quarter results and cut its full-year outlook, erasing approximately $4.4 billion in market value. The company's performance was severely hampered by the struggles of its recently acquired Foot Locker division, which overshadowed strong results from its core business.
A Tale of Two Businesses
The earnings report revealed a stark contrast between the company's two main segments. The core DICK'S banner continued to perform well, while the Foot Locker business, acquired in September 2025, significantly underperformed expectations.
- DICK'S Core Banner: Posted a strong 4.9% in comparable sales growth, with a healthy operating margin of 12.6% and the addition of 1.5 million new customers.
- Foot Locker Division: Reported a pro forma comparable sales decline of -3.6%, a sharp reversal from prior expectations of growth. The division recorded an operating loss of $31.9 million, whereas a profit was expected.
Management attributed Foot Locker's weakness to a "more promotional athletic footwear market," excess inventory, and weaker demand in Europe. The drag from the acquisition was the primary driver behind the company's consolidated gross margin falling 300 basis points to 34.06%.
Slashed Guidance and Market Reaction
 Ad
The severe underperformance at Foot Locker forced management to drastically lower its full-year forecast for the division. The company now expects an operating loss between $40 million and $80 million for Foot Locker, a significant downturn from its previous guidance for a profit of $110 million to $150 million.
Investors reacted harshly to the news, signaling deep concerns about the integration risks and the financial burden of the $2.4 billion acquisition. The company's debt-to-equity ratio has surged to 139% following the deal, and the guidance cut has raised questions about management's credibility among analysts.
Catalysts and Risks Ahead
Looking forward, the market will be closely watching the upcoming back-to-school season as a critical test for Foot Locker's turnaround strategy. While an initiative called "Fast Break" has shown promise in early tests with double-digit comp sales, its execution at scale remains unproven.
Other potential growth drivers include the expansion of Dick's premium "House of Sport" store formats and the summer 2026 launch of an AI-powered digital shopping assistant. However, the primary focus for investors remains whether the operational strength of the core Dick's business can overcome the significant challenges presented by the Foot Locker integration.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.