
Story
AI Boom Reshapes Memory Chip Sector, Driving Demand for HBM, DRAM, and NAND
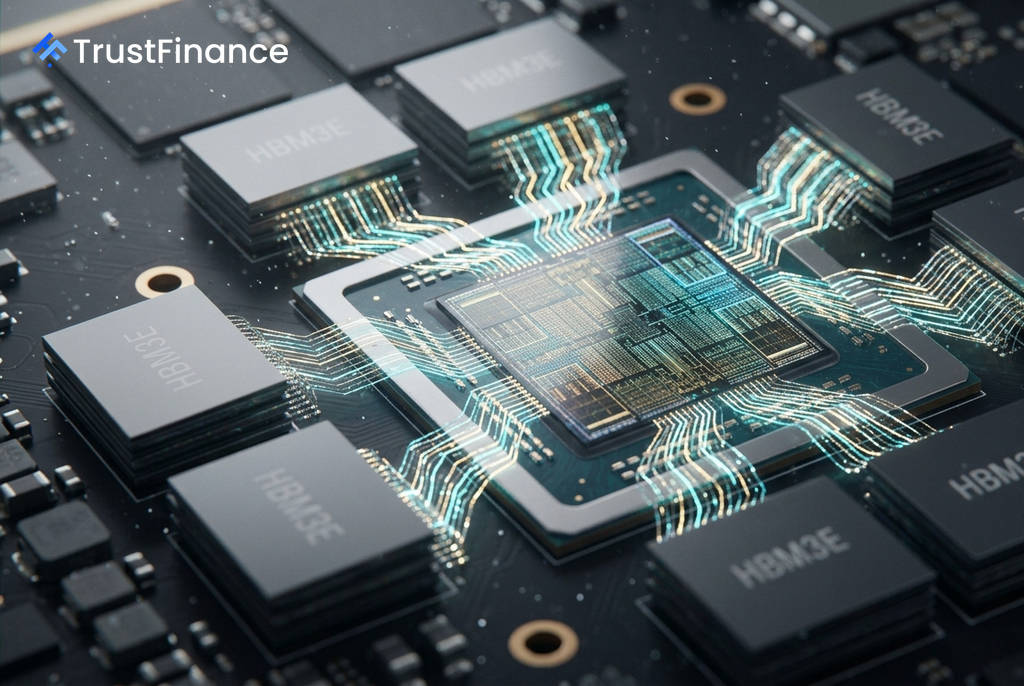
The explosive growth of artificial intelligence is placing unprecedented demands on the global semiconductor industry, with memory chips emerging as a critical performance bottleneck and a key area of investment. This surge in demand is fueling a structural shift away from the sector's historical cyclicality, driven by the need for faster, denser memory to power complex AI models.
The 'Memory Wall' in AI
AI processors are often limited not by their raw computational power but by the speed at which they can access data—a challenge known as the "memory wall." According to an analysis by Investing.com, training and running large language models require moving massive datasets, making memory bandwidth a decisive factor in the performance of AI infrastructure.
Without sufficiently fast memory, even the most powerful GPUs cannot operate at their full potential, creating a significant bottleneck that the industry is racing to solve.
HBM: The Premier AI Accelerator Fuel
High-Bandwidth Memory (HBM) has become the most strategically important component in this new landscape. HBM architecture involves stacking DRAM dies vertically, delivering data speeds reportedly 10 to 15 times faster than conventional DRAM, a crucial feature for high-end AI accelerators from companies like NVIDIA.
Key players in the HBM market include:
- SK Hynix: Identified as the current market leader and a primary supplier of the latest HBM3E generation to NVIDIA.
- Micron Technology: Reportedly ramping up its HBM production aggressively to capture market share.
- Samsung Electronics: Working to qualify its HBM products as it seeks to compete with its rivals.
 Ad
DRAM and NAND: The Essential Foundation
Beyond HBM, traditional memory types remain foundational to the AI ecosystem. The DRAM market, which provides the volatile memory for active data processing, is a tight oligopoly controlled by Samsung, SK Hynix, and Micron, who together hold approximately 95% of global supply.
The industry-wide transition to the DDR5 standard is a key upgrade cycle, as it doubles the bandwidth of its predecessor and is now standard in new AI server builds.
Meanwhile, NAND flash provides the non-volatile storage used in solid-state drives (SSDs) that hold the massive datasets and model checkpoints required for AI training. Major suppliers include Samsung, Micron, and Western Digital, which has strategically repositioned itself as a focused NAND and enterprise SSD provider.
Market Outlook and Key Risks
This AI-driven demand represents a potential paradigm shift for the memory market, with hyperscale companies investing billions annually in capital expenditures. According to the Investing.com analysis, memory can account for 30% to 40% of an AI server's total component cost, creating a strong structural tailwind for the sector.
However, significant risks remain. The memory industry has a long history of boom-and-bust cycles driven by supply and demand imbalances. Potential oversupply, particularly if HBM production ramps up faster than expected, and geopolitical tensions in key manufacturing regions present notable uncertainties for the sector's outlook.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.