
Story
Rocket Lab Forecasts Weaker Q3 Margins on Shift to Satellite Platform Sales
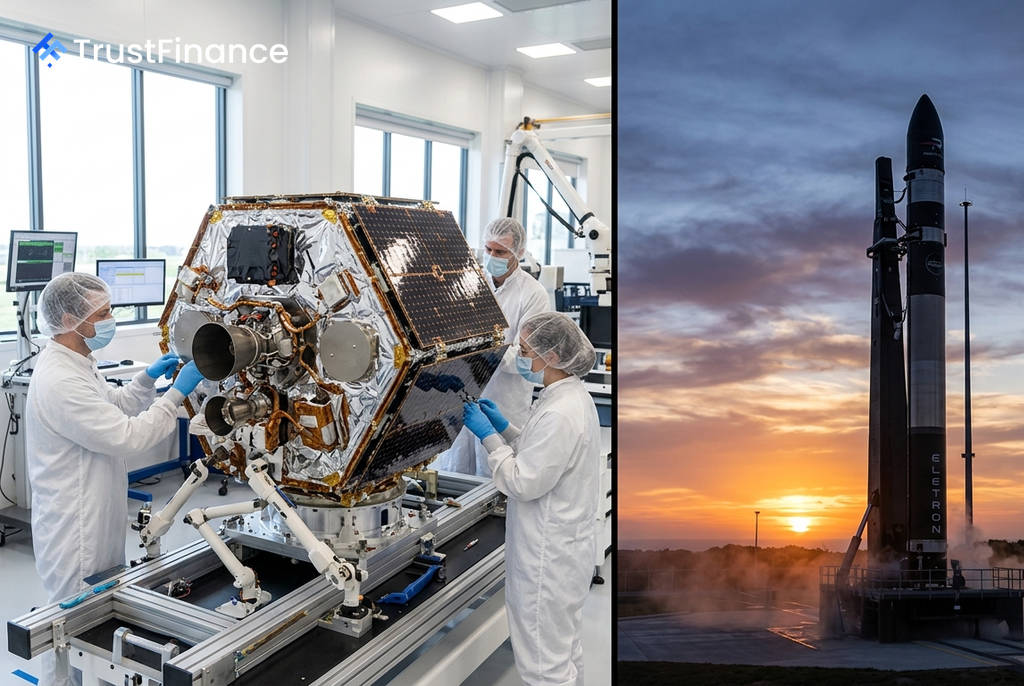
Rocket Lab (NASDAQ: RKLB) projected third-quarter gross margins below Wall Street expectations, signaling that a growing share of lower-profit satellite platform sales will weigh on profitability. The company's shares fell approximately 3% in extended trading following the announcement.
Margin Guidance and Market Reaction
Rocket Lab forecast a gross margin of 29% to 31% for the upcoming third quarter. This outlook falls significantly short of the analysts' average estimate of 37.6%, according to data compiled by LSEG.
The company attributed the weaker margin guidance to its product mix. Revenue from building larger, more complex satellite platforms is increasing, but these projects generate lower margins compared to its launch services and other space hardware products. This shift reflects the company's strategic expansion beyond its core Electron rocket into a broader satellite manufacturing operation.
Strong Revenue and Record Backlog
Despite the margin pressure, Rocket Lab issued a strong revenue forecast for the third quarter, expecting sales between $250 million and $265 million. This range is well above the Wall Street consensus estimate of $238.5 million.
 Ad
The optimistic revenue outlook is supported by strong performance in its largest division, Space Systems, which manufactures satellite components and other mission hardware. This unit was the primary driver of a 62% year-over-year jump in second-quarter revenue to a record $234 million, which also topped estimates. The company's confidence is further bolstered by a record backlog of $2.36 billion at the end of June.
Context: Investments in Growth
Rocket Lab continues to invest heavily in future growth, particularly in the development of its reusable medium-lift Neutron rocket. The Neutron is designed to compete for larger commercial satellite constellation missions and U.S. national security launches, with its first flight targeted for the fourth quarter of 2026.
These development costs, along with expenses related to integrating recent acquisitions like laser-communications firm Mynaric, are ongoing. The company's results illustrate the trade-off between investing in long-term, large-scale projects and maintaining near-term profitability margins.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.