
Story
HPE Shares Fall Sharply on Supply Chain and Margin Concerns Despite Q3 Beat
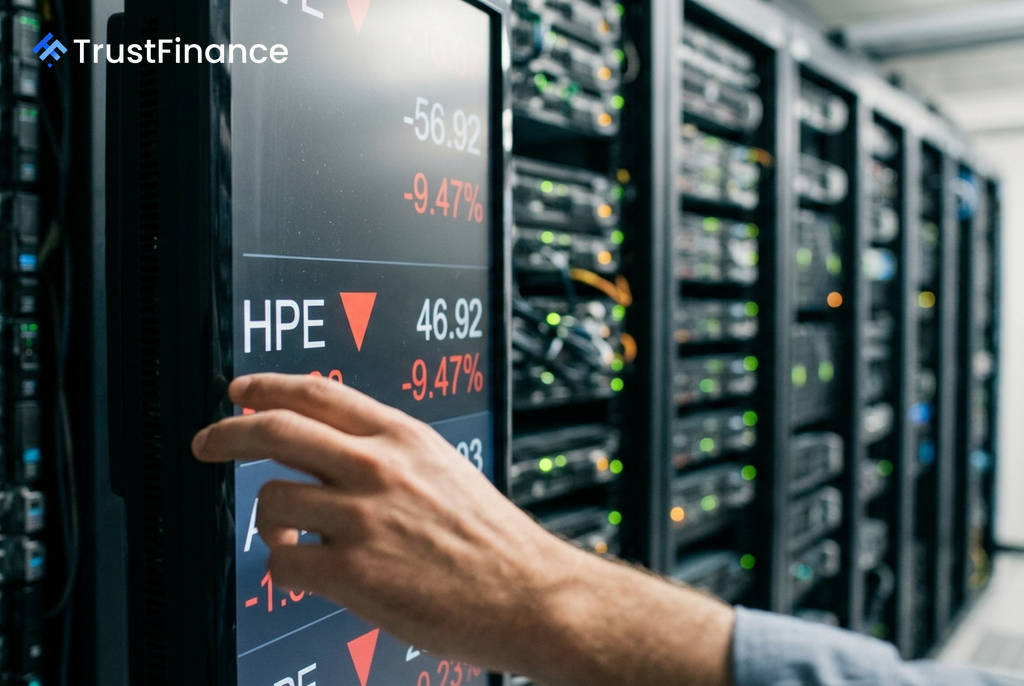
Shares of Hewlett Packard Enterprise Co. (HPE) fell sharply on Thursday, even after the company reported third-quarter earnings and revenue that surpassed analyst expectations. Investor focus shifted to warnings from management about persistent supply chain shortages and moderating profit margins, raising concerns about the company's ability to capitalize on strong demand.
As of 9:30 AM EDT on September 3, 2026, HPE shares were trading at $46.92, a decline of 9.47%.
Strong Demand Meets Production Headwinds
Hewlett Packard Enterprise posted robust results for its third quarter, fueled by a surge in demand, particularly for its AI systems. The company also raised its financial outlook, signaling confidence in its long-term growth trajectory.
Key highlights from the report include:
- Adjusted EPS: $1.11, beating the consensus estimate of $0.92.
- Revenue: $12.20 billion, compared to expectations of $11.93 billion.
- Orders: Grew 42% year-over-year, contributing to a record backlog of $7.6 billion.
- FY2026 Guidance: Full-year EPS guidance was raised to a range of $3.75 to $3.85.
 Ad
Despite these strong fundamentals, the company cautioned that shortages of key components—including DDR5 and DDR4 memory, NAND flash, and wafer capacity—are limiting its ability to ship products. Management also warned that gross margins could moderate in the fourth quarter as lower-margin AI systems constitute a larger portion of sales.
Market Focuses on Conversion Risk
The market's negative reaction highlights a classic conflict between strong demand and operational execution. The core concern for investors is that HPE's massive order backlog and $3.1 billion in AI-related orders may not translate into profitable revenue in a timely manner. The risk is that the company becomes a high-volume supplier of AI infrastructure with compressed profitability.
This sentiment was reflected in divided analyst opinions following the report. While Goldman Sachs remained positive, citing a stronger revenue growth outlook of 13%–17% for fiscal 2027 and a potential for over $5 billion in free cash flow, other firms expressed caution. Deutsche Bank raised its price target to $68, but Wells Fargo cut its target to $54, citing concerns over the pace of revenue conversion and underlying earnings before interest and taxes (EBIT).
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.