
Story
HPE, Dell Offer Contrasting AI Server Plays Amid Wide Valuation Gap
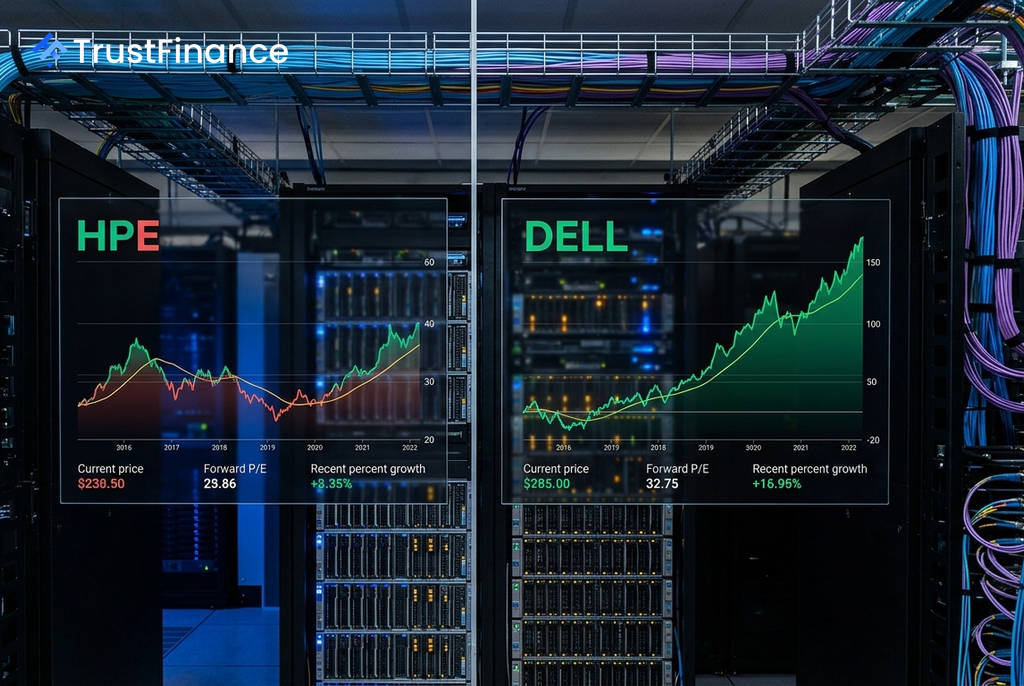
A significant valuation gap has emerged between AI server providers Hewlett Packard Enterprise and Dell Technologies, creating a distinct choice for investors between a potential value play and a high-growth momentum stock. According to analysis from Mizuho TMT specialist Jordan Klein cited by Investing.com, Dell is currently "priced for perfection," while HPE's lower multiples may offer a "margin of safety."
The Valuation Divide
Data compiled by Investing.com highlights the stark contrast in how the market is pricing the two hardware giants. The figures reveal a classic value-versus-growth scenario, with Dell commanding premium multiples for its robust expansion.
- Forward P/E Ratio: HPE trades at 14.6x forward earnings, a nearly 39% discount to Dell's 24.0x.
- Revenue Growth: Dell reported 38.6% revenue growth, significantly outpacing HPE's 22.6%.
- EPS Growth: Dell's earnings per share growth stands at an explosive 94.6%, compared to 3.7% for HPE.
- Fair Value: InvestingPro models cited in the report suggest both stocks are overvalued, but Dell more so, with a -15.7% fair value gap versus -9.0% for HPE.
HPE's Catalyst Weighed Down by Margin Concerns
The primary catalyst for HPE is its acquisition of Juniper Networks. On August 10, Morgan Stanley upgraded HPE to Overweight with a $69 price target, citing the deal's potential to create a "high-growth, high-margin profit engine." The bank pointed to accelerating free cash flow and shareholder returns as underappreciated factors, naming HPE its top pick among original equipment manufacturers (OEMs).
 Ad
However, HPE's profitability remains a central concern for investors. The company's net income margin is a razor-thin 0.2%, which pales in comparison to Dell's 5.2%. While HPE boasts a stronger gross margin at 30.3% versus Dell's 20.1%, its inability to carry that advantage to the bottom line suggests that integration costs and restructuring efforts are still weighing on performance.
Dell's Momentum Tempered by Risks
Dell's premium valuation is supported by its impressive financial performance, but it is not without risks. Analysts point to significant customer concentration, with an estimated 70% of its fiscal 2027 AI server revenue expected to come from just three clients: CoreWeave, xAI, and IREN.
Furthermore, the report notes $1.56 billion in insider sales over the last three months with no corresponding purchases. This activity coincides with a recent price target cut from Morgan Stanley, which maintained its Equal-Weight rating on Dell but lowered its target from $477 to $430 on August 7. For investors, the key question is whether Dell can sustain its growth trajectory to justify its high multiples, especially given these underlying risks.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.