
Story
Guidewire Stock Tumbles Despite Earnings Beat as Growth Outlook Weighs on Investors
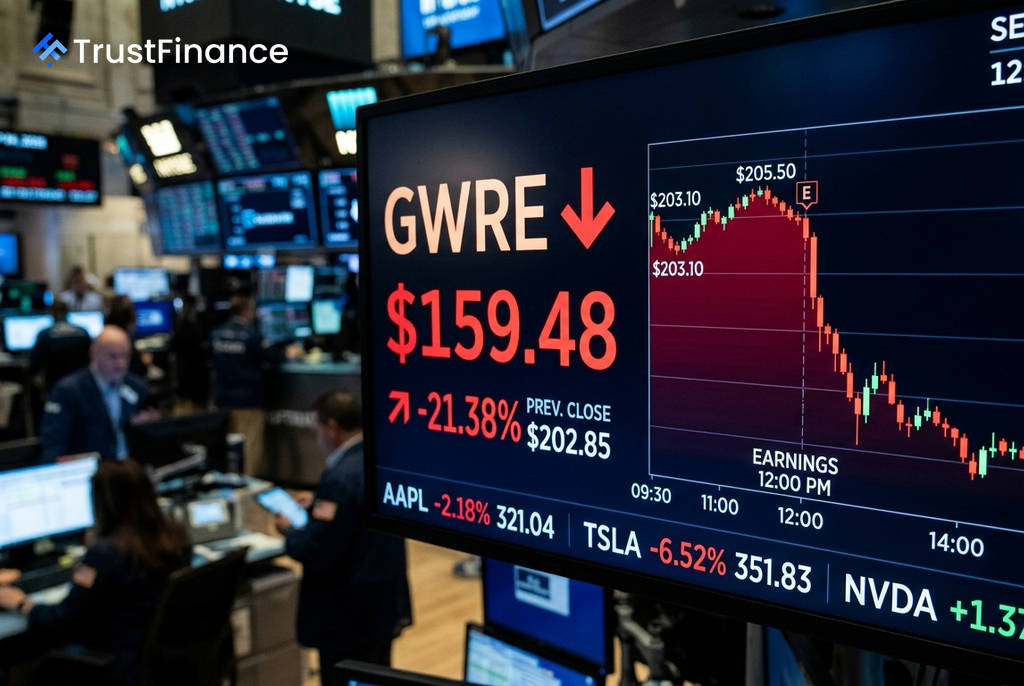
Guidewire Software (NYSE: GWRE) shares declined more than 21% in trading on September 4, 2026, even after the company posted fiscal fourth-quarter results that exceeded Wall Street estimates. The negative market reaction highlights investor concerns over the company's growth trajectory and the financial impact of its ongoing transition to a cloud-based subscription model.
Strong Quarter Met With Skepticism
Guidewire reported strong performance for its fourth quarter ending in fiscal year 2026. The company's results, detailed in its September 3 earnings report, surpassed analyst consensus:
- Earnings Per Share (EPS): $0.99, compared to an expected $0.93.
- Revenue: $411.08 million, versus expectations of $402.73 million.
- Annual Recurring Revenue (ARR): Grew to $1.242 billion for the full fiscal year, a 19% increase in constant currency.
Despite the beat, the market focused on the forward-looking narrative. As of 12:23 PM EDT on September 4, the stock was trading at $159.48, a drop of 21.38%.
Guidance Signals Slower Growth Ahead
 Ad
Management's guidance for fiscal year 2027 appeared to be the primary driver of the selloff. While Guidewire projects strong subscription revenue growth of approximately 31%, this is expected to be partially offset by a roughly $46 million decline in license revenue as more customers migrate to the cloud.
For fiscal 2027, the company guided for total ARR between $1.45 billion and $1.46 billion, which implies constant-currency growth of about 18%. This represents a slight deceleration from the 19% growth achieved in fiscal 2026, raising questions about growth durability at a time when the stock carries a high valuation.
The Investor Debate: Valuation vs. Transition
The core tension for investors is whether Guidewire's strong customer retention and cloud momentum can justify its premium valuation. According to the source, the stock traded at a trailing price-to-earnings ratio of 121.3x as of July 31, 2026, a level that demands near-perfect execution.
Looking ahead, investors will monitor several key catalysts to gauge the company's progress. These include potential product announcements at its Connections conference in October 2026, the adoption rate of new products like ProNavigator and PricingCenter, and the company's ability to expand gross margins and cash flow as the cloud transition matures.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.