
Story
DoValue Shares Plunge on Widening Loss and Surging Debt
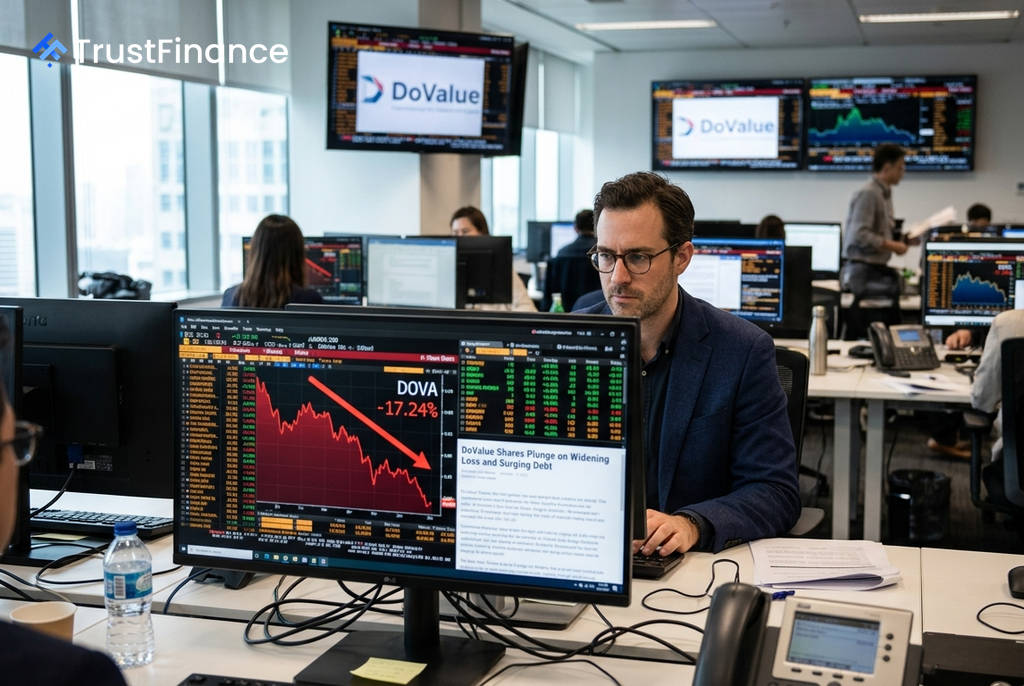
Shares of DoValue (Euronext Milan: DOVA) plunged 15.5% to €2.044 in morning trading, making it the worst-performing stock on the Euronext Milan exchange. The sell-off was triggered by the company's first-half 2026 financial results, which revealed a significant deterioration in profitability and a sharp increase in debt.
Earnings Weaken Significantly
DoValue reported a first-half net loss of €21.6 million, a steep increase from the €4.1 million loss recorded in the same period of 2025. The company attributed the wider loss primarily to non-recurring costs associated with the acquisition and integration of its coeo unit, including severance charges and transaction fees.
However, underlying performance also showed significant weakness. Even after excluding these one-time items, recurring net profit fell by approximately 82% to just €2.2 million, down from €11.9 million a year prior. First-half EBITDA also declined by 12%, according to the company's report.
Balance Sheet and Guidance Raise Concerns
 Ad
Investors are also focused on the company's deteriorating balance sheet. Net debt nearly doubled to €855 million from €439 million at the end of 2025, pushing financial leverage to 3.1 times EBITDA. The results also highlighted a new concentration risk, with the recently acquired coeo accounting for 31% of gross revenues in the second quarter.
While management confirmed its full-year 2026 EBITDA target of approximately €300 million, it noted that achieving this goal is conditional. The guidance depends on strong second-half performance from coeo and the successful execution of cost-reduction plans in what it described as a "less favorable" market for non-performing loan (NPL) servicing.
Market Reaction
The sharp decline in DoValue's stock was company-specific, as the broader Italian FTSE MIB index was only slightly lower. Following the results, analysts at Equita maintained a "Hold" rating with a €2.70 price target. The combination of a wider reported loss, collapsing recurring profitability, and surging leverage has introduced significant uncertainty for investors.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.