
Story
Dollar and Euro Hold Steady as Traders Await US Inflation Data, Monitor Mideast Tensions
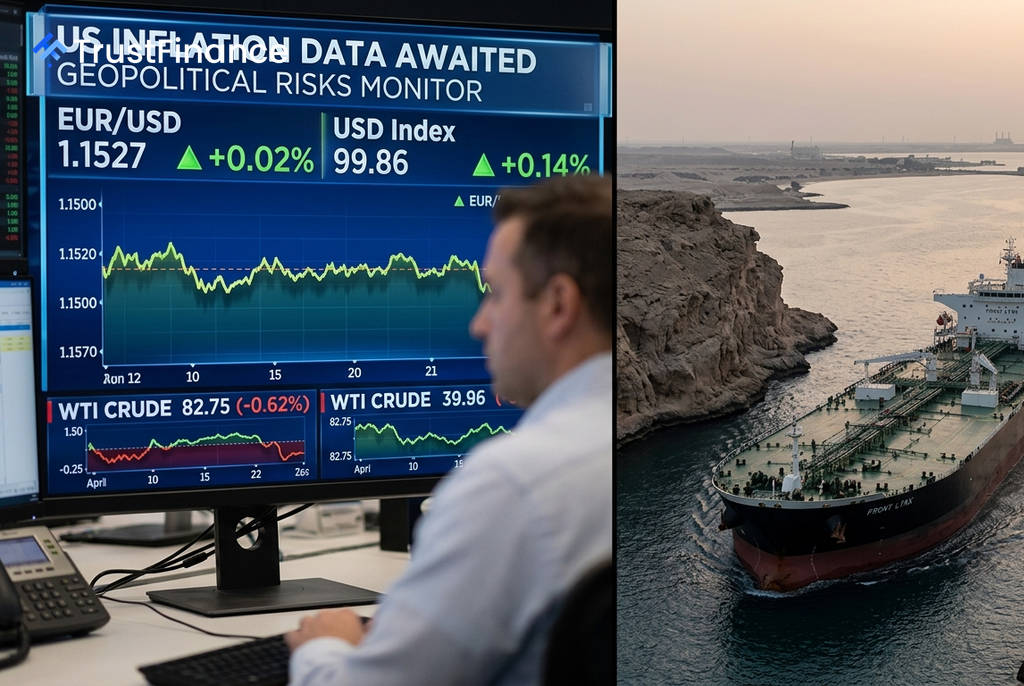
The U.S. dollar and euro traded in tight ranges on Tuesday as foreign exchange investors adopted a wait-and-see approach, balancing the effects of a surprisingly weak U.S. jobs report against rising crude oil prices and geopolitical friction.
All eyes are on Wednesday's U.S. Consumer Price Index (CPI) report, which will be a critical factor for the Federal Reserve's policy direction heading into the fall. The U.S. Dollar Index held firm around 99.84, while the euro was mostly flat against the dollar at approximately $1.1540.
US Data and Geopolitics Create a Tug-of-War
The currency market's quiet trading belies a complex macroeconomic environment. The dollar came under pressure after the U.S. Labor Department reported an unexpected decline in employment, with payrolls falling by 23,000 in July and previous months' figures being revised lower. This weak data led traders to unwind bets on a September rate hike from the Fed, pushing global sovereign bond yields down and pulling the dollar back from its summer highs.
However, a floor was placed under the dollar by a resurgence in energy costs, fueled by geopolitical tensions in the Persian Gulf. A diplomatic stalemate over passage through the Strait of Hormuz has pushed benchmark crude oil prices to multi-week highs. This standoff risks sustaining energy-driven inflation for major net-importing economies in Europe and Asia.
Global Central Banks Remain Cautious
 Ad
Other major central banks are also navigating persistent price pressures. The Reserve Bank of Australia (RBA) held its benchmark interest rate at 4.35%, a move that was widely anticipated by markets. The Australian dollar remained stable near $0.7055 as RBA Governor Michele Bullock maintained a balanced but cautious tone, noting that the central bank would not hesitate to hike rates further if upside inflation risks materialize.
In Europe, traders are awaiting a batch of regional economic data later this week, including second-quarter GDP figures and final July inflation numbers from Germany, France, and Spain. This data will be crucial in assessing whether the European Central Bank can afford to keep interest rates on hold at its September meeting.
Inflation Report Looms Large
The upcoming U.S. CPI report is the key event risk for the week. Market consensus expects core CPI to have risen 0.2% month-over-month.
A softer-than-expected reading would reinforce the view that the cooling labor market is translating into weaker price growth, giving the Fed a clear runway to extend its policy pause. Conversely, a stronger print could reignite rate hike expectations and introduce fresh volatility into currency markets.
Read next
More on Forex
Polish Zloty Hits 11-Month Low Against Euro on Energy Price Pressure
The Polish zloty weakened to 4.410 against the euro, its lowest point since November 2023, as rising energy prices and caution ahead of a U.S. Federal Reserve decision weighed on the currency.

Sterling Slips as Dollar Strengthens Ahead of Fed Decision and UK Budget
The British pound lost ground against a resurgent U.S. dollar on Wednesday as market attention shifted from tech sector volatility to upcoming central bank decisions and the UK budget announcement.
Eurozone Bond Yields Climb as French Fiscal Concerns Return Ahead of Fed, ECB Decisions
Yields on French and German government bonds rose as relief from a ratings affirmation for France proved temporary, with investors refocusing on fiscal challenges and awaiting key policy verdicts from the U.S. Federal Reserve and the European Central Bank.

Canadian Dollar Slips as Markets Await Bank of Canada, Fed Decisions
The Canadian dollar edged lower against its U.S. counterpart, snapping a seven-day winning streak as investors adopted a cautious stance ahead of Wednesday's key interest rate announcements from both the Bank of Canada and the U.S. Federal Reserve.