
Story
DocuSign Beats Q2 Estimates and Raises Guidance on IAM Platform Growth
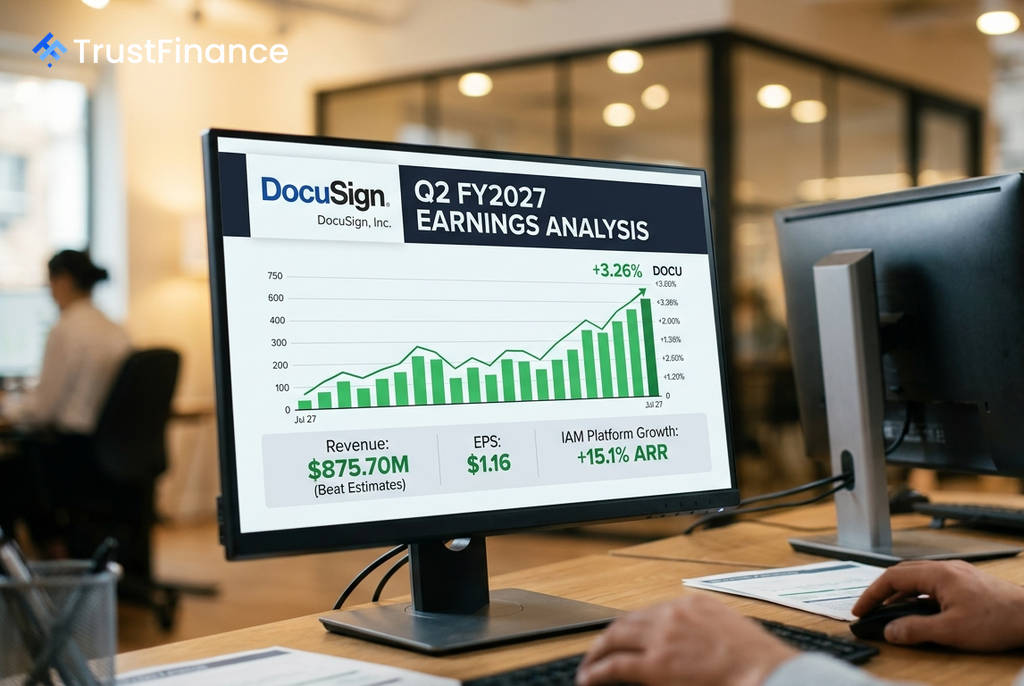
DocuSign Inc. (NASDAQ: DOCU) reported second-quarter financial results that exceeded Wall Street estimates and raised its full-year revenue guidance, citing strong adoption of its new Intelligent Agreement Management (IAM) platform. The positive results suggest the company's strategic shift beyond e-signatures is gaining traction with customers.
Earnings Beat and Raised Outlook
For the second quarter of fiscal year 2027, DocuSign announced strong performance across key metrics, indicating modest but steady business reacceleration. The company also provided an optimistic forecast for the full fiscal year.
- Revenue: $875.70 million, beating the consensus estimate of $867.20 million.
- Earnings Per Share (EPS): $1.16, compared to the $1.08 expected by analysts.
- FY2027 Guidance: Revenue forecast raised to a range of $3.499 billion to $3.507 billion.
- Revenue Growth: The company posted 9% year-over-year revenue growth.
DocuSign also generated $296 million in free cash flow, representing a robust 34% margin, and repurchased $307 million of its stock during the quarter.
IAM Adoption Shows Momentum
 Ad
A key focus for investors has been the adoption of DocuSign's broader IAM platform. The company reported that IAM's contribution to Annual Recurring Revenue (ARR) grew to 15.1%, up from 12.6% in the prior period. Management stated it expects this figure to reach 18% to 19% by the end of the fiscal year.
Other metrics pointed to strengthening enterprise adoption. The number of large customers with annual contract values over $300,000 grew by 14% year-over-year. Additionally, the dollar net retention rate, a key measure of customer expansion, improved to 103% from 102%.
Monetization Questions Remain
Despite the positive results, a key question for analysts and investors is the exact nature of IAM's contribution to growth. According to an assessment from Morgan Stanley cited in the source material, it remains unclear how much of IAM's adoption represents incremental spending versus customers migrating from legacy eSignature products.
Investors will be closely watching for evidence that the new platform can return the company to durable, double-digit revenue growth. Future earnings reports will need to demonstrate that IAM is not only changing the product mix but fundamentally accelerating the company's top-line growth rate.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.