
Story
Baird Identifies Top Apparel and Footwear Stocks, Citing Growth and Valuation
Summary
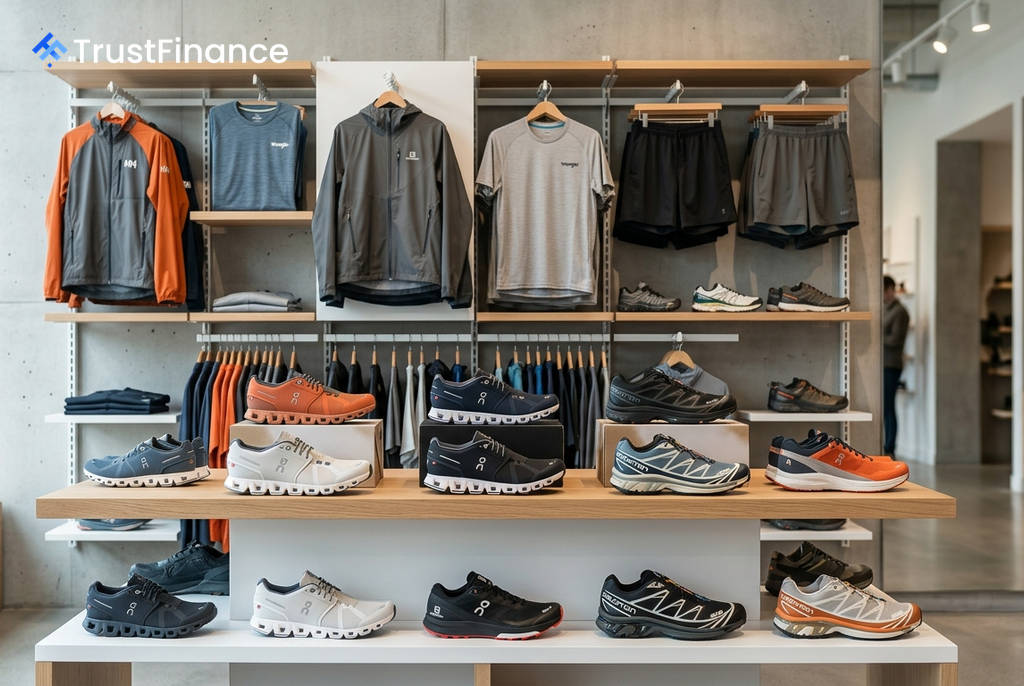
Investment firm Baird has highlighted several key opportunities in the apparel and footwear sector, maintaining Outperform ratings on companies like Amer Sports and On Holding due to strong brand momentum and attractive valuations.
Investment firm Baird has identified several compelling investment opportunities within the apparel and footwear sector, maintaining Outperform ratings on a slate of companies it believes are poised for growth despite recent market volatility. The firm's analysis highlights strong direct-to-consumer (DTC) momentum, brand strength, and attractive valuations as key drivers for potential upside.
Baird's Top Selections
In a recent note to clients, Baird detailed its rationale for favoring six specific companies in the space, pointing to a combination of secular growth trends and company-specific catalysts.
- Amer Sports (AS): Baird is positive on the company due to strong growth drivers across its main brands, supported by a premium DTC model. The firm sees the stock's valuation as compelling at approximately 10 times its next-twelve-months enterprise value to EBITDA (EV/EBITDA).
- On Holding (ONON): The firm views On as positioned for best-in-class growth, considering a recent slowdown in U.S. wholesale to be temporary. Baird noted the shares look "severely discounted" at less than 8 times its next-twelve-months EV/EBITDA.
- Kontoor Brands (KTB): Expected to benefit from accelerated growth following its Helly Hansen acquisition. Baird highlighted strong denim trends for the Wrangler brand and a planned $400 million accelerated share repurchase program.
- Wolverine World Wide (WWW): Baird expressed increased confidence in earnings upside, supported by solid fundamentals. Its Saucony and Merrell brands grew 9% and 10% respectively, excluding currency, in the second quarter.
- Boot Barn (BOOT): Described as having one of the better secular growth profiles in specialty retail, with the potential for 20% annual earnings per share growth over the long term, supported by Western and workwear trends.
- Crocs (CROX): The firm believes actions to improve marketplace health are translating to better performance. It cited the company's strong cash generation and share repurchases as providing an upward bias to earnings.
Recent Performance and Market Context
Baird's positive outlook is underpinned by recent financial results from these companies. Amer Sports, Kontoor, Wolverine, and Crocs all reported second-quarter 2026 earnings and revenue that surpassed analyst estimates, leading several to raise their full-year guidance.
 Ad
Similarly, Boot Barn exceeded expectations in its first-quarter fiscal 2027 report. The sentiment reflects a belief that these specific brands can navigate a challenging consumer environment. Baird's analysis acknowledges some headwinds, such as the wholesale pressure impacting On Holding, but frames them as transient issues that are already priced into the stocks.
Key Investment Themes
Across its selections, Baird emphasized several recurring investment themes. The successful shift to a direct-to-consumer sales model, which typically offers higher margins, was a critical factor for both Amer Sports and On Holding.
Authentic brand identity in resilient categories—such as performance running, outdoor gear, and workwear—was cited as a fundamental strength for Wolverine and Boot Barn. Finally, the potential for significant cash returns to shareholders through dividends and stock buybacks was noted as a key support for the investment theses for Kontoor Brands and Crocs.
Read next
More on Stocks
Large Bullish Options Trade Bets on BioMarin Stock Reaching $100 by April 2027
A significant options trade on BioMarin Pharmaceutical suggests a trader is betting on the stock to rise more than 37% by April 2027, a move supported by unusual volatility signals.
GlobalFoundries Stock Rallies on US-Japan Fab Report, Marvell AI Deal
Shares of the semiconductor manufacturer jumped after a report detailed negotiations for a multi-billion dollar U.S. factory backed by Japan, alongside a new manufacturing agreement with Marvell for AI components.

Lyft Stock Slips After Guggenheim Downgrade on Growth Concerns
Guggenheim downgraded Lyft to Neutral from Buy and cut its price target to $16, citing a reduced growth forecast and uncertainty from an upcoming CFO change.

SpaceX Considers Buying Data From Failed Startups for AI Development, Report Says
Elon Musk's SpaceX is reportedly holding internal discussions to acquire customer and operational data from struggling or defunct startups, a move aimed at sourcing affordable data to train its artificial intelligence models.