
Story
Baird Highlights Three Fintech Stocks Poised for Q2 Earnings Beat
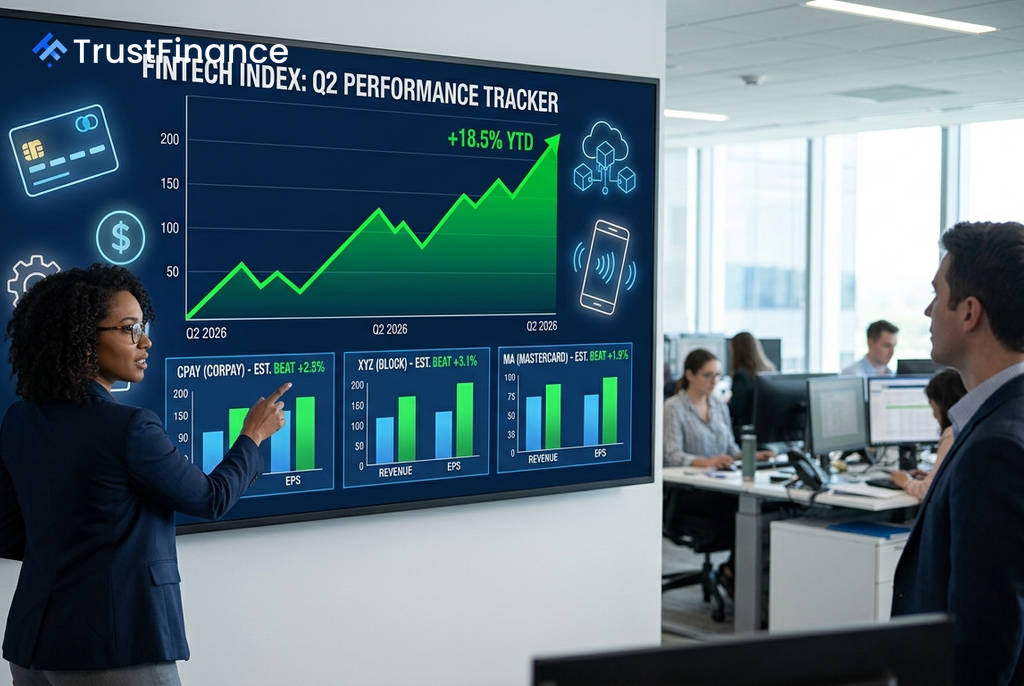
Baird Equity Research has identified three leading financial technology companies—Corpay (CPAY), XYZ, and Mastercard (MA)—as prime candidates for a "beat-and-raise" performance in the upcoming second-quarter 2026 earnings season. A July 14 research note from the firm highlights the companies' strong fundamentals and favorable positioning.
Favorable Fundamentals Drive Outlook
According to Baird analyst David J. Koning, the selected companies all demonstrate organic revenue growth exceeding 10% and earnings per share (EPS) growth of approximately 15% or more. The firm suggests their valuations appear reasonable given these growth profiles.
The positive outlook is supported by a strong backdrop for U.S. payments, with large banks reporting accelerating credit and debit volume growth. Baird also noted that sentiment toward the fintech sector appears to be improving as trading in artificial intelligence stocks has become more volatile.
Company-Specific Catalysts
Baird detailed its rationale for each of the top picks, anticipating that all three will exceed consensus estimates and lift their full-year forecasts.
 Ad
- Corpay (CPAY): The firm sees potential for 2026 EPS estimates to be biased upward by about 1%. Baird projects Q2 revenue growth to remain above 10% organically, with EPS growth surpassing 25%. The Corporate Payments unit, which accounts for roughly 40% of total revenue, is expected to grow around 15% in the second quarter.
- XYZ: A beat-and-raise is anticipated, with Baird seeing a potential upward bias of 2% to 4% for 2026 EPS estimates. The note forecasts that gross profit for its Square unit will accelerate to 11% growth, while its CashApp unit is likely to beat Street estimates with 33% year-over-year growth. Following recent updates, Baird raised its price target on the company to $100.
- Mastercard (MA): Baird expects a solid beat-and-raise performance, citing accelerating U.S. volumes reported by major banks. The firm believes current consensus estimates for cross-border revenue and operating margins are conservative. Baird recently increased its price target on Mastercard to $680.
Broader Macroeconomic Tailwinds
All three companies may also benefit from the current interest rate environment, according to the research note. Baird stated that XYZ and Mastercard both hold fixed-rate debt alongside floating-rate cash.
Meanwhile, Corpay’s Corporate Payments division stands to benefit from higher interest rates earned on its float portfolio. These macroeconomic factors, combined with strong company-specific execution, underpin Baird's positive thesis heading into the earnings reporting period.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.