
Story
UPM Downgraded by Barclays on Pulp Price Headwinds from New Capacity
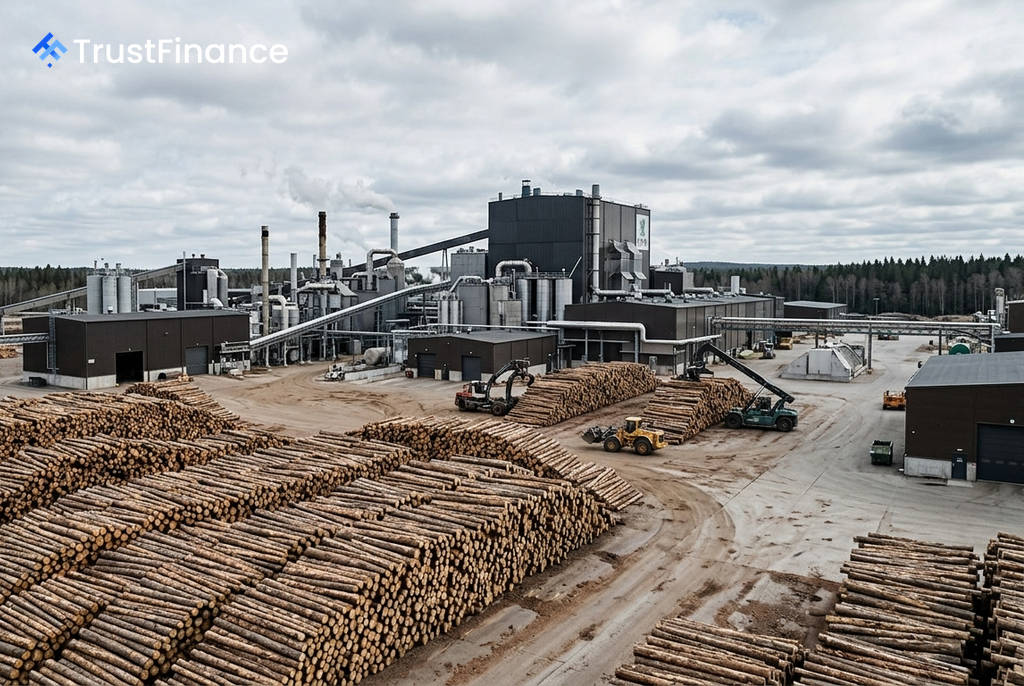
Barclays has downgraded Finnish forestry group UPM-Kymmene to “underweight” from “equal weight,” cutting its price target to €21 from a previous €24. The bank’s analysts cited concerns that a significant increase in global pulp production capacity over the next 18 months will lead to structurally lower prices, pressuring UPM's profitability.
Pulp Market Headwinds
The core of Barclays' thesis is a challenging outlook for the pulp market. The bank highlighted that new capacity expansions in China, Indonesia, and Brazil are set to outpace demand, which it sees growing at a slower rate of 0-2% annually, down from a historical 1-3%. This view is supported by softening demand, with global pulp demand down 2% year-on-year through May, particularly in China, which represents 30-35% of the global market.
This market dynamic poses a significant risk to UPM, as its Fibres division contributes over 40% of the group's earnings before interest and taxes (EBIT), excluding its plywood business. In response to this outlook, Barclays has cut its EBIT forecasts for the Fibres division by 20.5% for 2026 and 20% for 2027.
Valuation and Strategy Concerns
Barclays argued that UPM's current valuation, at an estimated 9x EV/EBITDA for 2027, is difficult to justify given the earnings risk. The bank believes that market optimism for the company's Energy, Biofuels, and Biochemicals businesses is already reflected in the share price.
 Ad
Furthermore, the note flagged UPM's management focus on inorganic growth over incremental shareholder returns. Barclays pointed to the Sappi graphic paper joint venture, which it described as dilutive from a free cash flow perspective, as an example of this strategic priority.
Revised Financial Forecasts
Reflecting its more cautious stance, Barclays lowered its total comparable EBIT estimate for UPM to €1.05 billion for 2026 and €1.25 billion for 2027. These projections sit 5% and 10% below Bloomberg consensus estimates, respectively.
In its sector-wide analysis, Barclays named Smurfit Westrock and SIG as its preferred stocks. Conversely, it rated Holmen, UPM, and Mondi as its least preferred, all with an “underweight” rating.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.