
Story
Snap to Report Q2 Earnings Amid High Volatility Expectations and User Growth Scrutiny
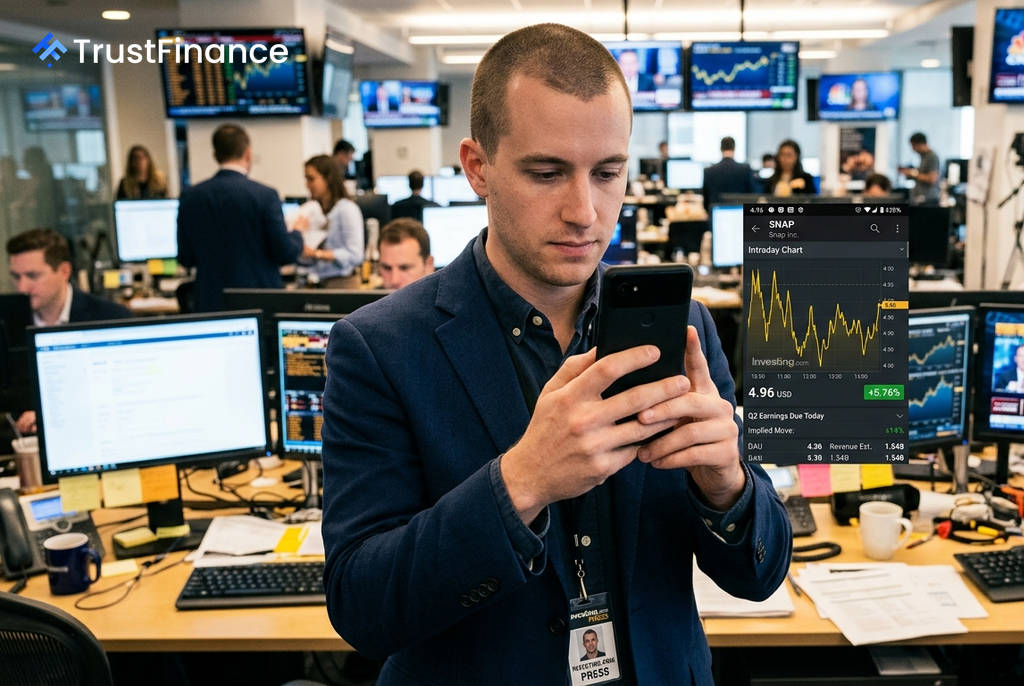
Snap Inc. is set to report its second-quarter financial results after market close, with investors closely watching for signs of sustained growth amid a history of significant post-earnings stock volatility. Wall Street anticipates year-over-year revenue growth but another quarterly loss, with options markets pricing in a potential share price swing of over 14%.
Wall Street Expectations
Analysts' consensus forecasts project a loss of $0.12 per share on revenue of $1.54 billion, according to data cited by Investing.com. This revenue target would represent a 15% increase compared to the same period last year and aligns with the higher end of the company's own guidance range of $1.52 billion to $1.55 billion.
Despite the expected top-line growth, the focus remains on the company's path to profitability and its forward-looking guidance. The stock has a history of sharp declines following its summer earnings reports, falling 31% and 18% in the two prior years, making forward guidance a critical factor for investors.
Conflicting Investor Narratives
The bull case for Snap centers on an improving financial trajectory and a track record of beating earnings per share (EPS) estimates in three of the last four quarters. Proponents point to the growth of its subscription service, Snap+, and new distribution deals as evidence of a diversifying business model beyond advertising, with a consensus forecast for a flip to full-year profitability in fiscal 2027.
 Ad
However, bears highlight several headwinds. The expected Q2 loss of -$0.12 per share is more than double the -$0.05 loss reported in Q1, representing a sequential widening. Analysts have recently trimmed price targets, citing pressure on Daily Active User (DAU) growth and regulatory scrutiny impacting its core younger demographic. Concerns also persist over significant capital expenditure on long-term hardware projects with no clear near-term financial return.
Key Metrics in Focus
Snap's stock performance will likely hinge on several key metrics beyond the headline revenue and EPS figures. Investors will scrutinize the company's guidance for the upcoming third quarter, particularly how its revenue forecast compares to the current consensus estimate of $1.70 billion.
Other critical data points that will likely determine the market's reaction include:
- Daily Active Users (DAU): Guidance on user growth is a paramount indicator of platform engagement and future monetization potential.
- Snap+ Subscribers: An update on the subscription service's traction will signal the success of its non-advertising revenue streams.
- Profit Margins: Commentary on margin expansion and the company's timeline for achieving sustained profitability will be closely analyzed.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.