
Story
Serco Upgraded to Outperform by BNP Paribas on Easing UK Political Risk
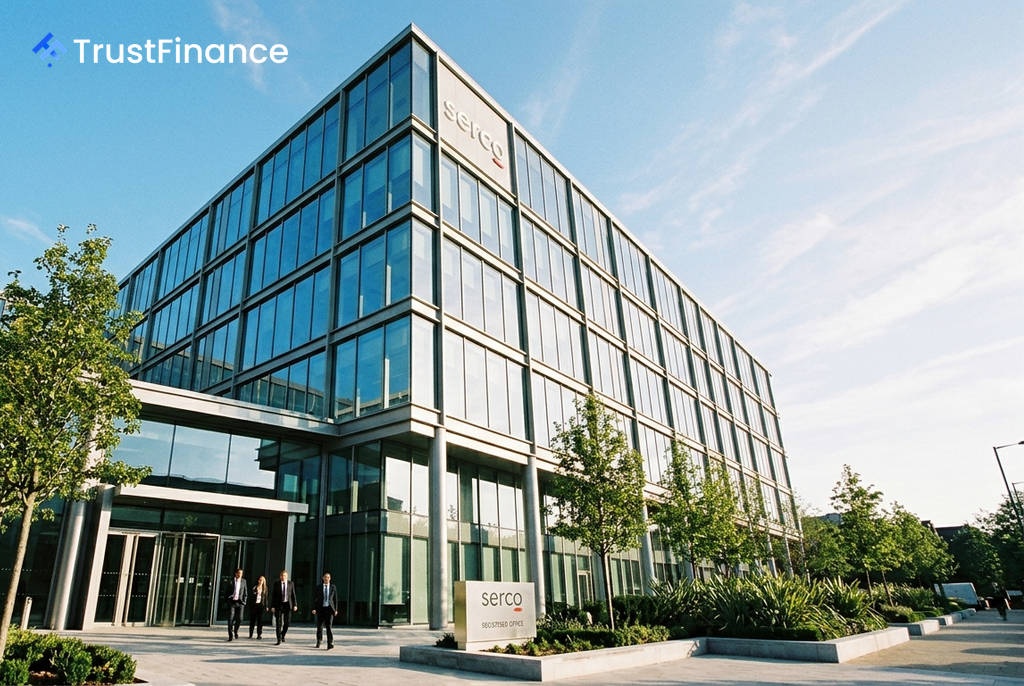
BNP Paribas has upgraded Serco Group to 'outperform' from 'neutral,' arguing that investor sentiment toward the British outsourcing firm is overly pessimistic given easing political risks in the UK and a strengthening outlook for its defence operations.
The bank raised its price target on Serco shares to 325 pence from 315 pence. In a note to clients, analysts said the stock’s valuation is attractive after a period of heightened uncertainty, noting that a UK political risk premium that rose sharply in May has since subsided and should continue to ease.
Rationale for the Upgrade
BNP Paribas outlined several factors for its more positive view on Serco’s UK business, which has been a key area of investor concern. The bank pointed to recent positive developments, including:
- The UK's July Defence Investment Plan, which is expected to relieve a procurement bottleneck.
- A more "nuanced debate" over asylum housing contracts.
- Recent Cabinet Office data indicating strong performance by Serco on its central government contracts.
Analysts also see limited scope for a significant shift away from government outsourcing, a core part of Serco's business model.
North American and Defence Outlook
 Ad
The bank's optimism extends to Serco's North American operations, where it expects recent market concerns over flat organic growth and a divisional CEO departure to be resolved by the company's December update. The note highlighted several overlooked positives, including 4% organic growth in the Defence unit in the first half of 2026.
Furthermore, Serco's pipeline of 24-month new bid opportunities has reached a record £8.1 billion, up significantly from £5 billion in 2025. This growth is supported by rising award activity among U.S. defence contractor peers and a potential increase in spending from the unspent 2025-26 U.S. defence budget, according to BNP Paribas.
Valuation and Forecasts
According to the note, Serco trades at a discount to its peers, with a price-to-earnings (P/E) ratio of 13 times compared to a sector average of 15 times, while offering a free cash flow yield of 7%. The new price target is based on a forward one-year P/E multiple of 16 times.
BNP Paribas forecasts Serco's adjusted earnings per share will grow from 19 pence in 2026 to 25 pence by 2029. Sales are projected to rise from £5.09 billion in 2026 to £5.76 billion over the same period.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.