
Story
Netflix Stock Hovers Near 52-Week Low as Wall Street Debates Decelerating Growth
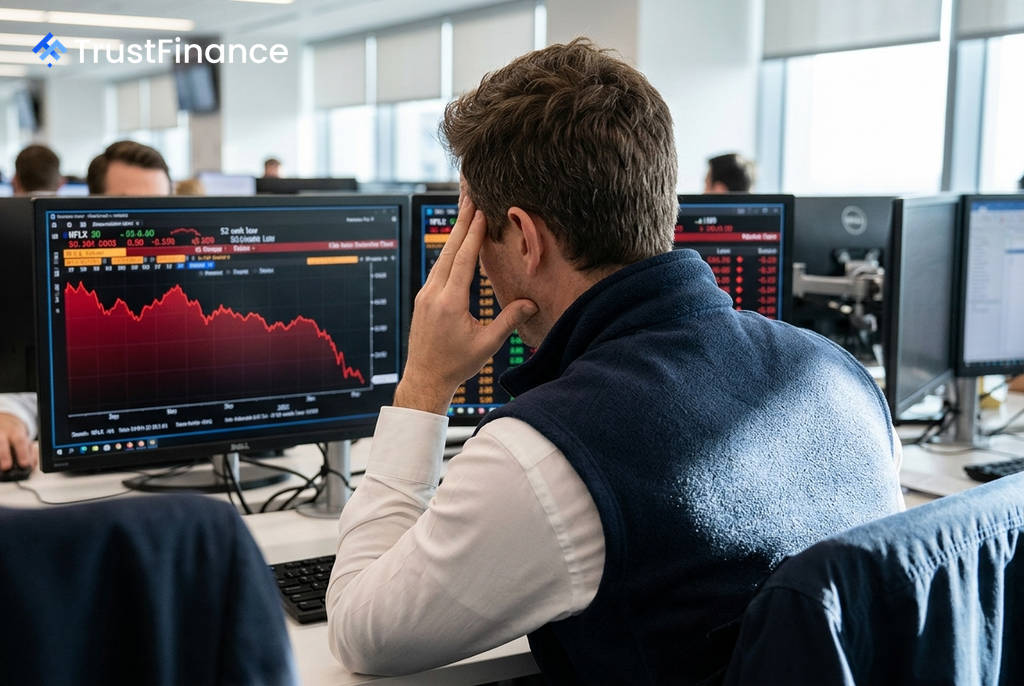
Netflix (NFLX) shares are trading near 52-week lows after a disappointing second-quarter earnings report and weak forward guidance intensified investor concerns about the streaming giant's slowing growth trajectory. The stock has fallen 43% over the past year and currently trades at $68.95, just above its 52-week low of $65.08, following a post-earnings decline on July 17.
Earnings Miss and Weak Guidance
While Netflix's Q2 2026 earnings per share (EPS) of $0.80 narrowly beat the $0.79 consensus estimate, other key metrics failed to meet Wall Street's expectations. The company's Q2 report on July 16 revealed a slight revenue miss and a cautious outlook that triggered the selloff.
- Q2 Revenue: Came in at $12.56 billion, just shy of the $12.58 billion consensus.
- Q3 Guidance: The company projected revenue of $12.86 billion and EPS of $0.82, falling short of analyst expectations for revenue closer to $13.0 billion.
- Transparency Concerns: Management also announced it would reduce the frequency of its engagement reporting to once per year, a move that unnerved investors concerned about viewer retention.
Analysts Recalibrate Expectations
In response to the report, several investment banks swiftly lowered their price targets on Netflix stock, though many still see potential upside from current levels. JPMorgan reduced its target to $85 from $118, while BofA Securities cut its target to $105 from $125. Oppenheimer and Rothschild Redburn also made significant downward revisions.
Despite the cuts, the median analyst price target of approximately $87 to $93 still implies a potential upside of 26% to 35% from the current share price. Analysts at Rothschild Redburn, who maintained a Buy rating, noted that the selloff seems more related to tax-rate revisions than a fundamental breakdown of the business model.
 Ad
The Bull and Bear Debate
Investors are now weighing competing narratives for the company's future. The core tension lies between new monetization strategies and signs of slowing momentum in its core business.
The Bull Case
Bulls point to several key factors as reasons for optimism. Netflix announced its largest-ever share repurchase program of $4.7 billion, signaling management's confidence in the stock's value. Furthermore, the company's ad-supported tier is a significant growth driver, on track to generate approximately $3 billion in 2026 revenue, with 55% of new subscribers reportedly choosing the ad plan.
The Bear Case
Bears argue that management's credibility on guidance is eroding after three consecutive quarters of negative post-earnings stock reactions. Concerns are also mounting over engagement fatigue, with Bloomberg data suggesting that hit shows can lose a significant portion of their audience after the first season. Critics also contend that even after the steep selloff, Netflix's valuation remains at a premium, trading at roughly 20 times its estimated 2027 earnings, leaving room for further downside if growth continues to decelerate.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.