
Story
Moody's Upgrades Adeia Outlook to Positive on Shifting Revenue Mix
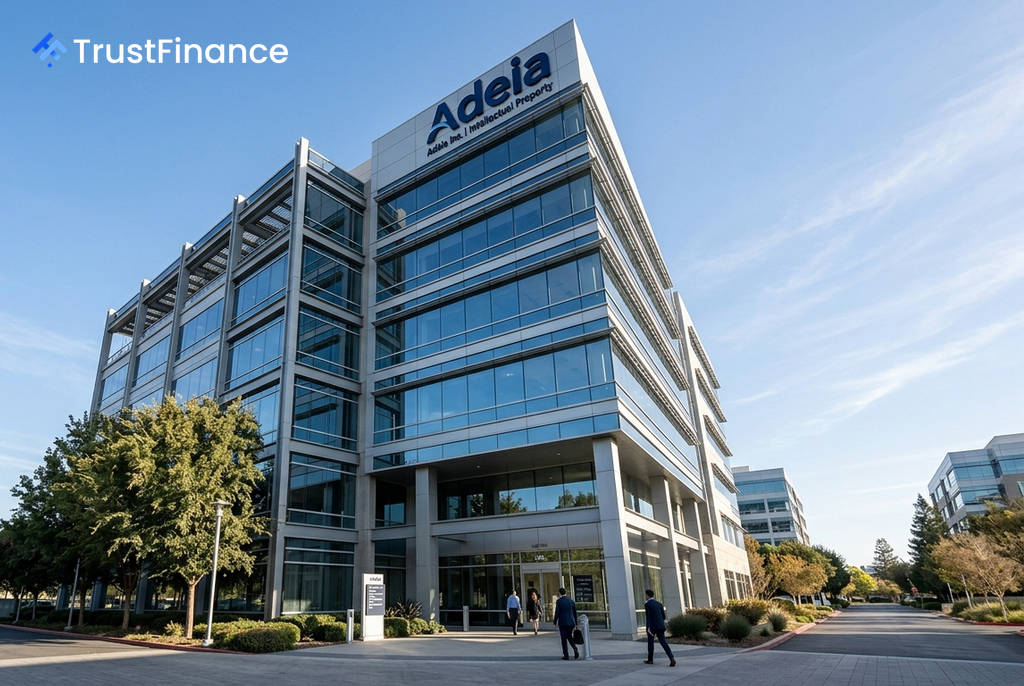
Moody's Ratings has affirmed Adeia Inc.'s Ba3 Corporate Family Rating and revised the company's outlook to positive from stable. The ratings agency cited an anticipated shift in Adeia's revenue composition, where growth in non-Pay TV and semiconductor licensing is expected to compensate for the decline in its traditional Pay TV business.
Rationale for the Outlook Change
The positive outlook is primarily driven by Moody's expectation that Adeia's exposure to traditional Pay TV licensing will fall to below 50% of total revenue over the next 12 to 18 months. This strategic pivot is seen as a key credit positive, diversifying the company's revenue streams away from a declining segment.
However, the Ba3 rating itself continues to reflect Adeia's relatively small revenue scale, significant customer concentration, and a narrow business focus on intellectual property licensing. The rating is supported by a strong IP portfolio of approximately 14,000 patent assets, which generated a recurring revenue base of $332 million for the twelve months ending March 31, 2026, according to the agency.
Financial Projections and Liquidity
Moody's projects a near-term decline in Adeia's top-line results, forecasting a low-teens percentage revenue drop in 2026. This is attributed to the absence of non-recurring revenue, such as upfront license fees and catch-up payments, that were recognized in 2025.
 Ad
Consequently, Moody's expects Adeia's adjusted EBITDA margin to decrease to the low 50% range, reflecting the lower non-recurring revenue and higher operating expenses from investments in R&D. Despite this, the company's credit metrics are expected to remain solid.
Key financial points from Moody's report include:
- Leverage: Adjusted debt-to-EBITDA is expected to remain at or below 2.0x.
- Liquidity: The Speculative Grade Liquidity Rating of SGL-1 was affirmed, reflecting a "very good" liquidity position.
- Cash Flow: Adeia is projected to generate at least $110 million in free cash flow over the next 12 to 18 months, supported by a cash and marketable securities balance of approximately $116 million as of March 2026.
Moody's also affirmed the Ba3-PD Probability of Default Rating and the Ba3 rating on Adeia's senior secured first lien term loan due in 2028.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.