
Story
Intel and Marvell Shares Fall, But Fundamentals Tell Different Stories
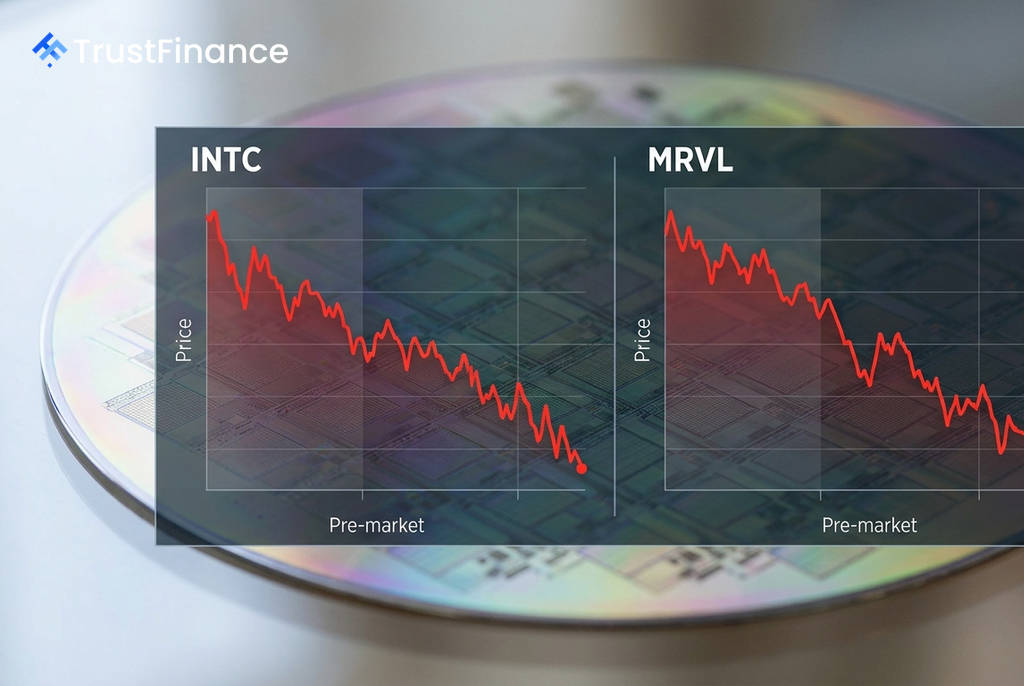
Shares of chipmakers Intel (INTC) and Marvell Technology (MRVL) both declined by approximately 5% in pre-market trading, but the drivers behind the sell-offs highlight diverging risk and reward profiles for the two semiconductor firms.
The Sell-Off in Context
The downward pressure on both stocks comes after a period of weakness in the broader sector. The Philadelphia Semiconductor Index fell roughly 8.5% in the week through July 15 amid investor concerns over high valuations and geopolitical tensions, according to Investing.com. Intel’s pre-market price stood at $87.11, while Marvell traded at $179.69.
Intel's Valuation and Turnaround Risks
Intel's stock decline follows a massive 343% run-up over the past year, setting a high bar for performance. While the company reported a strong third quarter on July 23, with ASIC revenue growing around 300% year-over-year, analysts have flagged significant headwinds.
Needham maintained a Hold rating on the stock, citing Intel's loss of market share in data center CPUs and a lack of competitiveness in AI accelerators. The firm also noted that the stock's valuation is "rich." According to InvestingPro's fair value model, Intel’s intrinsic value is estimated at $71.11, suggesting the stock was already overvalued by more than 22% at Monday's close, even before the pre-market drop.
Marvell's AI-Driven Growth
 Ad
In contrast, Marvell's sell-off comes as its business fundamentals appear to be strengthening. The company recently returned to profitability, reporting earnings per share of $3.07, a significant improvement from a loss of $1.02 two years prior.
Marvell's growth is largely driven by its custom silicon (ASIC) business for hyperscale data centers. Key metrics underscore its momentum:
- Annual revenue jumped from $5.77 billion to $8.19 billion in the latest fiscal year.
- Q2 revenue guidance is for approximately $2.7 billion, representing 35% year-over-year growth.
- Analyst consensus projects a 28.2% potential upside for the stock.
While a recent downgrade from Erste Group cited valuation concerns after a strong run, HSBC maintained a Buy rating in May with a $300 price target, citing the company's strong position in AI infrastructure, according to the source material.
Diverging Investment Outlooks
For investors, the two sell-offs represent different scenarios. Intel's drop appears to be a valuation correction for a company in the midst of a costly and high-risk foundry pivot, with negative return on equity and near-zero free cash flow yield. Marvell’s dip, however, looks more like a broader market pullback affecting a company with expanding margins, a clear growth trajectory in the AI sector, and a recent return to solid profitability.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.