
Story
Dell Crushes Earnings Estimates, Lifts Forecast on Soaring AI Server Demand
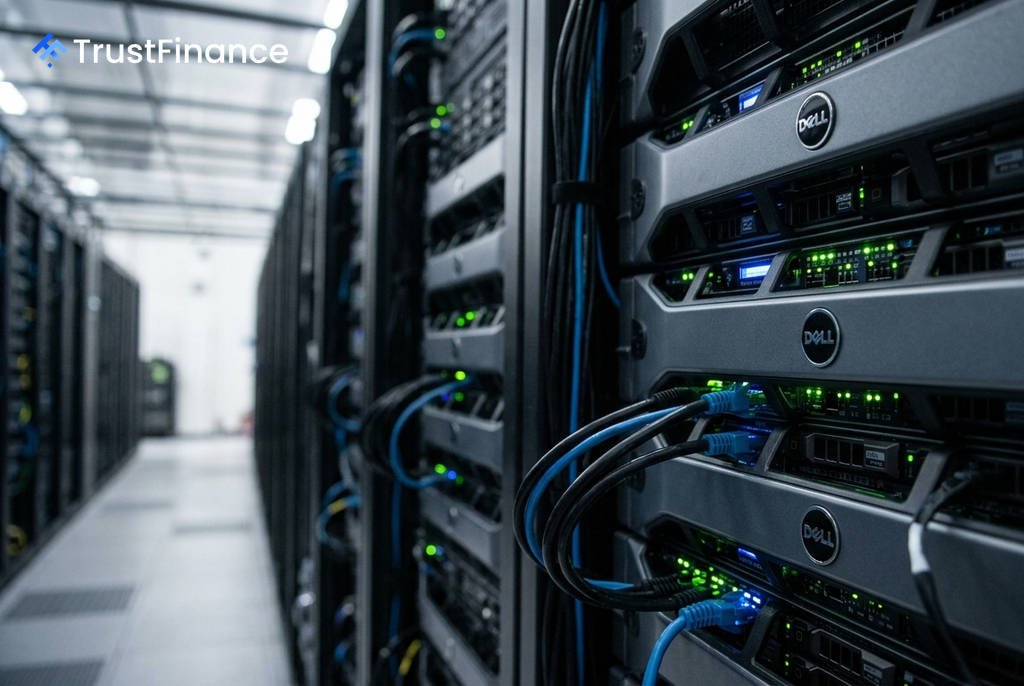
Dell Technologies Inc. (DELL) delivered quarterly results that significantly outpaced Wall Street estimates, driven by explosive growth in its artificial intelligence server business. The company also raised its full-year revenue guidance, signaling sustained momentum and confirming strong enterprise demand for AI infrastructure.
Results Exceed Expectations
For the quarter reported on September 1, 2026, Dell posted figures that decisively beat consensus forecasts. The strong performance was not limited to AI systems, as traditional server, networking, and storage segments also showed strength, suggesting that AI investments are driving broader data-center upgrades.
Key financial highlights include:
- Revenue: $47.0 billion, versus $44.84 billion expected.
- Earnings Per Share (EPS): $7.04, compared to the $4.87 analyst consensus.
- AI Server Revenue: $16.4 billion, an increase of approximately 100% year-over-year.
- AI Backlog: Grew to approximately $95 billion.
AI Demand Fuels Upgraded Forecast
 Ad
Based on the robust demand, Dell's management provided a significantly upgraded financial outlook. The company raised its fiscal year 2027 revenue guidance to approximately $192 billion, a substantial increase from its previous forecast of $167 billion. Guidance for AI server revenue was also lifted to roughly $74 billion from a prior $60 billion.
The massive $95 billion backlog in AI-related orders shifts the focus for investors. The primary question is no longer about the reality of AI demand but about Dell's ability to convert this backlog into profitable shipments while managing supply chain constraints for key components like memory and processors.
Market Reaction and Outlook
Following the report, Dell shares traded up 7.46% to $456.70 in afternoon trading on September 2. The rally adds to a remarkable run for the stock, which has gained over 277% in the past year, raising questions about its valuation.
Analysts are now weighing the sustainability of this growth. While acknowledging the strong quarter, UBS maintained a Neutral rating on the stock, though it raised its price target to $500. The key debate for investors centers on whether Dell can maintain its pricing power and gross margins if component costs continue to rise, or if customers might delay large-scale AI deployments, which could pressure future earnings.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.