
Story
BP Upgraded to 'Hold' by Freedom Broker on Surging Oil Prices and Q2 Earnings Beat
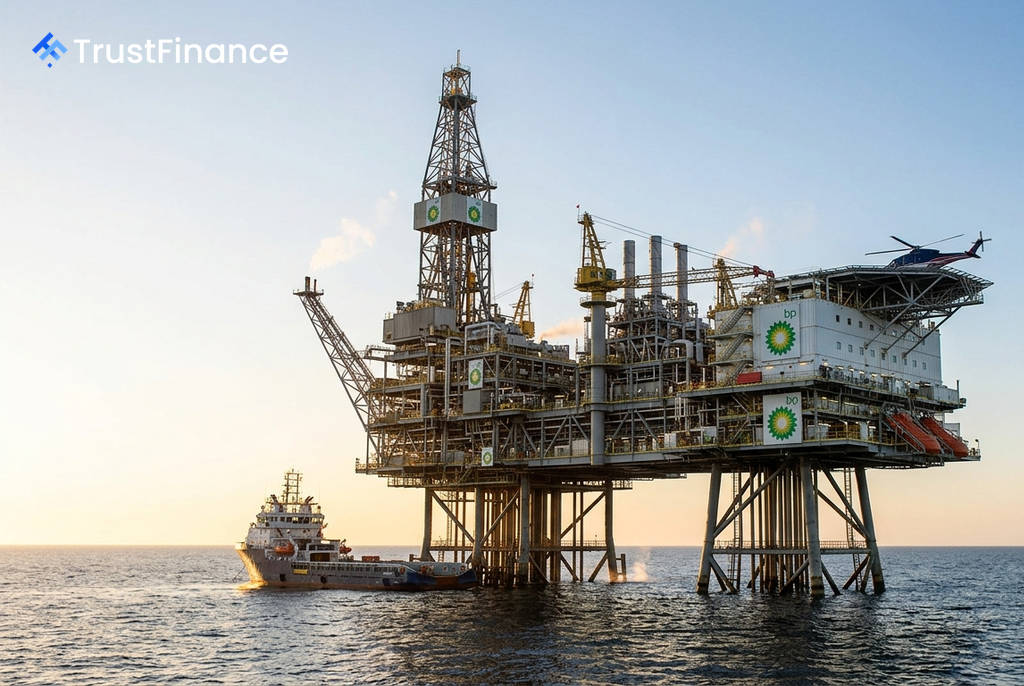
Freedom Broker has upgraded its rating on BP plc to “hold” from “sell” after the British energy major reported strong second-quarter 2026 earnings that surpassed analyst expectations, fueled by a sharp rise in hydrocarbon prices.
The brokerage also raised its price target for BP's American Depositary Receipts (ADRs) to $43 from a previous $39. The upgrade follows a quarter where BP’s adjusted earnings per share (EPS) of $2.22 per ADR beat consensus estimates by 13.8%, according to the research note.
Earnings Driven by Transitory Factors
BP’s financial performance was significantly boosted by favorable market conditions. The company's revenue climbed 48.2% year-over-year to $69.1 billion, while its adjusted net income reached $5.7 billion, a substantial increase from $2.4 billion in the same period a year earlier. Freedom Broker senior analyst Sergey Pigarev cautioned, however, that the outperformance was propelled by temporary events.
"BP’s Q2 outperformance was driven by transitory factors," Pigarev stated, attributing the results to elevated energy prices linked to geopolitical conflict in the Middle East and the loss of Russian refining capacity. Key performance drivers included:
- Refining Margins: Climbed 148.7% year-over-year to $29.6 per barrel.
- Realized Prices: Average prices in the Gas & Low Carbon Energy segment rose 29.3% year-over-year, while Oil Production prices increased 26.8%.
- Cash Flow: Operating cash flow before working capital changes rose 52.2% quarter-over-quarter to $13.5 billion.
Production Declines and Cautious Outlook
 Ad
Despite the strong financial results, BP's production volumes declined. Output in its Gas & Low Carbon Energy segment fell 2.1% year-over-year, while its Oil Production segment saw a 5.4% drop. The company's management guided for a further production decline of 1.2% in the third quarter, citing ongoing conflict and planned maintenance.
Refinery throughput is also expected to fall by approximately 9% following the divestment of a refinery. In a sign of capital discipline, BP's capital expenditures for 2026 are guided to be approximately $13.5 billion, down from $14.5 billion in 2025. The company also improved its balance sheet, with net debt falling by $2.9 billion during the quarter to $35.5 billion.
Shareholder Returns and Risks
BP's board approved a 4.1% increase in the quarterly dividend to $0.52 per ADR, representing an annualized yield of approximately 5.0%. However, the company did not execute any share repurchases during the quarter.
Looking ahead, Freedom Broker noted that potential asset disposals of $9 billion to $10 billion in 2026 represent a downside risk for investors. The broker warned that such sales would be "dilutive to revenue and earnings."
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.