
Story
BP Offers Cheaper Valuation While Shell Shows Stronger Financial Health, Analysis Shows
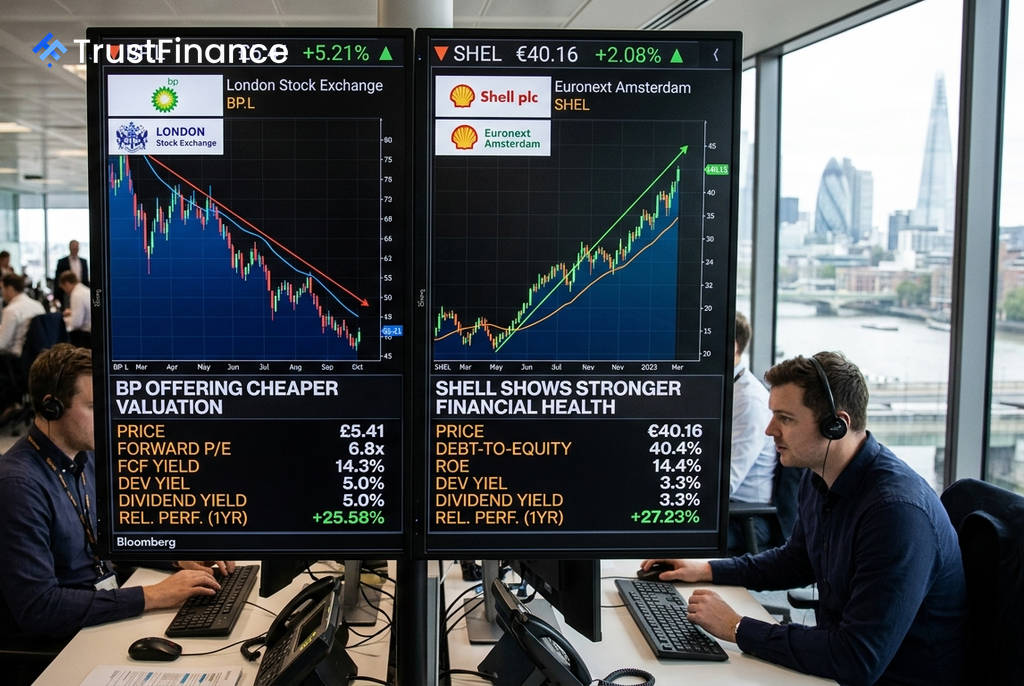
A comparative analysis of energy majors BP (BP) and Shell (SHEL) highlights a distinct trade-off for investors, with data showing BP offers a more attractive valuation while Shell demonstrates superior financial quality and stability.
Valuation Metrics Favor BP
On several key valuation measures, BP appears significantly cheaper than its rival. The company's stock trades at a lower forward price-to-earnings multiple and offers higher yields on both free cash flow and dividends, according to an analysis by Investing.com as of September 1, 2026.
- Forward P/E Ratio: BP at 6.8x vs. Shell at 8.0x
- Free Cash Flow Yield: BP at 14.3% vs. Shell at 12.4%
- Dividend Yield: BP at 5.0% vs. Shell at 3.3%
These figures suggest that from a pure value perspective, BP's shares are trading at a notable discount compared to Shell.
Shell Leads on Balance Sheet Quality
 Ad
In contrast, Shell's premium valuation is supported by its stronger financial position and profitability. The company operates with significantly less leverage and generates better returns for its shareholders.
Shell’s debt-to-equity ratio stood at 40.4% as of June 30, 2026, a fraction of BP’s 124.4%. Furthermore, Shell reported a Return on Equity (ROE) of 14.4%, outpacing BP's 9.2%. This suggests that BP's lower valuation partly reflects investor compensation for its higher financial risk and weaker profitability metrics.
Market Performance and Outlook
Recent stock performance has favored Shell, which outperformed BP by 1.65 percentage points over the past year and by 2.32 points year-to-date, according to the analysis. This trend indicates that the market has so far prioritized Shell's financial quality over BP's discounted price.
Technical indicators suggest Shell's rally may be more extended, while BP's momentum appears less stretched, potentially creating an opportunity for it to catch up. The core decision for investors hinges on whether the thesis is a mean reversion in valuation, which would favor BP, or a continued preference for Shell's financial resilience.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.