
Story
Analyst AI Focus: SpaceX Earns Street-High Target, Salesforce Downgraded on Product Concerns
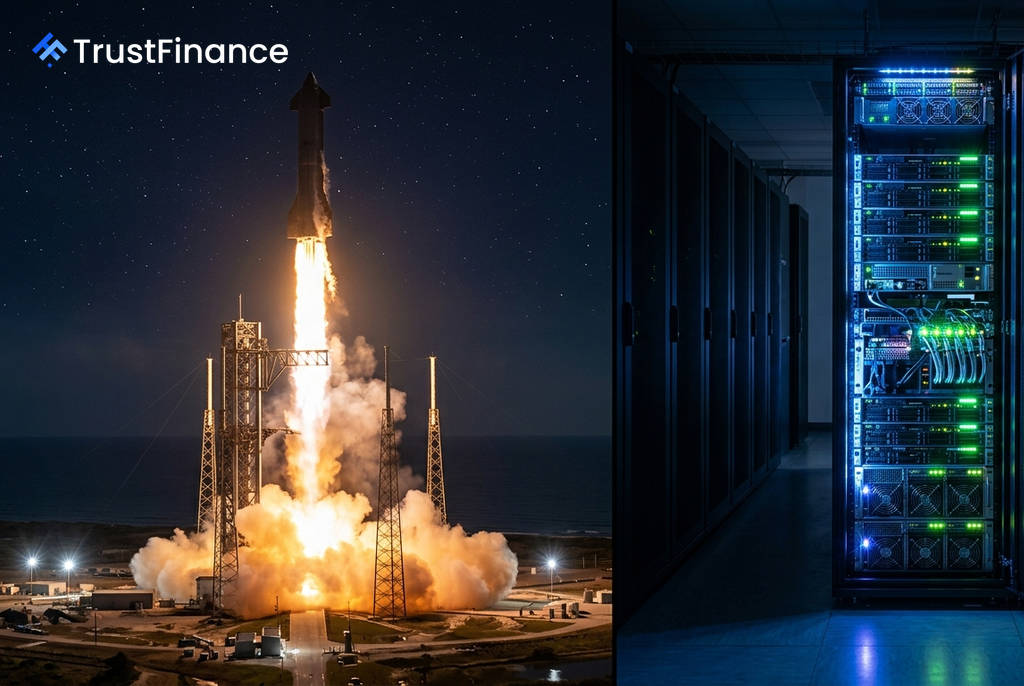
A series of major analyst reports this week highlighted diverging fortunes in the artificial intelligence sector, with a new Street-high price target for SpaceX contrasting with a downgrade for Salesforce over concerns about its AI product adoption.
SpaceX's 'Trillion-Dollar' Potential
Raymond James initiated coverage of SpaceX with a Strong Buy rating and an $800 price target, the highest on Wall Street. Analyst Brian Gesuale argued that the convergence of industrialized space access and AI represents "the most significant infrastructure convergence since the advent of the Internet."
The firm's thesis centers on Starship, which it estimates will reduce the cost of transporting mass to orbit by over 99%. This transformation, according to the note, turns orbital launch into a transportation network with a total addressable market approaching $30 trillion. Raymond James projects SpaceX's revenue could grow from approximately $38.5 billion today to more than $837 billion by 2031.
Divergent Views on Software and E-Commerce
In the software sector, Bernstein downgraded Salesforce to Sector Weight from Outperform, removing its price target. The move was prompted by weak customer feedback on the company's Agentforce AI product, with analyst Jackson Ader noting that conversations revealed customer data is often not organized for AI and that the product "just isn’t there."
 Ad
Conversely, Stifel upgraded Shopify to Buy from Hold and raised its price target to $150 from $110. The firm cited the stock's year-to-date decline as an attractive entry point, seeing a "realistic path to 30%-plus revenue growth in 2026." Stifel highlighted Shopify's strong execution, noting its first-quarter gross merchandise value (GMV) grew 35% year-over-year, far outpacing the broader e-commerce market.
Chip Sector and Asian Tech in Focus
Mizuho TMT specialist Jordan Klein described the recent sell-off in Samsung shares as an "overreaction" to its preliminary second-quarter results. Klein argued that the revenue miss was driven by mobile devices and TVs, not the critical memory business, where he estimates implied operating margins are over 80%. He advised that the company's full outlook at the end of July will be more telling for the semiconductor industry.
Meanwhile, Bank of America reiterated its Buy rating on Alibaba with a $172 price objective, calling it "one of the most compelling AI plays in China." The bank forecasts AI-driven demand will accelerate Alibaba's cloud revenue growth to 45% year-over-year in the June quarter, up from 38% in the prior quarter.