
Story
VSE Corp. Named Top Aerospace Pick by B Riley on Record Earnings, Upgraded Outlook
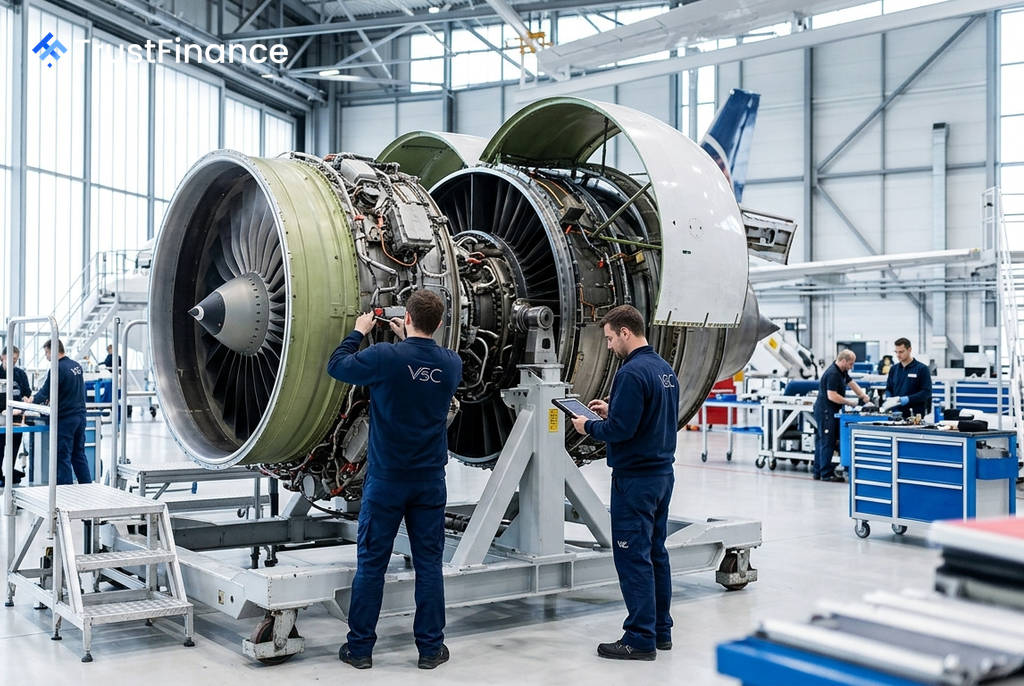
B Riley Securities has identified VSE Corporation (NASDAQ: VSEC) as a top investment idea in the Aerospace & Defense sector, citing strong operational performance and a transformative acquisition. The investment firm reiterated its Buy rating and $270 price target for the company, which specializes in aviation maintenance, repair, and overhaul (MRO).
Record Quarter Fuels Optimism
In a report released on August 5, VSE Corporation announced second-quarter financial results that significantly exceeded consensus estimates. The strong performance was driven by a combination of organic growth and contributions from recent strategic acquisitions.
Key highlights from the quarter include:
- Record Revenue: $449.1 million, a 65.0% increase year-over-year.
- Record Adjusted EBITDA: $86.0 million, a 98.0% increase year-over-year.
- Record Adjusted EBITDA Margin: 19.2%, an expansion of 320 basis points.
The company attributed the growth to robust activity in the commercial engine aftermarket, new business contracts, and market share gains. According to the report, organic growth accounted for approximately 14% of the revenue increase.
Transformative Acquisition Strategy
 Ad
A significant contributor to the record results was the integration of recently acquired businesses, including PAG, Aero 3, and NorthStar. VSE closed its $2.03 billion acquisition of PAG on May 5, the largest in its history.
This acquisition materially expands VSE's scale, global reach, and repair capabilities across commercial aviation, defense, and other end markets. The company noted that integration efforts are now underway to capitalize on commercial and operational synergies.
Upgraded Full-Year Guidance
Following the strong quarterly performance, VSE management raised its guidance for fiscal year 2026. The company now expects revenue growth of 61%-64%, up from a previous forecast of 57%-61%.
EBITDA margin guidance was also increased to a range of 18.7%-19.0%, from 18.1%-18.5% previously. Management reiterated its goal of achieving consolidated adjusted EBITDA margins above 20% in the near future. In response to the results and outlook, B Riley stated it is reviewing its estimates with an upward bias, while Stifel also reportedly increased its price target on the company.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.