
Story
Snowflake, MongoDB Earnings Face Scrutiny Amid Divergent Valuations
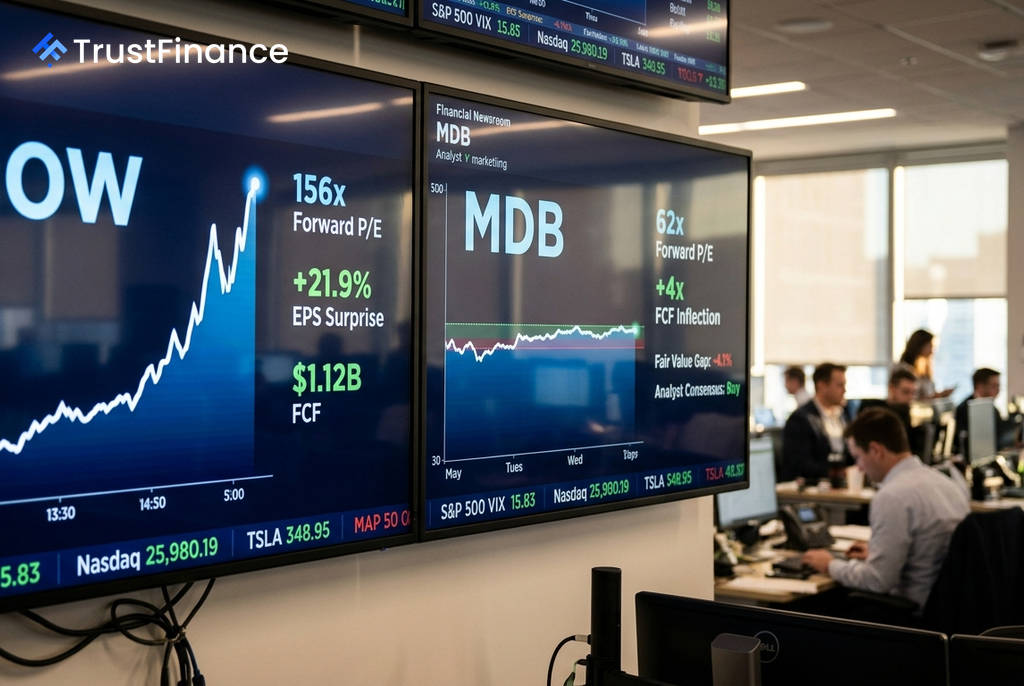
Cloud data platforms Snowflake (SNOW) and MongoDB (MDB) are scheduled to release their quarterly financial results this week, with both companies entering the period on the back of strong execution. However, a significant divergence in their valuations and recent stock performance sets a different stage for each ahead of their announcements.
High Bar for Post-Earnings Performance
Both companies have a track record of consistently beating earnings per share (EPS) estimates over the past four quarters. Despite this, positive surprises have not always translated into stock gains, highlighting the high expectations embedded in their share prices.
Market history shows that even strong reports can be punished if they fall short of perfection. In previous quarters, MongoDB's stock fell 23% after one strong report, while Snowflake saw a nearly 10% decline after another, underscoring the pressure on both firms to not only beat estimates but also provide robust forward-looking guidance.
A Tale of Two Valuations
Analysis of key financial metrics reveals a sharp contrast between the two software firms. Snowflake carries a much richer valuation, which could leave it more vulnerable to a post-earnings sell-off if results are not exceptional.
- Snowflake (SNOW): Trades at a forward price-to-earnings (P/E) ratio of 156.3x. Its stock has rallied 87.4% in the past three months, and its current price is approximately 22% above its calculated fair value, according to Investing.com data.
- MongoDB (MDB): Trades at a more modest forward P/E of 61.7x. The stock's price is only about 4% above its fair value, suggesting a more balanced risk profile.
This valuation gap is also reflected in their enterprise value-to-revenue multiples, with Snowflake trading at roughly 22x compared to MongoDB's 11.5x.
 Ad
Free Cash Flow Becomes a Key Differentiator
A critical factor in MongoDB's investment case has been a dramatic improvement in its free cash flow (FCF). The company saw its FCF surge by 314% in a single fiscal year, jumping from $121 million to $500 million.
This rapid growth signals a potential inflection point in operating leverage, a fundamental shift that can re-rate a company's stock. While Snowflake also generates substantial and growing free cash flow, MongoDB's explosive FCF growth represents a more transformative change to its financial profile.
Competitive and Market Context
Snowflake continues to navigate a highly competitive environment, facing pressure from rivals like Databricks. Meanwhile, some analysts see continued strength for MongoDB's Atlas cloud database platform, with Goldman Sachs previously forecasting growth that could exceed the company's own guidance.
Given its steep valuation and recent run-up, Snowflake's stock appears priced for a flawless report. In contrast, MongoDB's more moderate valuation and significant FCF improvements may offer a more forgiving setup for investors heading into this week's earnings announcements.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.