
Story
Petco Credit Rating Upgraded to B2 by Moody's on Debt Reduction and Operational Turnaround
Summary
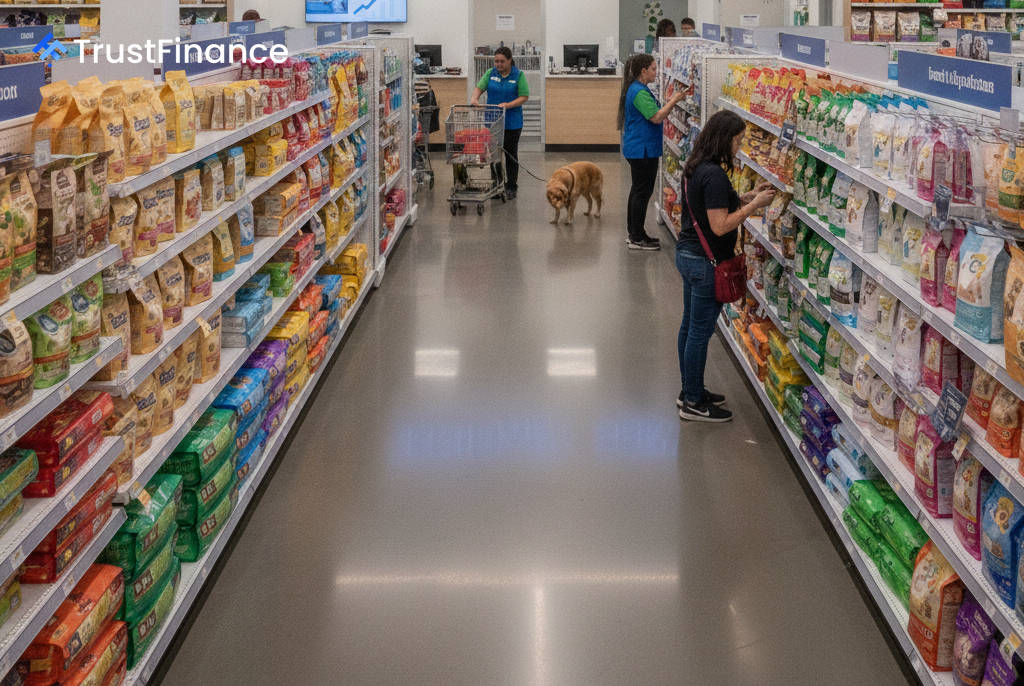
Moody's Ratings raised Petco's corporate family rating, citing the retailer's successful operational restructuring, focus on profitability, and voluntary debt paydown of approximately $170 million.
Moody's Ratings has upgraded Petco Health and Wellness Company's (NASDAQ:WOOF) corporate family rating to B2 from B3, attributing the move to the pet retailer's successful operational turnaround and consistent efforts to reduce its debt load. The ratings agency maintained a stable outlook on the company.
Turnaround Strategy Fuels Upgrade
The upgrade reflects Moody's confidence in Petco's strategic shift toward prioritizing profitability over sales volume. This strategy, initiated in 2025, has led to improved governance and a more conservative approach to debt management, according to the ratings agency.
Key components of the operational restructuring include:
- Scaling back promotional activity.
- Overhauling its product assortment to focus on higher-margin items.
- Expanding its veterinary services footprint.
- Closing underperforming store locations.
 Ad
As a result of these efforts and stronger cash generation, Petco has voluntarily paid down approximately $170 million in debt over the last twelve months. The company has a stated goal of bringing its net leverage down to a 2.0x target.
Financial Outlook and Remaining Risks
Moody's also raised its ratings on Petco’s probability of default to B2-PD and its senior secured debt, while affirming the company's top-tier SGL-1 liquidity rating. The agency projects Petco will maintain an adjusted leverage of around 3.5x debt-to-EBITDA and interest coverage of 1.5x over the next 12 to 18 months.
Despite the positive action, Moody's noted that Petco's credit profile faces constraints. These include execution risks in a competitive retail environment with cautious consumers and potential governance considerations stemming from its majority ownership by private equity firms CVC Capital Partners and Canada Pension Plan Investment Board. A sustained debt-to-EBITDA ratio below 4.5x could trigger further rating upgrades.
Read next
More on Stocks
MOEX Russia Index Falls 0.76% as Mining and Energy Stocks Decline
Russia's benchmark stock index closed lower on Monday, dragged down by losses in the mining, power, and oil & gas sectors. The Russian Volatility Index rose, indicating increased market uncertainty.

Meta Taps Tucker Bounds for Top Communications Role, Pivoting Predecessor to AI
Meta Platforms has promoted long-time executive Tucker Bounds to lead global communications, while moving former PR head David Ginsberg to a new role focused on applying artificial intelligence to product development.
Colombian Stocks Edge Lower as Financials and Utilities Weigh on COLCAP
Colombia's benchmark COLCAP index closed down 0.19% on Monday, pressured by declines in the financial, investment, and public services sectors despite gains in some individual stocks.

Mexican Stocks Close Nearly Flat as S&P/BMV IPC Dips 0.07%
Mexico's benchmark stock index, the S&P/BMV IPC, finished Monday's session with a marginal loss of 0.07%, as declines in industrial and consumer-focused stocks offset a market where more individual stocks advanced than fell.