
Story
Papa John's Rejects Takeover, Suspends Dividend as Sales Slump
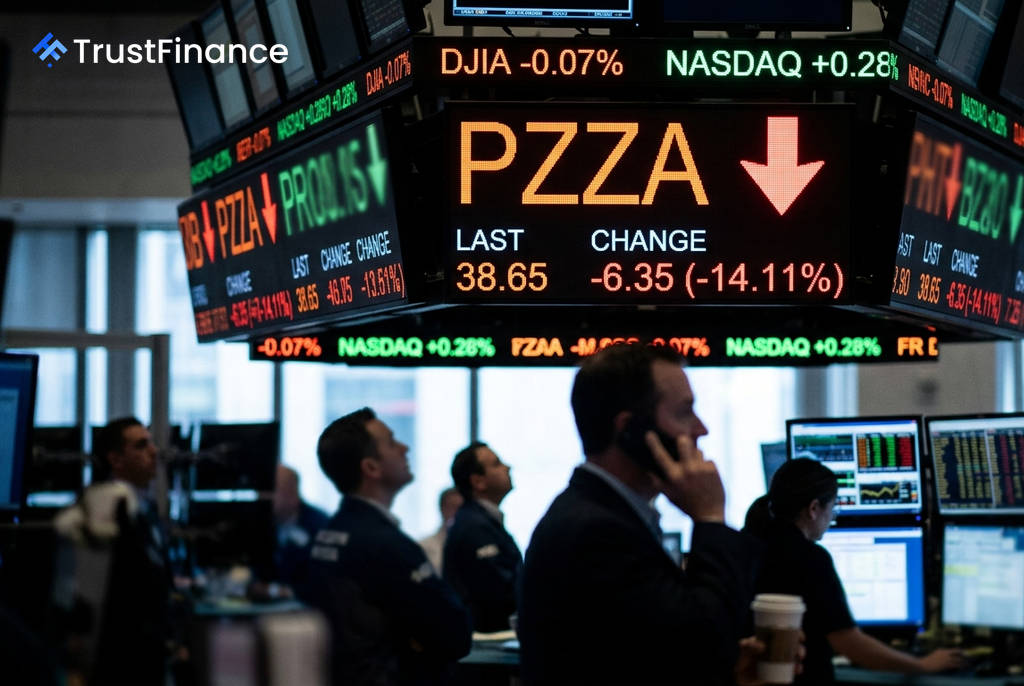
Papa John’s International Inc. (NASDAQ: PZZA) has concluded an 18-month strategic review, deciding against a sale of the company and instead committing to an internal transformation plan. The announcement, made during its Q2 2026 earnings call, was accompanied by a dividend suspension and weak financial results, causing shares to fall sharply in pre-market trading.
Takeover Hopes Dashed
The company's board stated it had conducted a "comprehensive review" of its strategy, which included exploring a potential sale. Management said on the call, "Our advisers have made clear that for Papa John's, the value creation opportunity is the execution of our transformation plan."
This decision effectively rejects reported interest from Qatari-backed Irth Capital Management, which holds an approximate 10% stake in the pizza chain. The Wall Street Journal reported in March 2026 that Irth had submitted a take-private offer of $47 per share. According to Reuters, Irth was also reportedly working with Papa John's largest U.S. franchisee on a proposal.
Weak Earnings and Outlook
The strategic shift comes amid deteriorating performance. The company announced it would suspend its quarterly dividend beginning in the third quarter of 2026 to preserve capital for its turnaround efforts.
Key figures from the company's second-quarter earnings release include:
 Ad
- Total Revenue: $482.4 million, down 8.8% year-over-year.
- North America Comparable Sales: A decline of 8.3%.
- Adjusted Diluted EPS: $0.24, down from $0.28 in the prior-year period.
Looking ahead, Papa John's set its full-year 2026 adjusted EBITDA guidance at $180 million to $190 million. According to StockStory, the midpoint of this range falls short of the analyst consensus of approximately $200 million.
Focus on Internal Turnaround
CEO Todd Penegor acknowledged in the earnings release that the company's transformation is "taking longer than anticipated" but pointed to "encouraging progress" in its rewards program and customer ordering experience. A notable bright spot was a 1.5% rise in international comparable sales, marking the seventh straight quarter of growth in that segment.
While formally ending the sale process for now, the board noted it "remains open to other alternatives to maximize value." For investors, the immediate focus will be on whether management's internal plan can generate value that exceeds the premium offered in the rejected takeover bids.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.