
Story
Lakala H1 Profit Soars on Asset Sale, But Q2 Earnings Plunge 42%
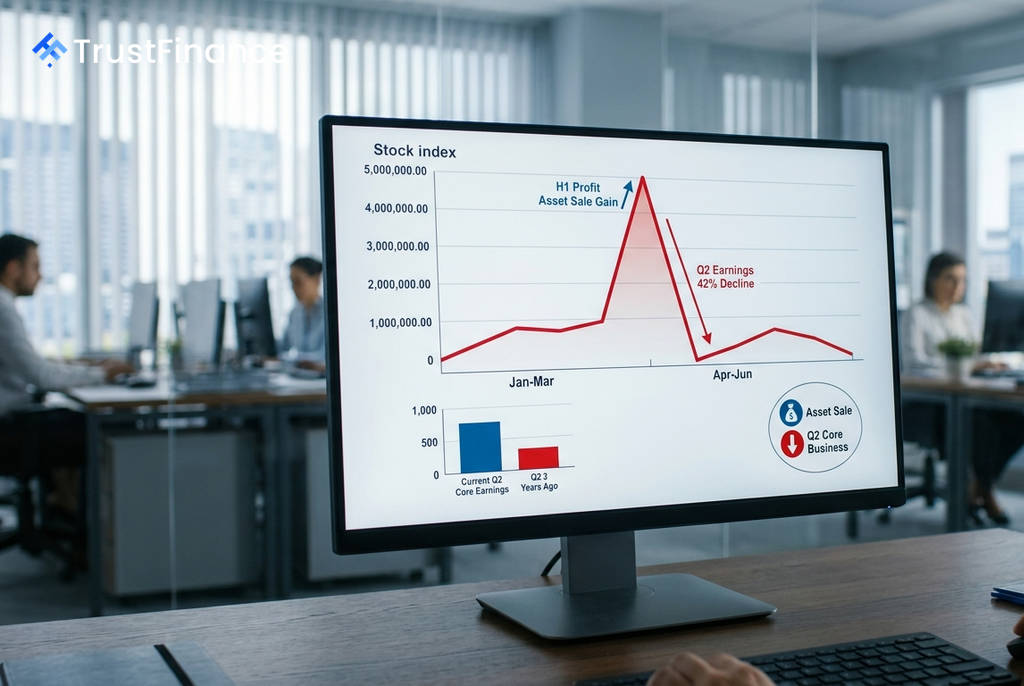
Chinese payment services provider Lakala (300773.SZ) reported a 192% year-over-year surge in first-half net profit, a figure heavily inflated by a one-time gain from the sale of its entire stake in marketing firm BlueFocus. However, the company's second-quarter earnings fell sharply and its core profitability remains below levels from two years ago, signaling underlying challenges for its primary business.
Profit Driven by Investment Gains
According to its semi-annual report released on August 7, Lakala generated revenue of ¥3.26 billion in the first half of the year, a 22.86% increase from the prior year. Net profit attributable to shareholders jumped to ¥669 million, a 191.67% increase.
However, after excluding non-recurring items, the company's net profit was just ¥2.19 billion, a more modest 50.28% rise. The significant difference stems from the liquidation of its holdings in BlueFocus (300058.SZ) during the first quarter, which resulted in an investment gain of approximately ¥5.51 billion. Over the entire investment period, Lakala confirmed total gains of about ¥1.53 billion from its BlueFocus position, according to company disclosures.
Core Business and Q2 Performance Weaken
The reliance on this one-time gain masks persistent weakness in Lakala's core operations. The company's adjusted net profit for the first half remains significantly below the ¥4.12 billion it earned in the same period two years prior. Analysts cited in the report noted this indicates the core payments business is facing intense competition and pressure on its fee structure.
A closer look at the second quarter reveals a concerning trend:
- Revenue: ¥1.64 billion, an increase of 21.53% year-over-year.
- Net Profit: ¥74 million, a sharp 42% decrease compared to the second quarter of last year.
 Ad
This discrepancy between rising revenue and falling profit in the second quarter underscores that the headline growth in the first half was not driven by sustainable operational performance. Analysts suggest that such an earnings structure, dependent on volatile market gains, fails to provide a stable outlook for investors.
Operational Segments and Strategic Moves
Despite the profit concerns, Lakala's business segments showed volume growth in the first half. Total domestic acquiring transaction volume reached ¥2.25 trillion, up 14.99%. QR code payments grew 29.38%, while bank card transactions recovered with 7.73% growth. Cross-border payment transaction volume also rose by 46.38%.
In a separate announcement, Lakala proposed an interim dividend of ¥2.0 per 10 shares, totaling approximately ¥217 million. The company also announced a ¥150 million investment into an AI-focused venture capital fund to explore future growth opportunities. This move follows a period where its former investment in BlueFocus benefited from a surge in AI-related stock valuations.
Hong Kong IPO Stalls Amid Profitability Concerns
Lakala's application for a public listing on the Hong Kong Stock Exchange, submitted in October of last year, lapsed in April with no further progress announced. Analysts believe the stall is linked to investor and regulatory scrutiny over the sustainability of the company's earnings.
The significant contribution from investment gains, rather than core business operations, likely complicates the valuation narrative for a public offering. According to analysts, demonstrating consistent, organic profit growth from its primary payment services will be critical for any future listing attempts.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.