
Story
Kerry Group Reports Better-Than-Expected Volume Growth, Reaffirms 2026 Outlook

Summary
The global taste and nutrition company posted second-quarter volume growth of 3.5%, surpassing analyst estimates, and maintained its full-year earnings guidance despite a significant miss on first-half free cash flow.
Kerry Group reported second-quarter volume growth that outpaced market expectations, signaling resilient demand for its taste and nutrition products. The company reaffirmed its full-year earnings forecast, even as first-half free cash flow fell short of consensus due to timing-related issues in working capital and capital expenditures.
First-Half Financials
Kerry's volume growth for the second quarter of 2026 reached 3.5%, ahead of analyst estimates which ranged from 3.0% to 3.1%. For the first half of the year, the company's earnings before interest, taxes, depreciation, and amortization (EBITDA) came in at €558 million, matching consensus expectations.
Key financial highlights for the first half of 2026 include:
- EBITDA Margin: Expanded by 60 basis points year-over-year to 16.7%.
- Adjusted EPS: Grew 7.9% in constant currency.
- Full-Year Guidance: The company maintained its forecast for constant currency adjusted EPS growth of 6% to 10%, compared to analyst estimates of 8.3%. A 3% foreign exchange headwind is anticipated for the full year.
Cash Flow and Regional Performance
 Ad
While earnings met expectations, first-half free cash flow was €262 million, a 29% shortfall compared to the consensus estimate of €371 million. The company attributed this to an €81 million movement in working capital tied to seasonality and receivable timing, as well as a €24 million increase in capital expenditure versus the prior year.
Regionally, the Americas led with 3.9% volume growth in the second quarter, driven by strong performance in snacks, meat, and beverages. The Asia Pacific, Middle East & Africa (APMEA) region was the fastest-growing, posting 5.2% volume growth, while Europe recorded a more modest 0.6% growth.
Balance Sheet and Dividend
Kerry's financial position remains solid, with net debt standing at €2,370 million. This represents a leverage ratio of 2.0 times net debt to adjusted EBITDA. In a sign of confidence, the company declared an interim dividend of €0.462 per share.
Read next
More on Stocks
Electric Trucks Reach Cost Parity with Diesel in Key EU Markets Amid Fuel Price Surge, Report Finds
A surge in diesel prices has made electric trucks cheaper to own and operate than their diesel counterparts in six major European Union countries, according to a new analysis by environmental group Transport & Environment.

Delta Flight to Boston Diverts to Portugal After Smoke Fills Cabin
A Delta Air Lines flight from Barcelona to Boston made a safe emergency landing in Porto, Portugal, on Sunday after reports of smoke in the cabin. Eleven passengers received medical attention following the diversion of the Airbus A330.
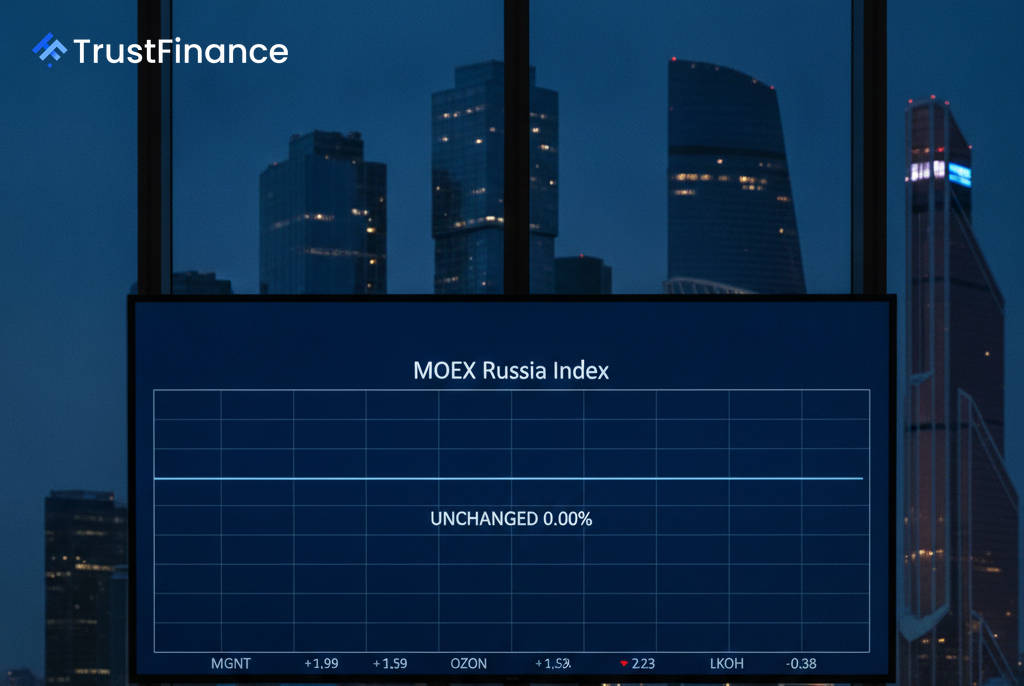
MOEX Russia Index Closes Flat Amid Divergent Sector Performance
Russia's benchmark stock index ended the session unchanged, as gains in consumer-focused companies like Magnit and Ozon were offset by losses in energy giants following a drop in global oil prices.
Anthropic CEO Dario Amodei to Meet Privately With Trump Ahead of AI Summit
Dario Amodei, CEO of AI firm Anthropic, is scheduled for a one-on-one dinner with President Donald Trump on Sunday, setting the stage for a wider White House summit on artificial intelligence policy later in the week.