
Story
Crypto Taxpayer's IRS Audit Exposure Cut from $1.55M to $148K After Reconstructing Blockchain Data
Summary
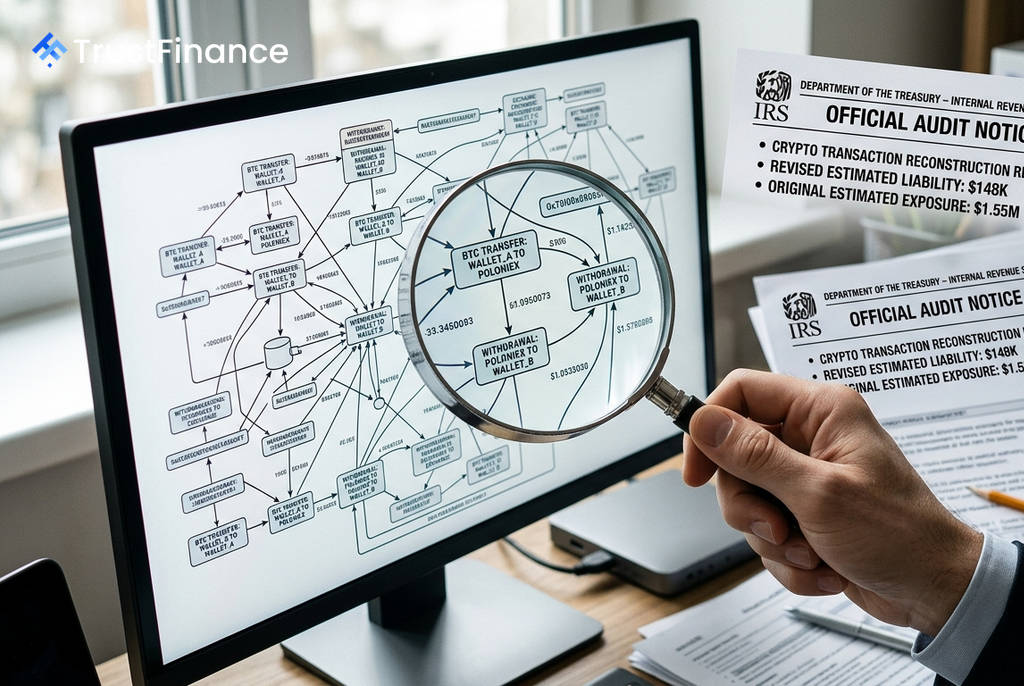
A U.S. taxpayer facing a potential $1.55 million IRS tax bill saw their liability reduced to approximately $148,000 after tax firms reconstructed blockchain data to prove that disputed transactions were non-taxable wallet transfers.
A cryptocurrency investor facing an estimated $1.55 million tax liability from an Internal Revenue Service (IRS) audit has settled the matter for approximately $148,000, according to the tax firms involved. The resolution came after specialists reconstructed the client's transaction history to prove that disputed withdrawals were non-taxable transfers between the taxpayer's own accounts.
The Challenge of Incomplete Records
The case highlights the significant risks crypto investors face from incomplete or inaccessible exchange data. The IRS initiated an audit after receiving information, likely through a John Doe summons, indicating unreported transactions from the Poloniex exchange. According to a statement from Crypto Tax Made Easy, the firm that handled the data reconstruction, the IRS initially assessed approximately $4.2 million in unreported income and capital gains.
The core issue arose because Poloniex had ceased operations for U.S. users, preventing the taxpayer from accessing their own records. The partial data available to the IRS showed funds moving out of the exchange, which could be interpreted as taxable income or gains, without showing the corresponding funds that the taxpayer had initially deposited.
"The IRS has data, but the data does not always explain the full transaction history," said Matt Walrath, Founder of Crypto Tax Made Easy. "When a taxpayer cannot document wallet ownership, exchange deposits, withdrawals, and cost basis, a transfer can be misread as income."
Reconstructing the Transaction Trail
To counter the IRS's assessment, Crypto Tax Made Easy performed an analysis of blockchain records to trace the flow of the client's funds. The firm demonstrated that the cryptocurrency in question originated from a wallet owned by the taxpayer, was deposited into exchanges, and was later withdrawn back to a wallet the taxpayer controlled.
 Ad
This evidence supported the position that the transactions were largely transfers between the client's own accounts. Under U.S. tax law, digital assets are treated as property, and transferring them between one's own wallets or accounts is generally not a taxable disposition.
Securus Advisors, a CPA firm representing the client before the IRS, presented this reconstructed history to the agency. The final settlement of about $148,000, which included penalties and interest, represented roughly 9.5% of the initial estimated tax exposure.
Implications for Investors
This audit underscores the critical importance of meticulous record-keeping for anyone transacting in digital assets. Taxpayers can be held responsible for proving the nature of their transactions, a task that becomes difficult when exchanges become defunct or restrict access.
"Crypto tax defense depends on whether the records can be explained in a way an examiner can follow," said Michael Bergloff, a CPA and Partner at Securus Advisors. "Raw exchange data may show funds moving out without showing that the same taxpayer moved funds in first." The firms noted that past results do not guarantee future outcomes, as each tax case is dependent on its specific facts and records.