
Story
ConocoPhillips Leads Oil Majors on Margins and Valuation, Analysis Shows
Summary
A sector analysis highlights ConocoPhillips for its superior profit margins and attractive valuation compared to peers like ExxonMobil and Chevron, even as the energy sector navigates a complex crude market.
ConocoPhillips (COP) is distinguishing itself from its integrated oil peers with superior profit margins and a more attractive valuation, according to a recent sector analysis, even as energy markets contend with conflicting supply and demand signals. The company's performance metrics stand out against competitors including ExxonMobil (XOM), Chevron (CVX), and Shell (SHEL).
Sector Navigates Divergent Trends
The analysis comes as oil company equities show strong performance, with major players gaining between 27% and 39% year-to-date. This bullish run contrasts with a more cautious outlook for crude oil, where Brent crude is trading in the low $60s per barrel despite forecasts for a supply surplus.
The International Energy Agency (IEA) had previously flagged a potential surplus of 3.84 million barrels per day entering the year. In a similar vein, OPEC has trimmed its 2026 demand growth forecast for three consecutive months, now projecting an increase of just 780,000 barrels per day, according to the source material.
A Comparison of the Majors' Metrics
A financial snapshot of the sector's largest companies reveals significant differences in valuation and profitability. While most majors have seen fundamentals normalize since the 2022 energy shock, their current financial health varies.
 Ad
- ExxonMobil (XOM): Trades at a 20.3x price-to-earnings (P/E) ratio with a perceived fair value upside of just 2.3%, suggesting its growth is largely priced in.
- Chevron (CVX): Offers a higher dividend yield (3.5%) and 10% upside, but its net income margin compressed to 6.7% in fiscal year 2025.
- ConocoPhillips (COP): Features a lower P/E ratio of 16.4x among U.S. peers and a significant fair value upside of 21.1%.
- Shell (SHEL): Appears as the most undervalued based on its P/E of 10.7x and 19.3% fair value upside, though this may reflect a discount for European regulatory risks.
ConocoPhillips' Standout Performance
The analysis identifies ConocoPhillips as a standout due to its combination of strong operational efficiency and favorable valuation. Its pure-play upstream model is cited as a key advantage, protecting it from compressing refining spreads that can affect more diversified peers.
The company's best-in-class net income margin of 13.3% in fiscal year 2025 far outpaces U.S. competitors. This efficiency, combined with a return on equity (ROE) of 14.1%, presents a compelling financial profile. A key risk to monitor, however, is its higher debt-to-equity ratio of 35.6% compared to U.S. peers.
Read next
More on Stocks
Cleveland-Cliffs Stock Falls as Subsidiary Idles Plant Citing US Tariffs
Shares of Cleveland-Cliffs dropped nearly 8% following a report that its Canadian unit, Stelco, will halt operations at a key processing facility due to pressures from U.S. import tariffs. The company plans to consolidate production at another plant to maintain overall output.
AMD to Acquire AI Startup World Labs for $8.2 Billion in All-Stock Deal
Advanced Micro Devices announced an $8.2 billion all-stock deal to buy spatial intelligence startup World Labs, a strategic move to challenge Nvidia's leadership in next-generation AI for robotics and simulation.

Pfizer, BioNTech, Moderna Lose Bid to Dismiss Bayer's mRNA Patent Lawsuit
A U.S. federal judge has denied a request from major COVID-19 vaccine makers to dismiss a patent infringement lawsuit filed by Bayer AG. The case, which will now proceed, centers on messenger RNA technology Bayer's Monsanto unit claims it developed.
AAR to Acquire $1.8 Billion Controlling Stake in MRO Holdings, WSJ Reports
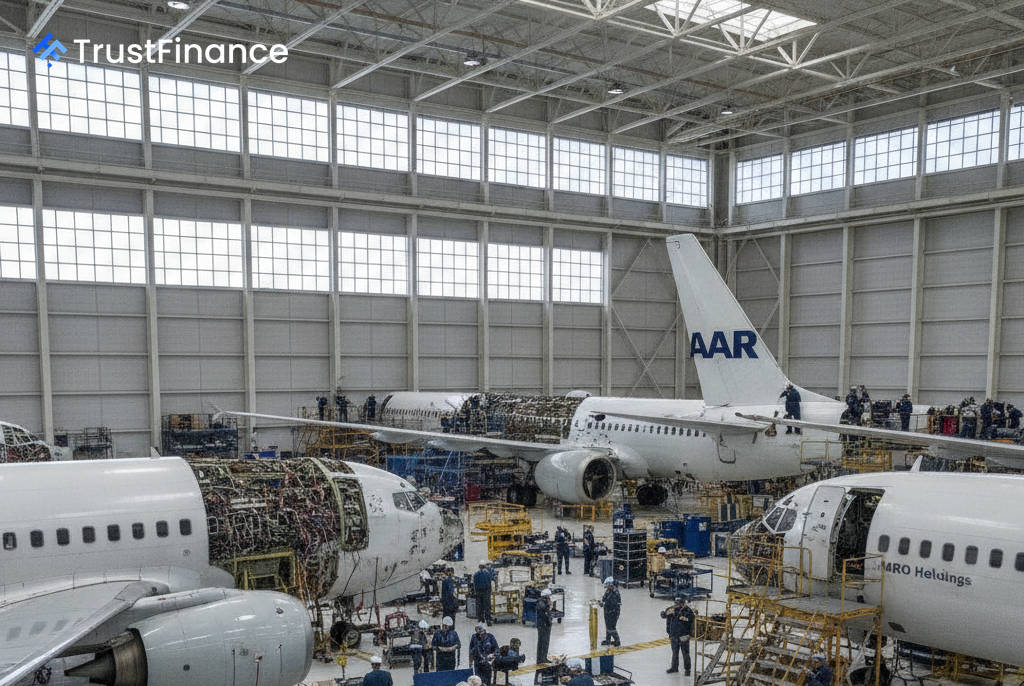
Aviation services provider AAR Corp. has reportedly agreed to buy a 65% stake in aircraft maintenance firm MRO Holdings for $1.8 billion, a move aimed at expanding its service capacity and boosting profit margins.