
Story
Celsius and Monster Stock Diverge, Offering Investors a Choice Between Value and Stability
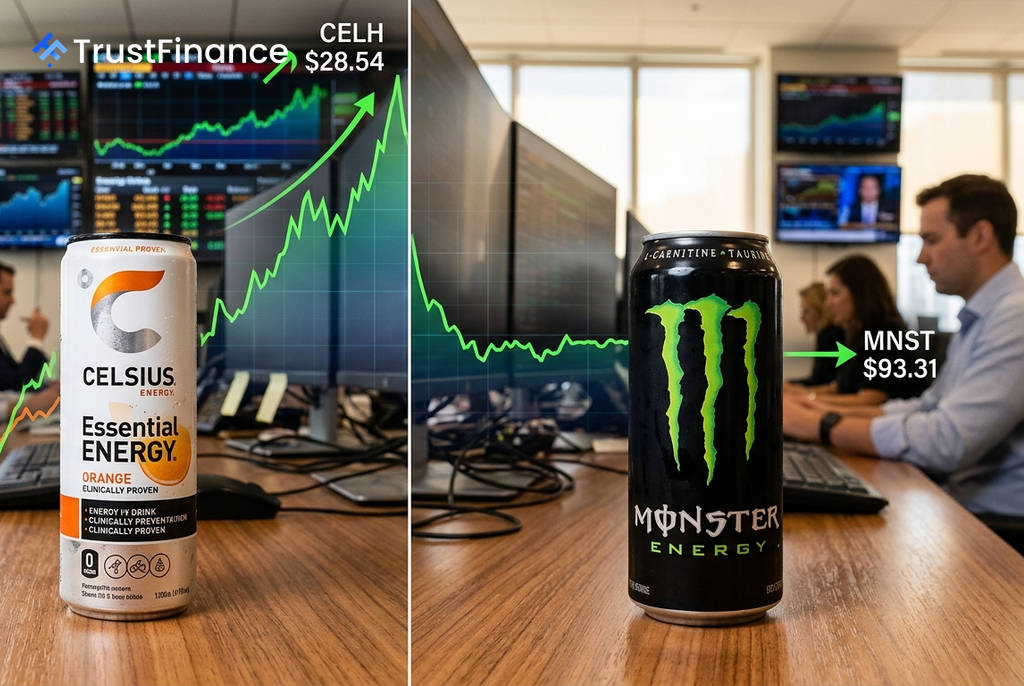
A sharp divergence has emerged in the energy drink sector, pitting high-growth Celsius Holdings (NASDAQ: CELH) against the established market leader Monster Beverage Corp. (NASDAQ: MNST). Celsius shares have tumbled approximately 49% over the past six months, while Monster has climbed 65% over the last year, creating a distinct choice for investors between a potential value play and a proven, but pricey, industry giant.
According to an analysis by Investing.com, Celsius now trades at a significant discount. The firm's model places Celsius's fair value 41.3% above its recent price of $28.54. In contrast, Monster, trading at $93.31, is estimated to be 13.4% overvalued, with Wall Street analysts seeing minimal upside of just 0.6% on average.
Monster's Profitability Commands a Premium
Monster Beverage stands out as a highly profitable and stable company, justifying its premium valuation in the eyes of many market participants. The company boasts a robust net income margin of 23.1%, nearly four times that of Celsius, and a strong return on invested capital (ROIC) of 26.7%, according to the source data.
Key financial strengths for Monster include:
- Market capitalization: $94.26 billion
- Balance sheet: Virtually no debt, with a debt-to-equity ratio of just 1.1%.
- Profitability: A gross margin of 55.5% and a net margin of 23.1%.
However, this operational excellence is reflected in its stock price. With a forward price-to-earnings (P/E) ratio of 41.5x, the stock leaves little room for error. This sentiment is echoed by analysts, with Deutsche Bank recently downgrading the stock to Hold and both JPMorgan and BMO Capital Markets assigning neutral-equivalent ratings.
 Ad
Celsius Bets on an Earnings Rebound
Celsius presents a classic growth story that has hit a patch of turbulence, leading to a potential valuation opportunity. The company's revenue has grown an explosive 123.3% over the last twelve months, partly boosted by its acquisition of the Alani Nu brand. Despite this, its net income margin is a comparatively slim 5.9%.
The core of the investment case for Celsius lies in its valuation disconnect. The stock trades at a trailing P/E ratio of 64.6x, but its forward P/E is just 17.8x. This sharp compression implies that analysts expect a significant surge in earnings to catch up with its revenue growth. While some analysts have revised earnings estimates downward, others, like Bernstein and JPMorgan, maintain Outperform and Overweight ratings, respectively, signaling continued conviction in the long-term story.
Market Weighs Execution Risk vs. Established Quality
The current market dynamic presents investors with a clear trade-off. Monster offers a lower-volatility option with a proven track record of profitability and a fortress-like balance sheet, but its stock appears fully priced. Any slowdown in growth could trigger what Deutsche Bank termed a "meaningful valuation reset."
Celsius, meanwhile, offers substantial upside if it can successfully expand its margins and prove its growth trajectory is sustainable. The stock's recent decline has priced in significant execution risk, creating an opportunity for investors who believe the market has become overly pessimistic. The choice hinges on an investor's appetite for risk and their conviction in Celsius's ability to translate rapid sales growth into bottom-line profit.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.