
Story
Apple's Growth Catalysts Multiply with China AI Deal and Foldable iPhone Plans

Summary
Apple is poised for a potentially pivotal period, buoyed by regulatory approval for its AI features in China and a strong pipeline of new hardware, including a foldable iPhone.
Apple Inc. (AAPL) is facing a series of significant potential growth drivers over the next year, highlighted by a crucial regulatory approval for its AI services in China and an ambitious hardware roadmap that includes a foldable iPhone. The developments come as the company prepares to report its fiscal third-quarter earnings on July 30, with investors closely watching to see if it can extend its four-quarter streak of exceeding profit estimates.
China AI Approval Unlocks Key Market
Perhaps the most significant near-term development is the approval of Apple Intelligence by China's cyberspace regulator. This allows Apple to deploy its on-device generative AI features on iPhones in the country, a critical step for competing in the world's largest smartphone market.
To comply with local regulations, the service will be powered by large language models from Chinese technology firms, including Alibaba's Qwen and Baidu's AI. The move addresses a key competitive disadvantage Apple faced against local rivals like Huawei and Xiaomi, which had already integrated advanced AI features into their devices.
Hardware 'Super-Cycle' on the Horizon
A robust pipeline of new products is expected to further fuel momentum. According to market reports and analyst commentary, Apple's upcoming hardware catalysts include:
 Ad
- Foldable iPhone: The company is reportedly targeting production of approximately 10 million units in the fourth quarter of 2026, marking its entry into a new premium product category.
- Expanded iPhone Lineup: A Nikkei report indicated plans for five new iPhone models between the second half of 2026 and the first half of 2027.
- Price Increases: Analysts at Citi, who raised their price target to $365, anticipate margin-accretive price increases focused on higher-end models.
- Chip Strategy: Apple continues to secure its supply chain with an extended deal with Broadcom for custom chips through 2031 and is reportedly exploring acquisitions of AI chip startups.
Earnings and Legal Filings in Focus
Investors are looking ahead to Apple's Q3 FY2026 earnings report on July 30. Wall Street consensus estimates stand at $1.89 for earnings per share (EPS) on $108.86 billion in revenue. The company has surpassed EPS estimates for the past four consecutive quarters.
Adding a layer of uncertainty, Apple filed a federal lawsuit against OpenAI on July 11, alleging that former executives stole trade secrets for OpenAI's consumer hardware initiatives. Analysts at Evercore ISI, who have an Outperform rating and a $365 price target on the stock, view the legal action as a net positive for protecting Apple's competitive moat.
Read next
More on Stocks
CIBC Offers Compelling Value Profile Among Major Canadian Banks
While TD Bank trades at the lowest price-to-earnings multiple, an analysis of yield and upside potential positions Canadian Imperial Bank of Commerce (CIBC) as a more balanced value investment among its peers.

Volvo Cars Appoints Klaus Zellmer as Next CEO to Succeed Hakan Samuelsson
Volvo Cars has named Klaus Zellmer as its next president and chief executive officer, replacing the departing Hakan Samuelsson. The transition comes as the automaker pursues an aggressive growth strategy amid market challenges.

Analyst 'Strong Buy' Ratings Signal Upside for TSX-Listed Miners
Several Canadian gold and copper miners, including Equinox Gold and Kinross Gold, are attracting strong buy ratings from analysts who project double-digit upside potential based on recent company-specific catalysts.
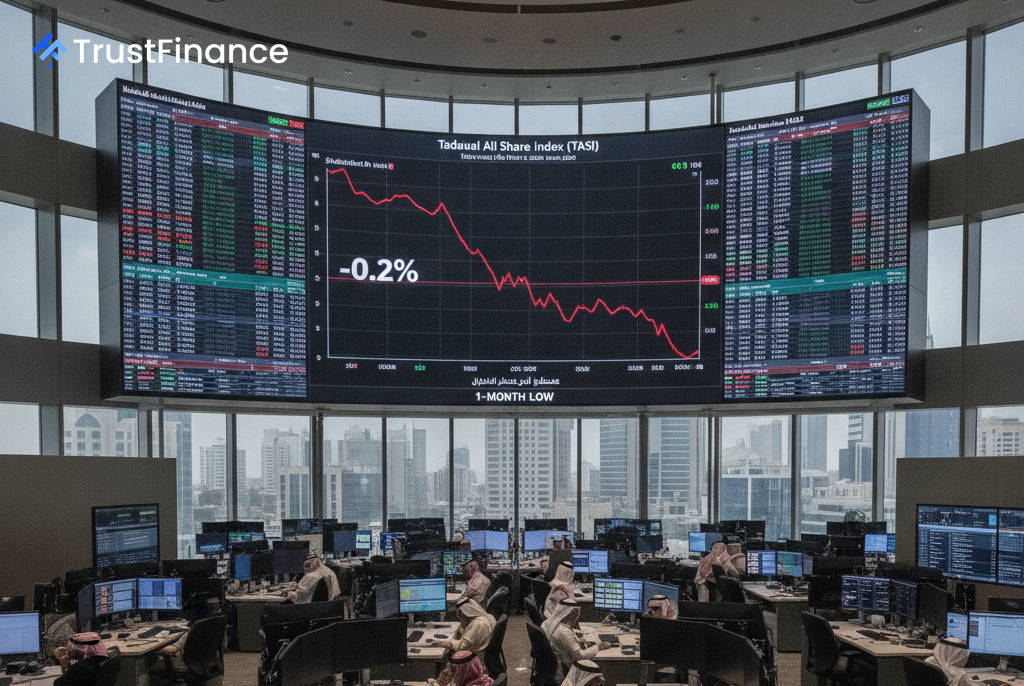
Saudi Tadawul All Share Index Slips to 1-Month Low on Broad Sector Declines
Saudi Arabia's benchmark stock index, the Tadawul All Share, closed down 0.26% on Sunday to reach its lowest point in a month, dragged lower by weakness in the insurance and energy sectors.