
Story
Adobe, Intuit Lead SaaS Value Plays Amid Sector-Wide Correction
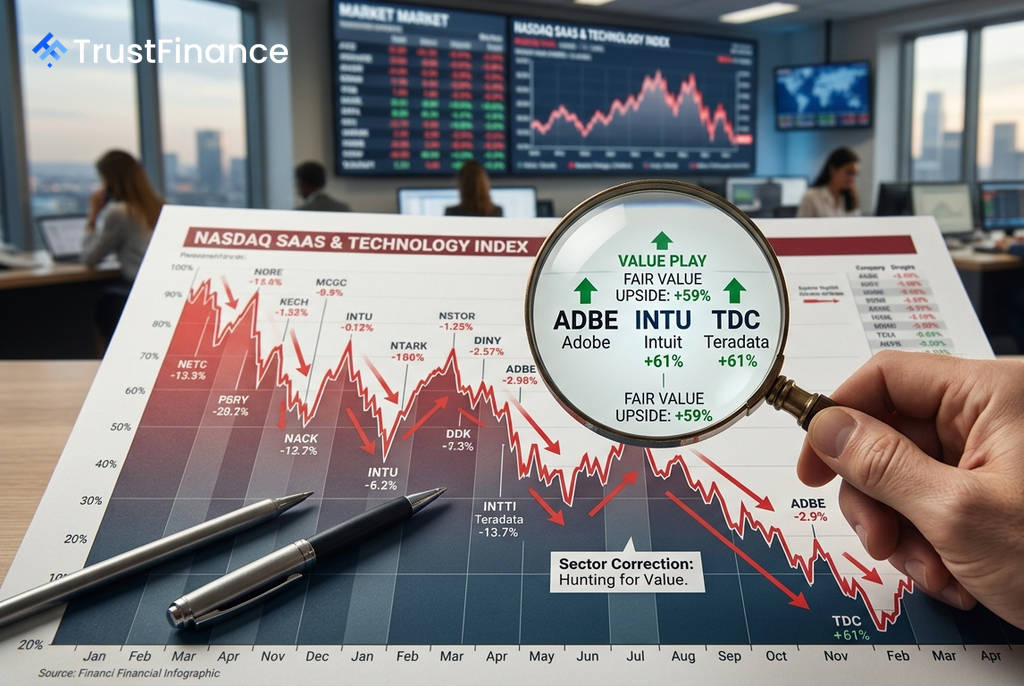
A significant market recalibration in the Software-as-a-Service (SaaS) sector has shifted investor focus from growth-at-all-costs to fundamental value, revealing deep discounts in established companies with resilient cash flows. Despite steep stock price declines over the past year, an analysis of market data indicates that firms like Adobe and Intuit now present substantial potential upside to their estimated fair values.
A New Calculus for SaaS Valuations
The broader SaaS industry has faced a sharp correction, with valuations for many major companies falling between 20% and 60% over the last 12 months. This downturn has prompted a shift in market sentiment, prioritizing tangible financial health over speculative growth.
Analysts, including those at CLSA, now suggest that the market will reward SaaS companies that demonstrate strong cash generation and a clear strategy for leveraging artificial intelligence. The era of valuing companies on revenue growth alone appears to be giving way to a more disciplined approach focused on profitability and free cash flow.
Key Value Candidates Emerge
Several established software companies stand out based on metrics like fair value upside and forward Price/Earnings-to-Growth (PEG) ratios. These figures suggest their current stock prices may not fully reflect their long-term earnings potential.
 Ad
- Adobe Inc. (ADBE): Shows a 59.3% potential upside to its fair value. Despite its stock being down 24.0% over the past year, it boasts a strong forward free cash flow (FCF) yield of 7.2% and a low PEG ratio of 0.29.
- Intuit Inc. (INTU): Has a potential fair value upside of 61.9%. The company's stock has fallen 57.5% in a year, but its PEG ratio is just 0.19, indicating its growth may be significantly undervalued.
- Teradata Corporation (TDC): Presents a unique deep-value case with a 61.2% fair value upside and a remarkable 70.0% stock return over the past year. However, this is tempered by negative revenue growth of -5.0%, positioning it as a higher-risk, contrarian investment.
The Emphasis on Cash Flow
The primary differentiator in the current market environment is the ability to generate cash. Adobe and Intuit exemplify this, pairing significant upside potential with durable business models in creative software and financial services, respectively. Their strong FCF yields underscore their financial stability in a volatile market.
In contrast, while Teradata's metrics are compelling from a value perspective, its shrinking revenue remains a key concern for analysts. The market's new playbook suggests that sustainable cash flow, not just a low valuation, is the key criterion for separating long-term winners from value traps in the SaaS industry.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.