
Story
Trucking Stocks Trade at Steep Discount to Railroads, But Margins Tell a Different Story
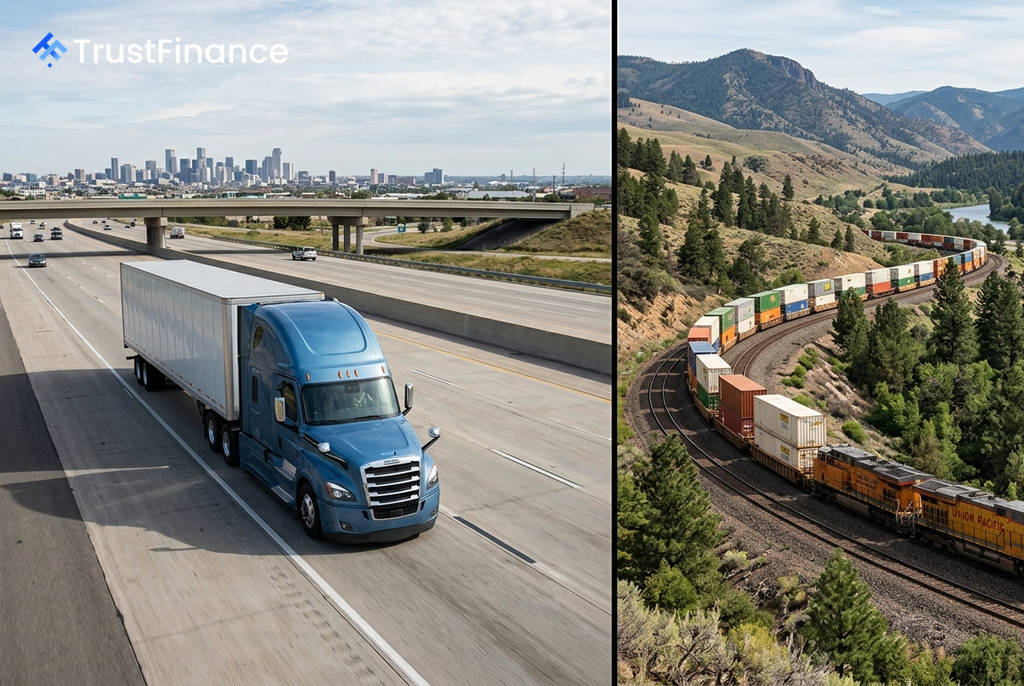
A wide valuation gap has opened in the U.S. freight sector, with trucking and logistics stocks trading at a significant discount to railroads. However, an analysis of operational performance shows that railroads' superior profitability and pricing power may warrant their premium, according to data from August 11, 2026.
The Valuation Divide
Trucking and parcel giants trade at considerably lower multiples than their railroad counterparts. FedEx (FDX) and UPS (UPS) are valued at 17.4x and 19.4x trailing earnings, respectively. In contrast, major railroads like Union Pacific (UNP), CSX (CSX), and Norfolk Southern (NSC) command price-to-earnings ratios in the 22x to 29x range.
This discount in the trucking sector is also reflected in cash flow metrics. FedEx and UPS offer attractive free cash flow yields of 6.8% and 6.1%, respectively, suggesting a higher return of cash relative to their market price compared to railroads, which cluster in the 2.2% to 3.7% range.
A Moat Built on Margins
The core reason for the valuation disparity lies in profitability. Railroads operate with margins that are fundamentally different from the more competitive trucking industry.
 Ad
- Railroad Operating Margins: Union Pacific and Canadian National (CNI) lead with impressive margins of 40.8% and 40.7%.
- Trucking Operating Margins: Most trucking firms operate in the single digits, with FedEx at 7.9% and J.B. Hunt (JBHT) at 7.5%.
This profitability gap stems from the railroad industry's oligopoly-like structure. Owning irreplaceable track infrastructure creates high barriers to entry and significant pricing power. The trucking industry, by contrast, faces intense competition and cyclical pressures. Old Dominion Freight Line (ODFL) is a notable exception, achieving a 25.8% operating margin, but it trades at a premium multiple of over 40x earnings to reflect this quality.
Implications for Investors
When viewed through a fair value lens, the sector appears largely overvalued. According to the analysis, UPS is the only stock among its peers trading below its estimated fair value, with a potential upside of 10.2%. Most other freight companies, including all major railroads, are trading at prices significantly above their calculated fair values.
This creates a clear choice for investors based on their definition of value. Those seeking lower multiples and higher shareholder yields may favor trucking stocks like UPS, which also leads the group with a 6.2% shareholder yield. Conversely, investors willing to pay a premium for high-quality, wide-moat businesses with consistent pricing power may find the railroads' superior margins and returns on equity more compelling, despite their richer valuations.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.