
Story
Toolmakers Stanley Black & Decker, Snap-on See Diverging Fortunes

Summary
The tools sector is experiencing a sharp divide, with strong professional demand boosting Snap-on while Stanley Black & Decker navigates a weaker consumer market despite a significant margin recovery.
A clear divergence has emerged in the tools and accessories sector, as robust demand from professional channels buoys premium brands while the consumer retail segment remains soft amid spending caution and tariff uncertainty. This split is creating distinct outlooks for the industry's largest players, Stanley Black & Decker (SWK) and Snap-on (SNA).
Professional Strength vs. Consumer Caution
Demand from commercial and industrial channels, particularly vehicle repair, is a significant tailwind. Snap-on management has described the vehicle repair market as being in a "golden age," citing structural drivers like aging vehicle fleets and increasing repair complexity. This has helped lift premium brands to record margins.
Conversely, the consumer-facing market is experiencing headwinds. Stanley Black & Decker's outdoor segment saw a 7% organic decline due to weather-related softness. The source also noted that elevated price sensitivity among consumers is forcing promotional activity, while a shift in enterprise spending toward AI is reportedly cannibalizing budgets for PC hardware and accessories, creating a structural drag.
Stanley Black & Decker's Margin Recovery
Stanley Black & Decker is viewed as a turnaround story, with its margin recovery being a key focus for investors. The company reported strong results in its power tools division, which posted 8% organic growth in the second quarter of 2026.
 Ad
Key financial highlights for SWK include:
- Gross Margin Expansion: Q2 gross margin expanded by 620 basis points year-over-year to 33.7%, with approximately 250 basis points attributed to net tariff refunds.
- Improved Guidance: Management guided for gross margins of 34%–35% in the second half of 2026 and raised its full-year EPS outlook to $5.20–$5.80.
- Financial Health: As of September 16, 2026, the company's debt-to-equity ratio stood at 58.2%, a figure noted by market bears.
Snap-on's Defensive Stability
Snap-on represents a more defensive position within the sector, benefiting from its strong foothold in the professional market. The company maintains consistently high margins, with a fiscal 2025 gross margin of 51.7% and a net income margin of 19.7%.
Snap-on's stable financial profile is supported by low leverage, with a debt-to-equity ratio of 21.7%. The company is also taking structural steps to mitigate future tariff risks by re-shoring manufacturing, such as moving a 14.4-volt power tool line from China to North Carolina. The primary risk noted for both companies would be a broader economic deterioration that drags the resilient professional channel down with the consumer market.
Read next
More on Stocks
U.S. Stock Futures Rebound as Markets Digest Hawkish Fed Rate Hike
U.S. stock futures rose in overnight trading, recovering from a sell-off triggered by the Federal Reserve's first interest rate hike in three years. Falling oil prices and positive corporate news helped lift market sentiment.
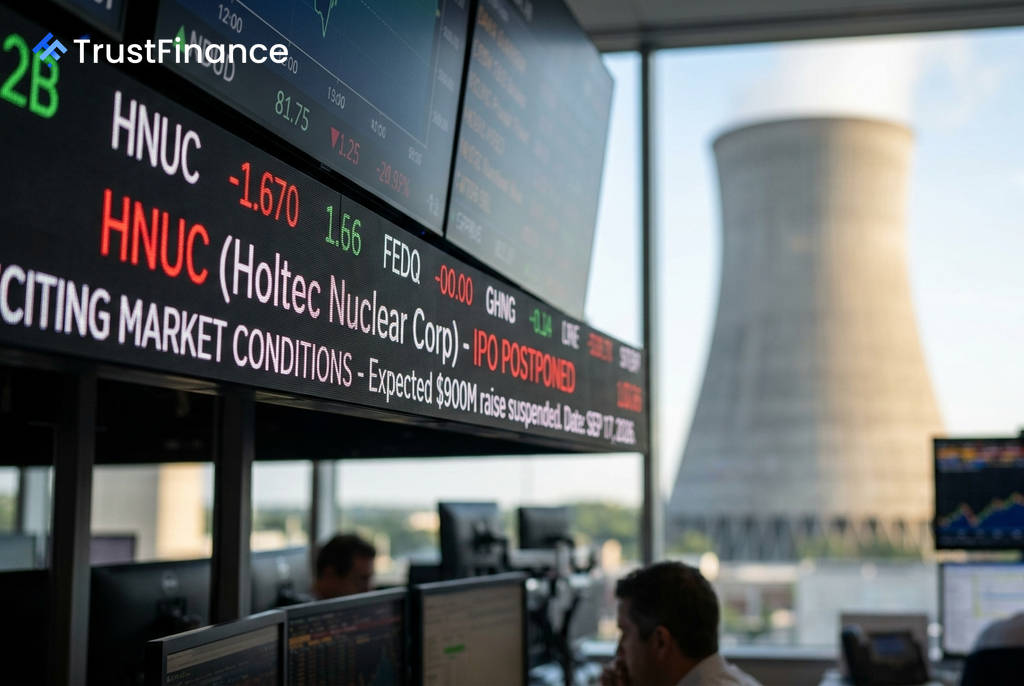
Holtec Suspends $900 Million IPO Amid Challenging Market Conditions
Nuclear services company Holtec Nuclear Corp. has postponed its U.S. initial public offering, which aimed to raise as much as $900 million, citing unfavorable market conditions and weak performance from recently listed peers in the sector.

Snap Stock Climbs on Enterprise Push for New Specs AR Glasses
Shares of Snap Inc. gained in after-hours trading after the company unveiled its new $2,195 Specs AR glasses and announced key enterprise partnerships with Salesforce, Nvidia, and AWS.

Gold Prices Fall as Hawkish Fed Outlook Boosts US Dollar
Gold prices declined after the Federal Reserve raised interest rates by 25 basis points and signaled further tightening, strengthening the U.S. dollar and increasing the opportunity cost of holding the non-yielding metal.