
Story
Palo Alto Networks Earnings Face High Bar Amid 'Priced for Perfection' Valuation
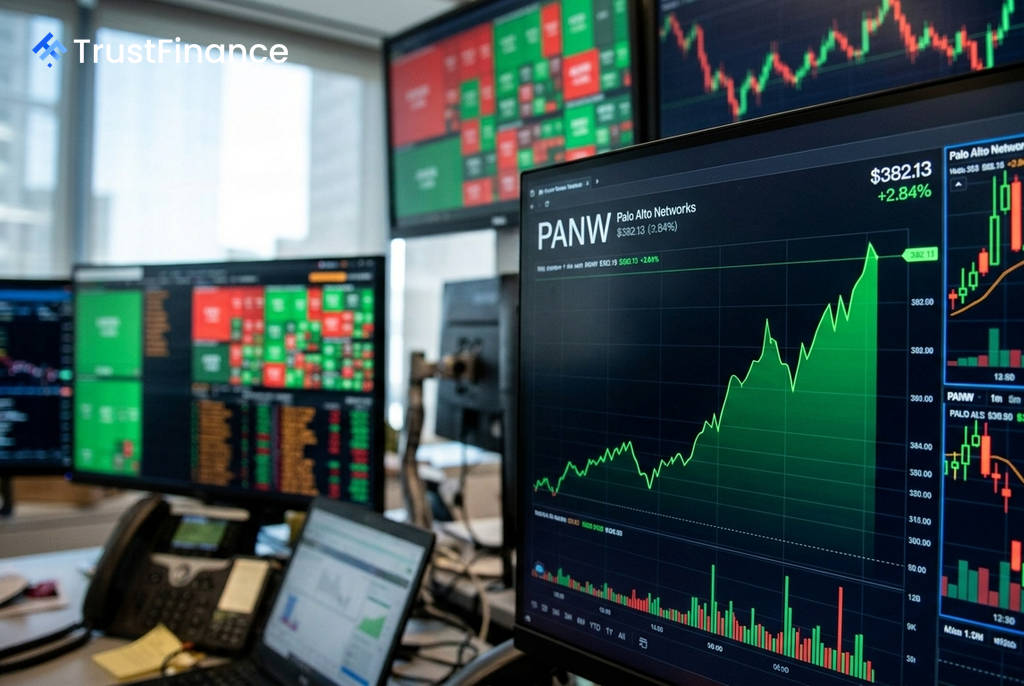
Palo Alto Networks (NASDAQ: PANW) is set to report its fiscal fourth-quarter 2026 earnings today after market close, with its stock trading near all-time highs. The cybersecurity giant enters the print with significant momentum, having surged +107% year-to-date, but faces intense scrutiny over its valuation and a peculiar history of negative stock reactions to strong results.
The Earnings Paradox
A critical pattern has emerged for Palo Alto Networks that investors are watching closely: the stock has sold off after three of its last four earnings reports, despite beating analyst estimates each time. According to data from Investing.com, these post-earnings declines have been significant, including drops of -8.75% and -6.67% in the previous two quarters, even with positive earnings per share (EPS) surprises.
This trend suggests the market has already priced in flawless execution, a classic "priced for perfection" scenario. For the upcoming report, consensus estimates call for an EPS of $0.98 on revenue of $3.35 billion. However, the historical data indicates that simply beating these figures may not be enough to prevent a sell-the-news reaction.
Stretched Valuation and Analyst Caution
The company's valuation metrics underscore the high expectations. Palo Alto Networks trades at a forward price-to-earnings (P/E) ratio of approximately 105x, a significant premium compared to peers in the technology and cybersecurity sectors. An InvestingPro fair value model cited in the source material suggests the stock's intrinsic value could be around $225.99, implying a potential -40.9% downside from its current price of $382.13.
 Ad
While Wall Street analysts are broadly constructive on the company's long-term prospects, their price targets often lag the stock's recent rally. Several firms, including BTIG and DA Davidson, hold targets below the current trading price. Analysts at DA Davidson noted that for the stock to advance, the company will likely need to show "organic NNARR [Net New Annual Recurring Revenue] upside" and clear momentum from its AI-driven products.
Market Outlook and Key Factors
Despite valuation concerns, the bull case for Palo Alto Networks rests on strong secular tailwinds. Cybersecurity spending remains a top corporate priority, and the rise of AI-driven threats is accelerating demand. Analysts at Evercore ISI noted that partner surveys show a surge in the perceived urgency of AI-related security solutions.
The options market is pricing in a potential post-earnings stock move of 8.6% in either direction, highlighting expectations for volatility. Given the stock's powerful run-up and historical tendency to fall on good news, the company's forward guidance and commentary on future growth drivers will be just as critical as its fourth-quarter results.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.