
Story
J.M. Smucker Stock Hits 52-Week High on Tariff Refund Windfall, Lifts Guidance
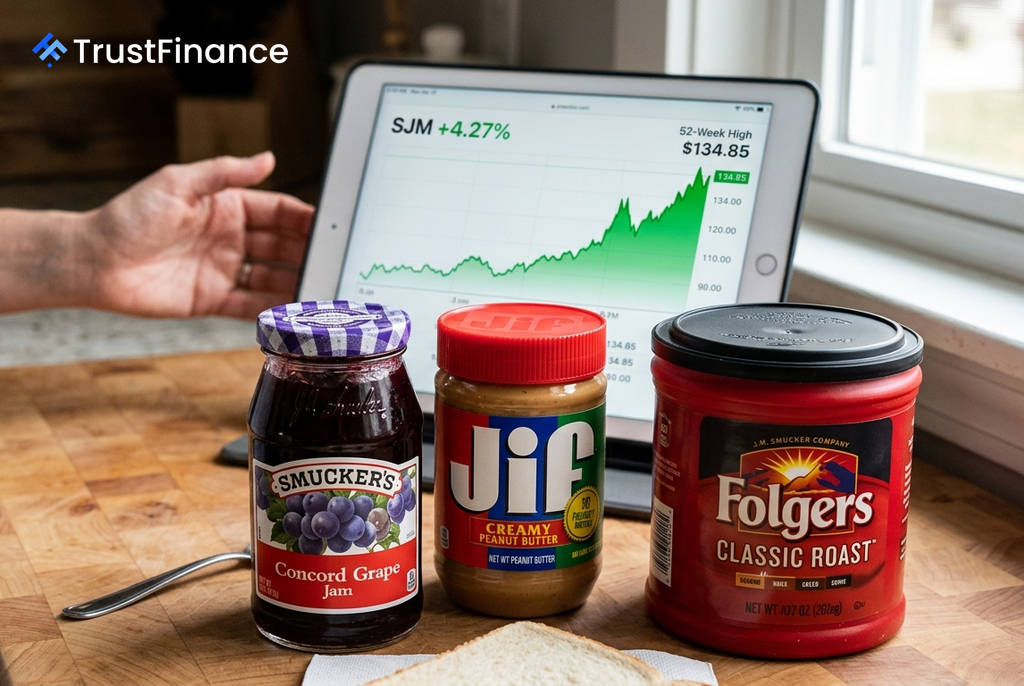
The J.M. Smucker Co. (NYSE: SJM) reported first-quarter earnings that significantly surpassed analyst expectations, fueled by a large, one-time tariff refund. The news sent the company's stock to a 52-week high of $134.85 and prompted management to raise its full-year earnings guidance.
Tariff Refund Fuels Record Quarter
Smucker posted Q1 FY2027 earnings per share (EPS) of $3.24, a 46.6% beat compared to the consensus estimate of $2.21. According to the company, this result was largely driven by a $115 million tariff refund, which contributed approximately $0.84 per share.
Company management clarified that the refund was a one-time event related to a past reconciliation. For the full fiscal year, the net benefit from tariffs is expected to be about $0.60 per share after accounting for reinvestments and other costs. Following the strong quarter, Smucker raised its full-year EPS guidance to a range of $10.50 to $11.00, well above the prior Wall Street estimate of $10.05.
Coffee and Uncrustables Drive Growth
Beyond the one-time gain, Smucker saw robust performance in key divisions, demonstrating underlying operational strength. The U.S. Retail Coffee segment was a standout performer, with sales rising 13% to $807.8 million and segment profit soaring 124%.
Other growth drivers included:
 Ad
- Uncrustables: The frozen sandwich brand delivered 12% net sales growth, leading management to upgrade its full-year growth outlook from mid-single digits to high single digits. The brand is on track to surpass $1 billion in annual sales.
- Café Bustelo: The coffee brand also posted strong results with 23% sales growth.
Balance Sheet Strength and Lingering Concerns
Smucker's financial health improved significantly, with the company reaching its target leverage ratio of 3x a full year ahead of schedule. Net debt to EBITDA fell to 2.9x from 3.8x, and free cash flow swung from a negative $94.9 million a year ago to a positive $337.3 million. This improved balance sheet could allow for future share repurchases.
However, not all segments performed well. The Sweet Baked Snacks division, which includes the Hostess brand, saw sales decline by 7% and profit fall 13%. Management expects the segment to decline by low single digits for the full year, indicating it remains a challenge for the company despite ongoing portfolio simplification.
Market Outlook
Following the report, analysts at UBS and JPMorgan raised their price targets on SJM to $142 and $139, respectively. The key question for investors is whether the company can maintain its earnings momentum in the coming quarters without the benefit of another tariff windfall. The company's guidance for Q2 anticipates low 20% EPS growth, which will be a critical test of its core operational performance.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.