
Story
Chipotle Stock Presents Better Value Than CAVA Amid Market Downturn, Analysis Shows
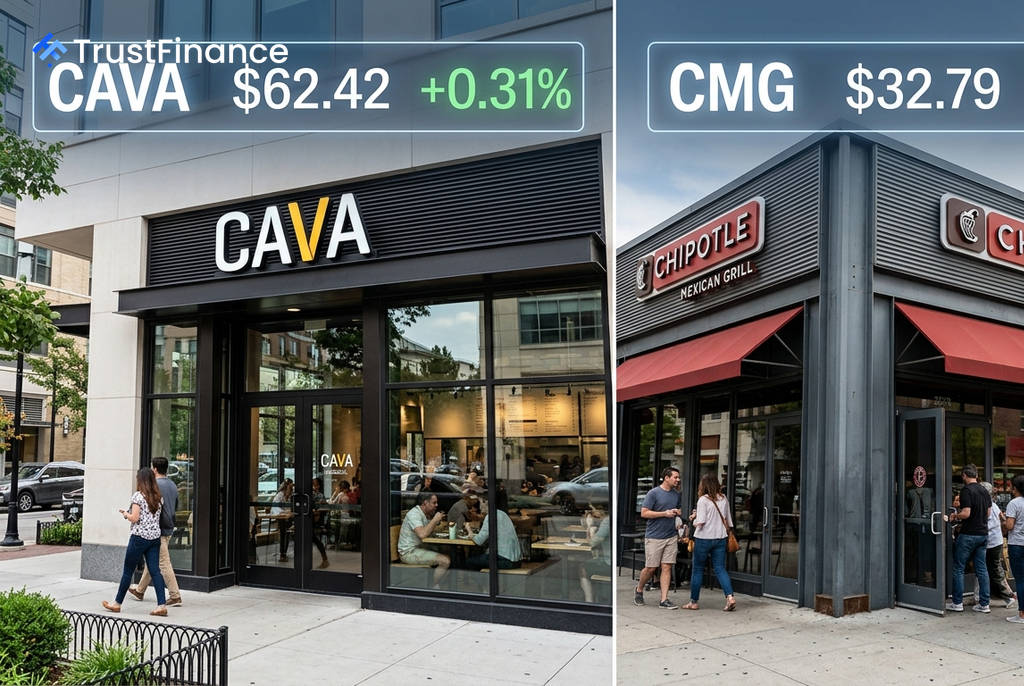
Shares of fast-casual restaurant chains CAVA Group (CAVA) and Chipotle Mexican Grill (CMG) have both experienced significant downturns over the past year, but a closer look at their underlying financial data reveals two vastly different investment profiles. According to an analysis by Investing.com, the established and highly profitable Chipotle currently offers a more compelling value proposition compared to the high-growth but richly valued CAVA.
The Valuation Divide
The core difference between the two companies lies in their current market valuations. While both have seen their stock prices decline, CAVA trades at a significant premium, reflecting investor expectations for future growth, whereas Chipotle is priced more like a mature, profitable enterprise.
Key metrics from the analysis highlight this contrast:
- P/E Ratio (LTM): CAVA trades at 118.6x trailing earnings, while Chipotle is at a more modest 29.2x.
- EV/EBITDA: CAVA’s multiple is 49.6x, more than double Chipotle’s 20.3x.
- Fair Value Upside: An Investing.com model suggests CAVA has only 1.2% upside to its fair value, while Chipotle has a potential 24.1% upside to reach its calculated fair value.
CAVA: A Growth Story Priced for Perfection
 Ad
CAVA's appeal stems from its rapid expansion and impressive 24.1% last-twelve-months revenue growth. With roughly 400 stores compared to Chipotle's more than 3,400, the company has a long runway for growth, and strong unit economics support its expansion strategy. Analysts' price targets reflect this optimism, suggesting an average upside of over 50%.
However, this potential is already reflected in its stock price. The analysis notes that at nearly 119 times earnings, CAVA is priced for flawless execution, leaving no margin for error. The stock’s 30% decline over the past year demonstrates how sensitive it is to any potential setbacks, such as a slowdown in same-store sales or margin pressure.
Chipotle: The Profitable Incumbent
Chipotle, in contrast, represents a proven business model with superior profitability. The company boasts an elite return on equity (ROE) of 49.6% and a net income margin of 11.4%, which is more than double CAVA’s 4.8%. This financial strength allows it to generate significant free cash flow and return capital to shareholders.
While Chipotle faces its own challenges, including slower revenue growth of 7.3% and concerns over labor costs, its valuation provides a cushion. The stock’s potential 24.1% upside to its fair value suggests that current market concerns may be overly discounted, presenting a more favorable risk/reward balance for value-oriented investors, according to the source's analysis.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.