
Story
Becton Dickinson, McCormick & Co. Flagged for Valuation and Dividend Growth
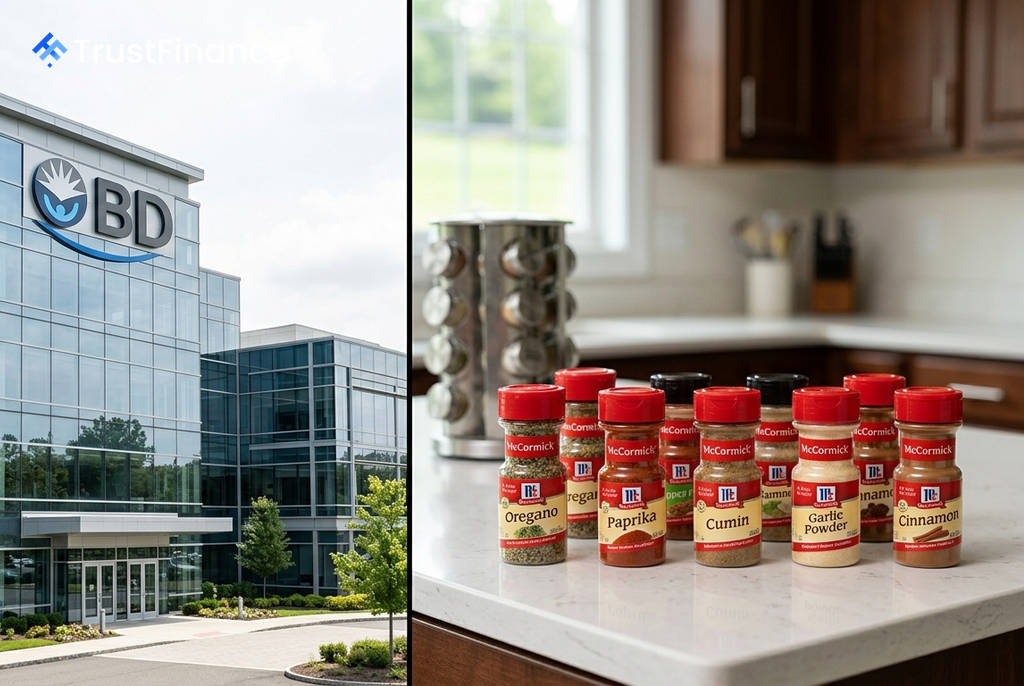
An analysis by Investing.com has highlighted medical device manufacturer Becton Dickinson (NYSE: BDX) and consumer staples firm McCormick & Co. (NYSE: MKC) as notable opportunities among the S&P 500's Dividend Aristocrats, based on a combination of valuation, financial health, and dividend quality.
Key Findings of the Analysis
The report screened for companies with at least 25 consecutive years of dividend increases, focusing on metrics such as potential upside to fair value, dividend growth rates, and financial stability. Becton Dickinson was distinguished for its significant valuation discount combined with strong financial health, while McCormick was noted for its low earnings multiple and robust dividend growth.
According to the analysis:
- Becton Dickinson was cited for a potential fair value upside of 32.4%, the highest among screened companies rated with "Great" financial health.
- McCormick & Co. was highlighted for having the highest five-year dividend compound annual growth rate (CAGR) at 7.1% among the top picks, paired with a low price-to-earnings (P/E) ratio.
Becton Dickinson: A 'Dividend King'
 Ad
The report points to Becton Dickinson's 55-year streak of consecutive dividend hikes, a track record that places it in the elite category of "Dividend Kings." The company currently offers a 2.7% dividend yield and has grown its dividend at a five-year CAGR of 5.7%, according to the data presented.
Potential strengths for BDX cited in the analysis include its recurring revenue from medical devices and diagnostics. However, the report also noted potential risks, including a relatively high P/E ratio of 26.7x and sector-wide pricing pressures from policy risk.
McCormick: Value in Consumer Staples
For McCormick & Co., the analysis emphasized its 40-year history of dividend growth and a low P/E multiple of just 8.7x. The spice and flavoring company offers a 3.7% dividend yield and a potential fair value upside of 25.3%, according to the report.
The Investing.com analysis suggested McCormick's strong brand portfolio provides pricing power. Potential headwinds mentioned include competition from private-label products and pressure on consumer volumes, which has led to modest revenue growth.
Read next
More on Stocks
FTC Orders Walmart, Uber, Delta to Disclose Data on Personalized Pricing
The U.S. Federal Trade Commission is demanding nine major companies, including leading retail, travel, and gig economy firms, to provide information on how they use consumer data for setting individual prices and wages.

Google Launches Gemini 4 Carbon AI Model to Bolster Cybersecurity Capabilities
Alphabet's Google has unveiled Gemini 4 Carbon, its latest AI model specifically designed for advanced cybersecurity tasks like vulnerability detection and secure code generation. The launch escalates competition with rivals OpenAI and Anthropic in the enterprise AI market.

Oracle Shares Surge After Unveiling $225 Billion Revenue Target for 2030
Oracle stock rose sharply after the company presented a long-term financial outlook targeting at least $225 billion in annual revenue by fiscal 2030, driven by its expanding AI infrastructure business.

DOJ Scrutinizes Nvidia's $12.9B Hugging Face Deal Amid Broader Antitrust Probe, Sources Say
The U.S. Department of Justice is reportedly examining Nvidia's planned $12.93 billion acquisition of AI platform Hugging Face as part of a wider, ongoing antitrust investigation into the chipmaker's market conduct.