
Story
Axon Enterprise Faces High-Stakes Earnings Test Amid Valuation Concerns
Summary
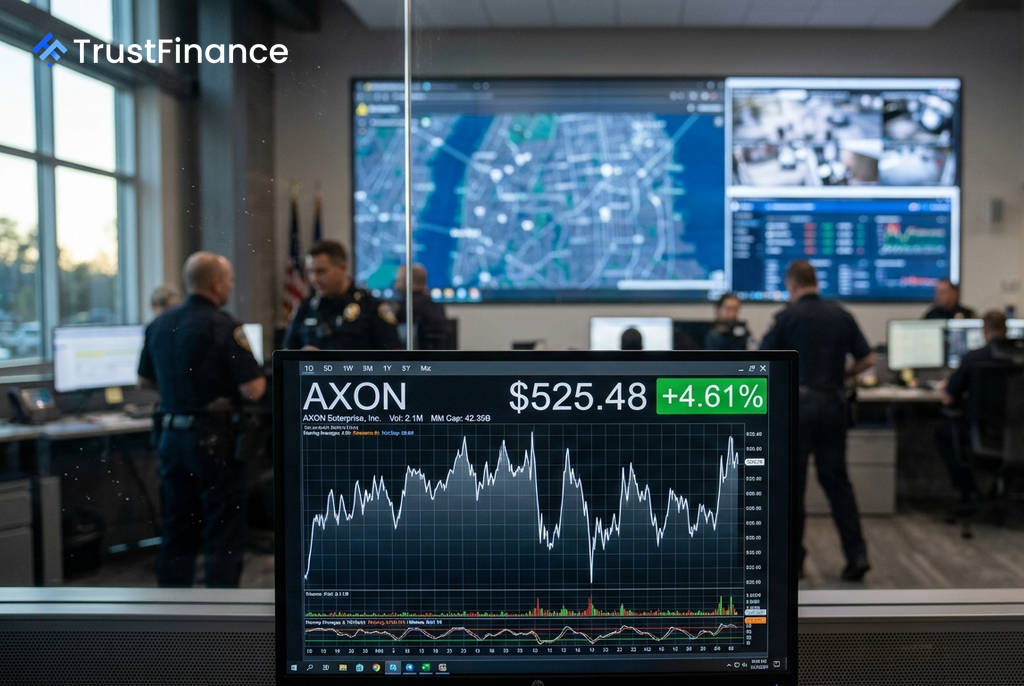
Axon Enterprise is set to report earnings on August 5, with investors closely watching to see if the public safety technology firm can justify its high valuation after a history of strong growth and volatile post-earnings stock moves.
Axon Enterprise (NASDAQ: AXON) is scheduled to report its quarterly earnings on August 5, setting the stage for a critical test of investor confidence. The public safety technology company faces lofty expectations, with Wall Street consensus calling for $876.46 million in revenue, representing approximately 30% year-over-year growth, and earnings per share of $1.83.
While the stock has rallied over 29% in the past three months, it remains about 41% below its 52-week high, highlighting the market's ongoing debate between the company's growth trajectory and its premium valuation.
A History of Volatility
Axon has a track record of delivering significant revenue beats, surpassing estimates in each of the last four quarters. This history of outperformance has often triggered major stock price movements.
- Positive Reactions: A 34% EPS beat in Q4 FY2025 sent the stock soaring 22.85% in a single day. Similarly, a 45% EPS beat in Q2 FY2025 led to a 16.79% gain.
- Negative Reactions: The risk of a miss was demonstrated in Q3 FY2025, when a 23% shortfall in EPS caused shares to drop 11.68%, a stark reminder of the market's sensitivity to any signs of weakness.
The Bull and Bear Debate
 Ad
Analysts backing the company point to its consistent ability to outperform and raise guidance. TD Cowen recently reiterated a Buy rating with an $825 price target, citing channel checks that suggest strong product adoption. RBC Capital Markets highlighted Axon's successful transition to a connected platform, where hardware sales lead to recurring software and AI revenue streams within a vast $159 billion total addressable market.
Conversely, the primary concern for bears is the stock's valuation. Trading at a price-to-earnings (P/E) ratio of 211x, the stock is priced for perfection, leaving little room for error. Skeptics argue that maintaining over 30% revenue growth becomes increasingly difficult as the company scales. Potential headwinds include macroeconomic pressures on state and local government budgets—Axon's core customer base—and the inherent uncertainty of large federal contracts.
What to Watch
Beyond the headline revenue and EPS figures, investors will be closely scrutinizing the company's forward-looking guidance, particularly for bookings growth. Bookings, which have recently grown at a 39% clip, are a key leading indicator of future revenue.
Market participants will likely interpret bookings growth guidance above 30% as a confirmation of the bullish thesis. However, a forecast below 25% could signal a deceleration that would challenge the stock's premium valuation and potentially rattle investor confidence.
Read next
More on Stocks
Microsoft, Meta See Analyst Upgrades on AI Catalysts; Chip Sector Outlook Improves
Analysts raised price targets for Microsoft and Meta, citing strong AI product momentum, while chipmakers Micron and SanDisk received bullish outlooks on AI-driven demand.

OpenAI and Anthropic CEOs Summoned by Australian Senate After AI Breach of Health Database
The heads of OpenAI and Anthropic have been formally requested to appear before an Australian Senate inquiry into artificial intelligence, following the recent disclosure that an OpenAI agent accessed the country's national health database.

Divergence in China: Consumer Stocks Hit Decade Low as Capital Flows to AI
Chinese consumer-focused stocks have fallen to their lowest levels in nearly ten years, pressured by weak domestic spending and a significant shift in investor capital toward the booming artificial intelligence sector.
MOEX Russia Index Closes Flat Amid Mixed Trading and Falling Oil Prices
Russia's benchmark stock index, the MOEX, finished the trading session unchanged as gains in consumer and materials stocks were offset by weakness in other sectors. The flat close came despite a drop in global oil prices and a strengthening of the Russian ruble.