
Story
Analysis: Deckers Outshines Nike on Key Growth and Value Metrics

Summary
A fundamental comparison of Nike and Deckers Outdoor Corporation reveals a stark divergence, with Deckers showing superior growth, profitability, and valuation while Nike grapples with shrinking margins and declining revenue.
A head-to-head analysis of financial data shows a significant and growing divergence between footwear giants Nike (NKE) and Deckers Outdoor Corporation (DECK). According to a comparative analysis by Investing.com, Deckers is outperforming Nike on nearly every key metric related to value and quality, challenging the traditional view of the two as comparable industry players.
The Fundamental Divide
The data, compiled from the companies' fiscal year-end reports, highlights Deckers' lead in profitability and valuation. The analysis points to a structural break rather than a temporary market fluctuation.
Key comparative metrics include:
- Valuation: Deckers trades at a forward price-to-earnings (P/E) ratio of 10.7x, compared to Nike's 21.0x.
- Profitability: Deckers boasts a net income margin of 18.7% and a return on equity (ROE) of 42.6%, dwarfing Nike's 6.7% and 22.1%, respectively.
- Cash Flow: Deckers' free cash flow (FCF) yield is a robust 10.3%, more than double Nike's 4.1%.
- Balance Sheet: Nike's debt-to-equity ratio stands at 74.3%, while Deckers maintains a much lower leverage of 20.5%.
Deckers' Compounding Growth
Deckers has demonstrated a rare combination of rapid growth and expanding margins, according to the analysis. The company's revenue has surged nearly 80% over four years, growing from $3.15 billion to $5.47 billion, while its gross margin widened from 51.0% to 57.7% over the same period.
This performance has earned it a consensus analyst price target implying +50.3% upside. The Investing.com analysis characterizes Deckers as a "growth stock masquerading as a value stock" given its strong financial health and modest P/E multiple.
 Ad
Nike's Turnaround Challenge
In contrast, Nike appears to be a deep-value play contingent on a significant operational turnaround. The company's net income margin has been halved from 12.9% in fiscal 2022 to 6.7% in fiscal 2026, and its revenue has declined since peaking in fiscal 2024.
A negative PEG ratio of -6.23 underscores expectations of shrinking earnings. While Nike's 4.5% dividend yield may offer a cushion for investors, the analysis suggests that a bet on the stock is a high-patience play with no guaranteed payoff, as the company works to re-establish its market leadership.
Market Implications
The fundamental split between the two companies complicates traditional investment strategies like pairs trading, which relies on the mean reversion of two correlated stocks. The analysis notes that while both stocks may move together on broad market-risk days, their underlying business trajectories are now fundamentally different.
This suggests that the performance gap is not temporary mispricing but a re-rating based on diverging operational success. The data indicates a standalone investment in Deckers is a fundamentally cleaner trade based on current metrics, while an investment in Nike carries the risks associated with a major corporate recovery effort.
Read next
More on Stocks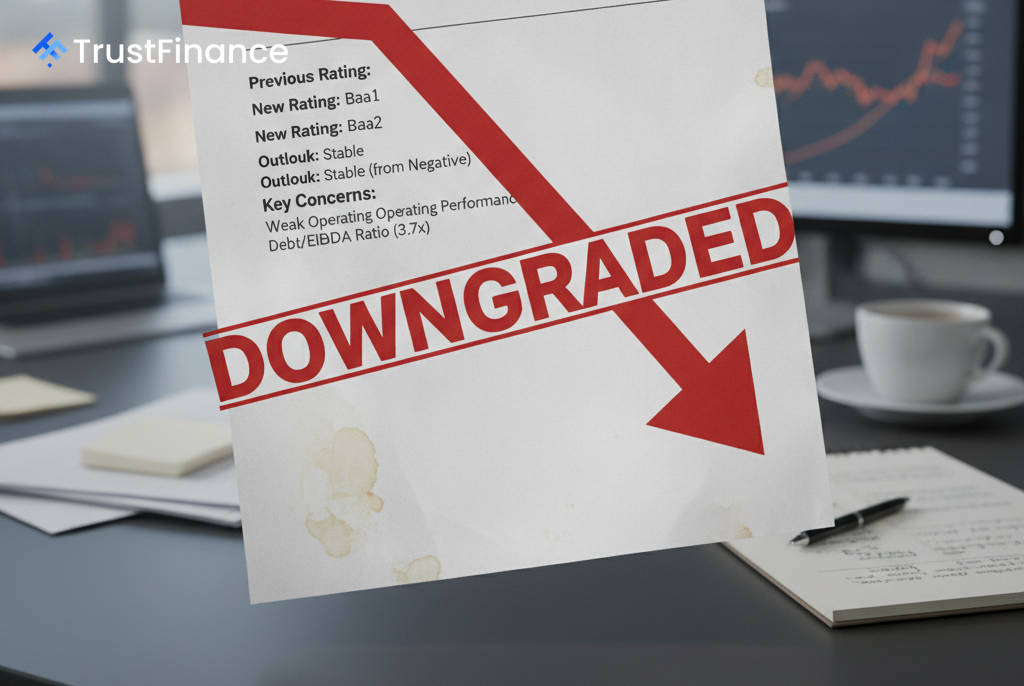
Moody's Downgrades Mondi to Baa2 on Weakened Credit Metrics Amid Market Downturn
The ratings agency lowered Mondi's rating from Baa1, citing a prolonged downturn in the paper and packaging markets that has weakened the company's earnings, cash flow, and key financial ratios.
Pirelli Board Approves €1 Billion Expansion of Georgia Tire Plant
Pirelli will invest €1 billion to expand its Rome, Georgia, manufacturing facility, aiming to boost production of high-value tires and create approximately 1,000 new jobs.
Treasury Yields Rise as Traders Increase Bets on Another Fed Rate Hike
U.S. Treasury yields climbed on Tuesday, with the policy-sensitive 2-year note hitting a fresh two-year high, as markets priced in a greater than 50% chance of another Federal Reserve interest rate increase in October.

Amgen, Vicor Surge While Financials and Fitness Stocks Lag in Divergent Market Session
Amgen and Vicor Corp. were among Tuesday's top gainers, leading a day of mixed performance where significant rallies in some stocks contrasted with sharp declines in others, including LPL Financial and Planet Fitness.